admin
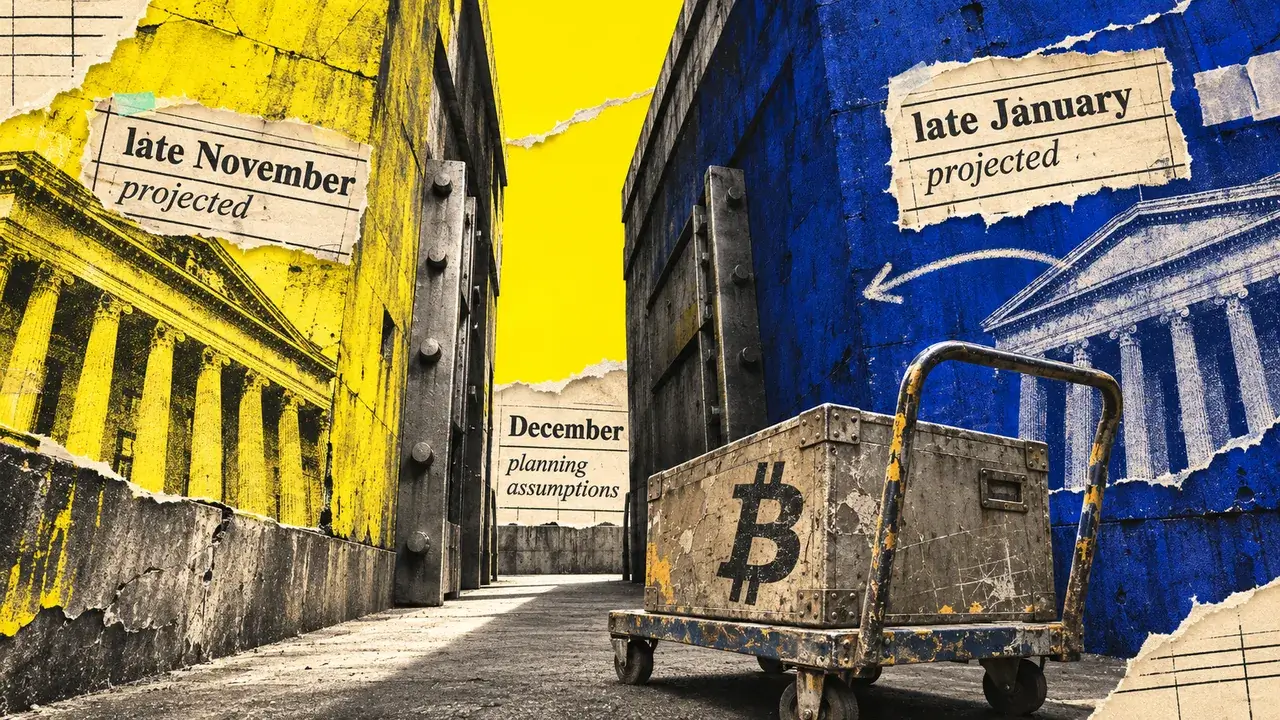
The United States Department of the Treasury’s latest financing calendar has ignited discussions about potential liquidity shifts in the cryptocurrency market, particularly for Bitcoin. Projections indicate a possible window for increased liquidity in December, framed by anticipated peaks in the Treasury’s cash balance on either side of the month. The Treasury’s November 4th refunding statement outlines expectations for cash balances to approach $1,025 billion in late November and again in late January, with a notable dip projected by the end of December. This sequence suggests a crucial period where the Treasury’s spending patterns could influence the broader financial system, potentially impacting digital asset markets.
The core of this analysis lies in the intricate interplay between the Treasury’s operating account at the Federal Reserve, often referred to as the Treasury General Account (TGA), and the flow of reserves within the banking system. When the Treasury draws down its balance in the TGA, it essentially injects liquidity into the banking system, as funds are transferred to commercial banks. Conversely, when the Treasury collects taxes or issues debt, it pulls cash out of circulation, reducing bank reserves. The Treasury’s planned reduction in bill auction sizes during December, partly attributed to anticipated tax receipts, presents a complex scenario. While smaller auction sizes might typically suggest less debt issuance and potentially more available cash, the concurrent influx of tax revenue moves cash in the opposite direction. Therefore, December’s net cash movement, encompassing both spending and receipts, is poised to be the first critical test of whether the projected reserve relief materializes.
Two Cash Peaks Frame a Crucial December Window
The Treasury’s refunding statement, released on November 4th, offers detailed projections for the TGA. The operating account at the Federal Reserve is estimated to reach a peak of approximately $1,025 billion, with a margin of error of $50 billion, in both late November 2026 and late January 2027. Within this broader cycle, the Treasury anticipates holding an estimated balance of $850 billion at the close of December. This projected drawdown from the late November peak to the end-of-December figure represents a significant potential injection of liquidity.
Further bolstering these projections, the Treasury’s November 2nd borrowing estimates also paint a picture of substantial cash balances, assuming a $1 trillion cash level by the end of March 2027. This suggests a sustained period of high cash reserves, with December serving as a temporary dip within a larger replenishment cycle.
The structure of Treasury bill auctions introduces a seasonal dynamic to this cash flow. The Treasury plans to maintain current benchmark bill auction sizes through late November, potentially including a short-dated cash management bill issuance around the month’s end. However, the crucial shift is expected in December, when the Treasury intends to reduce the sizes of shorter-dated bill auctions. This reduction is directly linked to the anticipated corporate and non-withheld tax receipts, which are projected to flow into the Treasury’s coffers around the middle of the month.
Conversely, January is expected to witness a reversal of this issuance trend. As seasonal fiscal outflows, such as government payments, increase, the Treasury anticipates raising auction sizes across the bill maturity spectrum. This proactive adjustment aims to manage the government’s borrowing needs and maintain adequate cash reserves. It is important to note that the Treasury retains the flexibility to adjust these plans in response to evolving borrowing requirements and market conditions.
The confluence of these projected cash peaks and the strategic sequencing of bill auctions adds a granular timing element to the broader quarter-end framework previously analyzed for potential liquidity impacts on digital assets. A December respite, therefore, could be a temporary easing within a larger replenishment cycle, rather than an indicator of sustained, long-term liquidity expansion.
The Mechanics of Reserve Relief: Why Fewer Bills Alone Aren’t Enough
Understanding how Treasury cash flows translate into broader financial liquidity requires a look at the "reserve channel," as explained by the Federal Reserve’s accounting principles. When the Treasury makes payments from its account at the Federal Reserve, these funds are transferred to the accounts of commercial banks held at the central bank. This process directly increases the reserves available to these banks, assuming all other factors remain constant. These reserves are crucial for banks to meet regulatory requirements, facilitate lending, and generally maintain the smooth functioning of the financial system.
Conversely, when individuals and corporations pay taxes, these funds are transferred from commercial bank accounts to the Treasury’s account at the Federal Reserve. This action drains liquidity from the banking system, reducing bank reserves.
This distinction is particularly critical when analyzing the implications for December. While the Treasury’s intention to reduce bill auction sizes might initially suggest less debt issuance and therefore less cash being pulled from the private sector, the concurrent expectation of significant tax receipts complicates the net liquidity picture. These tax receipts, while enabling the Treasury to reduce debt issuance, simultaneously act as a drain on bank reserves. Therefore, a simple reduction in bill auction sizes, in isolation, does not definitively prove that the combined effect of Treasury spending and tax collection will lead to an easing of overall funding conditions.
It is imperative to recognize that all future balance sheet figures are projections or assumptions, not yet realized observations. The timing of these events is not always perfectly synchronized. Furthermore, external factors, such as tax receipts and other changes on the Federal Reserve’s balance sheet, can offset any potential reserve support provided by Treasury spending. Crucially, the analysis of Treasury financing does not, in itself, establish any direct causality for Bitcoin buying activity or subsequent price movements.
The realized net movement in the Treasury’s operating account already incorporates the combined effects of financing activities, tax receipts, and government spending. To then subtract debt issuance from this net cash change would be a form of double-counting the financing impact. Other significant factors influencing bank reserves include Federal Reserve open market operations (purchases and sales of securities), lending facilities, and fluctuations in currency in circulation, reverse repurchase agreements, and other deposits held at the Fed. These elements can all alter the final aggregate reserve total in the banking system.
Moreover, the stated gross size of Treasury’s refunding operations should not be interpreted as entirely representing new demand for cash from the private sector. For instance, the Treasury plans to issue approximately $125 billion in securities against roughly $97 billion in privately held notes and bonds maturing on November 15th. This means that approximately $28 billion represents new cash being raised from private investors. The auctions for the three-year, ten-year, and thirty-year Treasury notes are scheduled for November 9th, 10th, and 12th, respectively, with settlements occurring on November 16th, which is the relevant date for this cash exchange.
The December Test for Bitcoin Liquidity
The most recent publicly available data from the Treasury’s operating cash balance report, released early on November 5th, indicated a closing cash balance of $938 billion on November 3rd. In parallel, the Secured Overnight Financing Rate (SOFR), a key benchmark for overnight borrowing against Treasury collateral, stood at 3.97% on November 3rd, the latest date for which this data was available. While these figures provide a snapshot of current conditions, they represent dated baselines rather than a synchronized signal of easing funding conditions.
The Federal Reserve’s balance sheet release from October 29th reported total bank reserves at approximately $2,895 billion as of Wednesday, October 28th. These disparate data points underscore the challenge of identifying a precise moment of liquidity shift.
For market participants, particularly those focused on cryptocurrencies like Bitcoin, the critical test will commence with the observation of actual Treasury cash movements. This will be followed by an assessment of the subsequent reserve levels and overall funding conditions after accounting for other changes on the Federal Reserve’s balance sheet. It is essential to reiterate that even if easier funding conditions are observed, the decision by market participants to allocate capital towards Bitcoin remains a separate and unproven step.
A realized decline in Treasury’s cash balance throughout December, coupled with stable or increasing bank reserves and demonstrably easier funding rates, would lend significant support to the thesis of temporary liquidity relief. Conversely, if any cash drawdown by the Treasury is offset by other factors on the Fed’s balance sheet that drain liquidity, the positive impact on reserves would be diminished or negated. Furthermore, any observed improvement in December could face renewed scrutiny if the Treasury begins to rebuild its cash balance towards the projected late-January peak, potentially by increasing bill auction sizes once more.
Broader Implications and Market Sentiments
The Treasury’s financing calendar and its potential impact on liquidity are closely watched by a wide range of financial market participants, including institutional investors, hedge funds, and central banks. While the direct link between Treasury cash flows and Bitcoin’s price action is complex and often debated, periods of increased liquidity in the broader financial system have historically coincided with heightened risk appetite, which can benefit assets like cryptocurrencies.
Analysts at various financial institutions have been scrutinizing the Treasury’s debt management strategy for signs of potential shifts in market liquidity. Some have pointed to the Treasury’s reliance on issuing short-term debt, such as Treasury bills, as a key factor influencing the demand for liquidity from money market funds and other short-term investors. The planned reduction in bill auction sizes in December, therefore, could ease pressure on these funding markets.
However, the prevailing sentiment remains one of cautious observation. The Treasury’s projected cash peaks and troughs are subject to numerous variables, including the pace of economic growth, inflation trends, and future fiscal policy decisions. Unexpected developments, such as a sudden increase in government spending or a slowdown in tax revenue, could alter the projected trajectory of the TGA and, consequently, the availability of liquidity.
For Bitcoin specifically, the narrative of "liquidity on" or "liquidity off" has become a significant driver of market sentiment. Investors often look for signals of ample liquidity in the financial system as a precursor to increased investment in riskier assets. The Treasury’s December financing plans, while offering a potential short-term window of relief, are part of a much larger and more complex macroeconomic picture. The ultimate impact on Bitcoin will depend not only on the Treasury’s actions but also on the Federal Reserve’s monetary policy stance, global economic conditions, and the specific risk appetite of investors. The upcoming weeks will be crucial in observing whether the projected cash drawdown materializes and how it influences the broader financial landscape and, potentially, the cryptocurrency markets.