admin
A comprehensive new study examining the trading of stock tokens over weekends has revealed that their prices do not consistently or reliably predict the direction of the conventional stock market’s opening on the following Monday. The analysis, conducted by blockchain data provider Bitquery, scrutinized the performance of tokenized stocks representing 121 underlying equities across 17 weekends, concluding that the supposed advantage of continuous weekend trading for forecasting purposes is not yet realized.
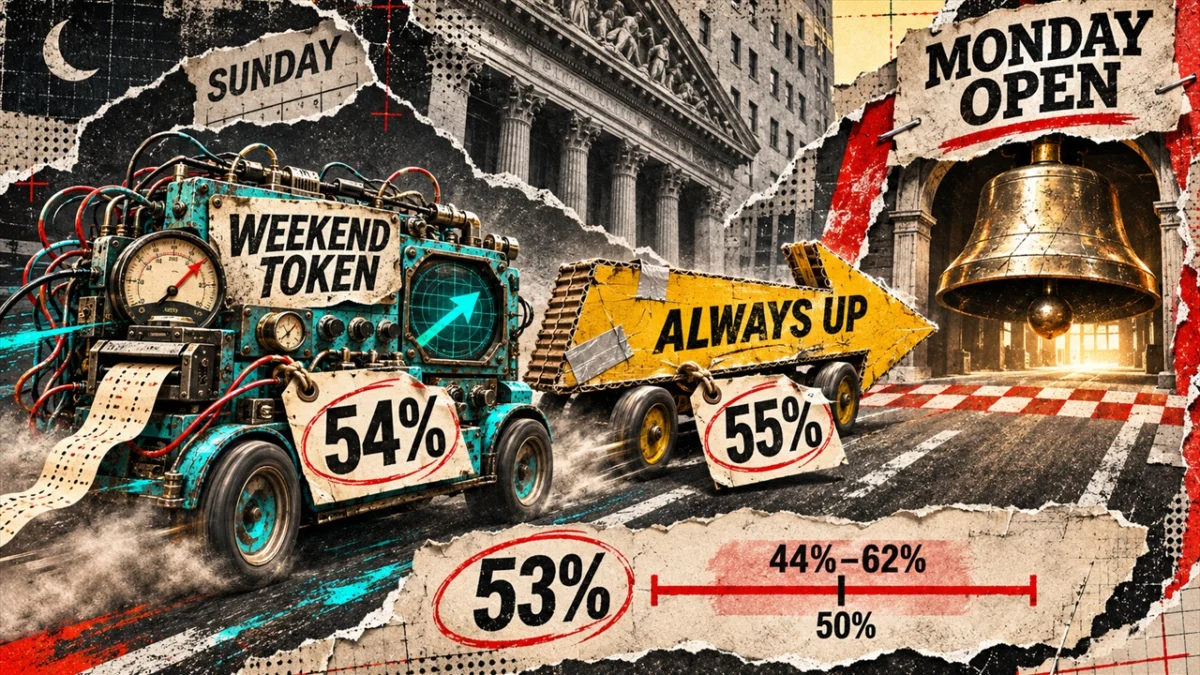
The findings challenge the notion that extended trading hours for tokenized assets translate into superior predictive power for the traditional equity markets. Bitquery’s Nov. 3 analysis, which tracked token movements from July 10 through October 30, found that Sunday token prices, measured just before the reopening of equity-index futures, correctly predicted the direction of only 54% of qualifying stock market openings. This success rate is barely above a simple strategy of predicting that every stock would open higher, which achieved a 55% accuracy.
Unpacking the Weekend Price Test Methodology
Bitquery’s research meticulously tracked 791 stock-opening observations across the selected 121 stocks over the 17-week period. The core of the directional test focused on openings that exhibited a significant move of at least 0.5% from their Friday closing price. Out of these 533 qualifying openings, token movements accurately indicated the direction in 286 instances. In contrast, the benchmark strategy of assuming a universally higher opening correctly predicted 291 of these moves. Given that more stocks tended to rise than fall during the study period, a simple 50% coin-toss benchmark would have been insufficient to gauge the true predictive capability of the tokens.
To provide a more nuanced evaluation, the study also employed balanced accuracy, a metric that averages the success rate for both upward and downward movements. In this regard, the stock tokens scored 53% balanced accuracy. The researchers reported a 95% confidence interval for this figure, placing it between 44% and 62%. This indicates a substantial degree of uncertainty surrounding the token prices’ predictive accuracy.
Beyond directional predictions, the study also assessed the magnitude of price discrepancies. Across all 791 observations, including those with smaller price fluctuations, the median error when using token moves to predict the next opening was 1.2%. This contrasts with a median error of 0.9% when assuming the stock would simply open at its Friday closing price. Bitquery calculated this “excess error” attributable to token price movements at 0.3%, with a 95% range of 0.2% to 0.5%. This suggests that relying on token prices, on average, introduced a slightly larger forecasting error compared to a static prediction.
Timing is Crucial: The Sunday 6 PM ET Cutoff
A critical element of Bitquery’s methodology was the timing of the token price readings. The primary test utilized token prices recorded just before 6 p.m. Eastern Time on Sunday. This specific cutoff was chosen deliberately as it aligns with the reopening time for equity-index futures, a key market indicator. The rationale behind this timing was to assess whether token prices, taken just before the futures market began to reflect new information, could offer a predictive edge.
The study acknowledged that a later cutoff for token prices could potentially incorporate information already disseminated through the futures market, thus diminishing any independent forecasting value. To explore this, a separate check was conducted using token prices recorded just before 8 p.m. ET. This later reading yielded a balanced accuracy of 59% across 220 qualifying openings, with a 95% range of 53% to 65%. However, this adjusted analysis also involved a higher weekend trading volume threshold of $1 million and a modified movement filter, making direct comparisons with the earlier test challenging.
Filtering and Exclusions: Ensuring Robustness
To ensure the integrity of its analysis, Bitquery implemented several filtering criteria. For a stock token to be included in the directional test, it needed to have at least $10,000 in weekend trading volume and execute at least one trade in the hour leading up to each specified cutoff time. Furthermore, openings affected by significant corporate actions such as stock splits or ex-dividend dates were excluded. The study also deliberately omitted crypto-sensitive stocks like Strategy and Coinbase, recognizing that their prices might be disproportionately influenced by broader cryptocurrency market dynamics rather than solely by the underlying equity’s fundamentals. The final weighted analysis combined data from different issuers based on their weekend trading volumes.
The researchers noted that previous perpetual market research had reported improved forecasts from final weekend prices in different samples. However, they emphasized that differences in the instruments studied, the liquidity filters applied, and the observation times used in those earlier studies prevent a direct comparison or rebuttal of their current findings.
Nasdaq’s Move Towards Extended Trading Hours
The findings from Bitquery’s study gain added relevance in light of recent developments from Nasdaq. On October 30, Nasdaq announced an anticipated transition to 23-hour, five-day trading for certain securities, tentatively scheduled for December 6. This expansion, pending the readiness of clearing and market-data infrastructure and subject to regulatory approval, aims to significantly narrow the gap between traditional trading hours and the continuous availability of tokenized assets. Nasdaq’s member implementation notice outlines a new overnight session from 9 p.m. to 4 a.m. ET, which will necessitate new member ports.
If Nasdaq’s initiative proceeds as planned, the extended conventional weekday hours could diminish one of the perceived advantages of stock tokens: continuous trading access. For investors whose brokers and jurisdictions permit trading through both avenues, the need for weekend trading of tokenized stocks as a primary means of capturing pre-market information might lessen. This could lead to a more unified market where price discovery is more synchronized across different trading venues.
However, it is important to distinguish between extended trading hours and other potential benefits of stock tokens. The ability to hold tokens in a blockchain wallet, offering a degree of self-custody, and the potential for greater transparency in transaction records remain distinct advantages that are not directly addressed by Nasdaq’s trading hour expansion.
Ownership Rights and Jurisdictional Limitations
A significant caveat in the realm of stock tokens, as highlighted by Kraken’s xStocks disclosure, pertains to ownership and rights. Kraken’s service, for instance, explicitly excludes users from the United States, Canada, the United Kingdom, and Australia. While it permits compatible wallet withdrawals, it clearly states that holders of these tokens "lack ownership and voting rights in the underlying shares." This distinction is crucial for investors to understand, as they are essentially trading a derivative or a synthetic representation of the stock, not the equity itself. This lack of direct ownership can have implications for dividend payments, corporate actions, and the fundamental rights associated with holding actual shares.
Implications for the Future of Trading
The Bitquery study underscores a fundamental point: access to trading and the generation of truly useful forecasting information are distinct claims. While stock tokens offer the allure of trading outside traditional market hours, the current evidence suggests that this extended access has not yet translated into a demonstrable predictive edge over established market indicators.
The study’s limitations, as self-reported, include being based on vendor research rather than independent raw-data replication, the absence of a futures-price benchmark for all comparisons, and the lack of cost-adjusted strategy analysis. The evolving nature of the filters and cutoffs also adds complexity to direct comparisons across different phases of the study.
Looking ahead, the next crucial steps in evaluating the utility of stock tokens for forecasting would involve studies that maintain consistent timing and eligibility criteria, rigorously compare performance against available market benchmarks, and crucially, measure executable results after accounting for trading costs. Until such comprehensive evidence emerges, the ability to trade stock tokens over the weekend should not be conflated with a proven advantage in forecasting the direction of the stock market’s next opening. The landscape of financial markets is continually evolving, and the integration of blockchain technology into traditional asset classes presents both opportunities and challenges that require careful, data-driven analysis. The journey from offering continuous trading to providing a reliable forecasting tool for stock tokens is clearly still in its early stages.