Dwi Wanna
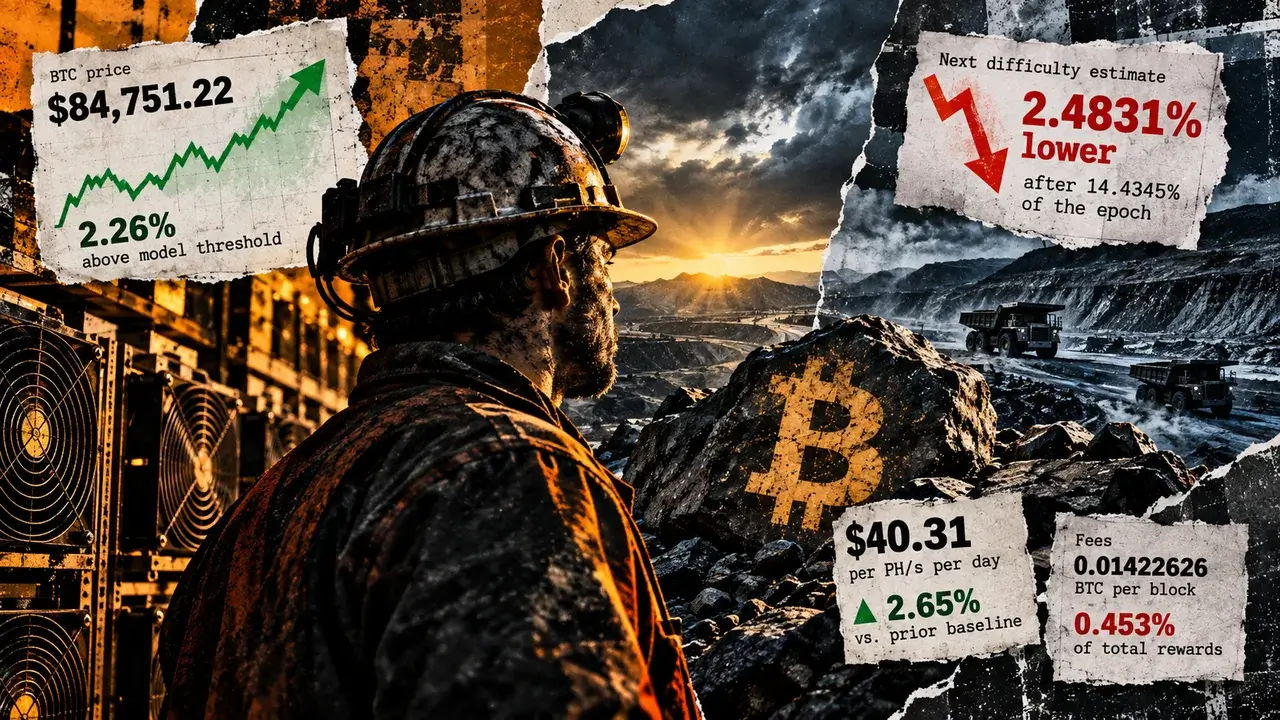
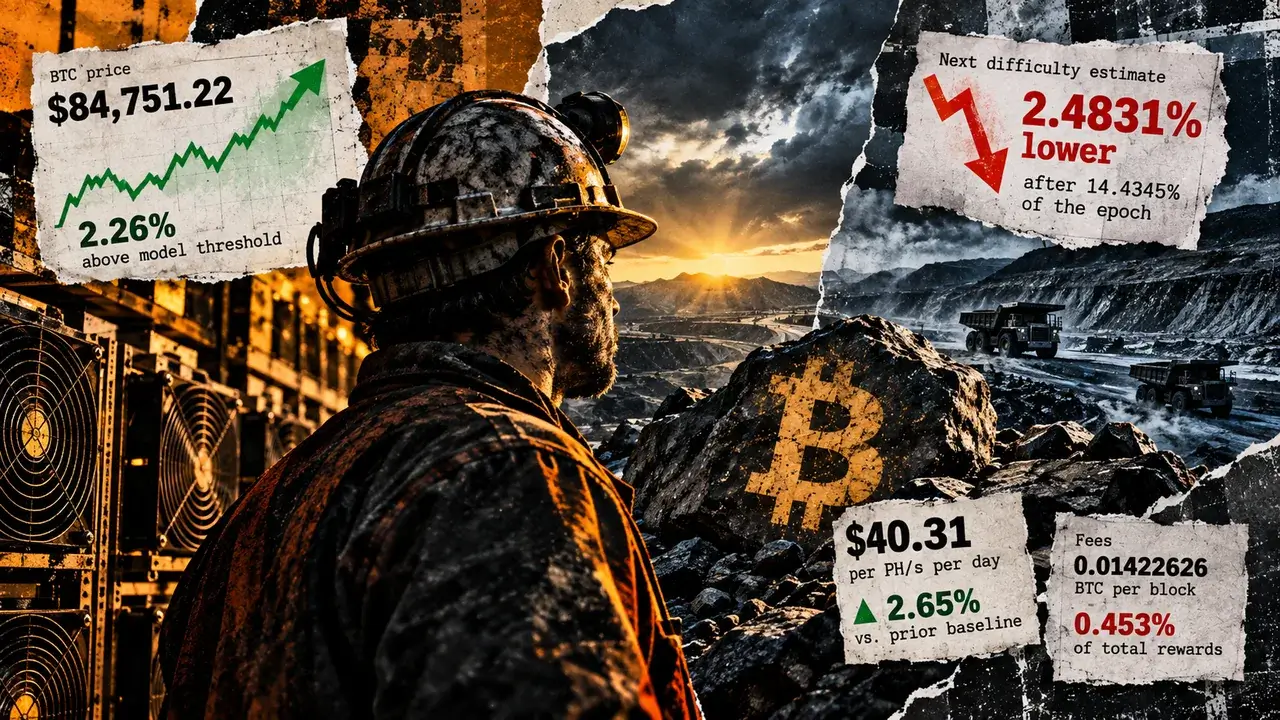
The Bitcoin mining sector experienced a marginal yet significant reprieve following the most recent difficulty retarget, as a sharp increase in the price of Bitcoin (BTC) to $84,751 effectively neutralized the increased costs of network competition. As of late September, the theoretical gross hashprice—a primary metric for measuring miner revenue—rose to approximately $40.31 per petahash per second (PH/s) per day. This figure represents a 2.65% improvement over previous modeled baselines, suggesting that while the network is becoming more difficult to mine, the market value of the rewards is currently sufficient to maintain a modest revenue cushion for efficient operators.
This economic shift comes on the heels of the September 19 difficulty adjustment, which saw the network’s complexity rise by 4.1634%. Under the current reward structure, where the block subsidy stands at 3.125 BTC following the April 2024 halving, miners are increasingly sensitive to the interplay between network difficulty and market price. The recent rally to the mid-$84,000 range has provided the necessary "breakeven" momentum required to offset the increased computational work required to secure the blockchain.
The September 19 Difficulty Adjustment and Revenue Thresholds
The Bitcoin network undergoes a difficulty adjustment approximately every 2,016 blocks, or roughly every two weeks, to ensure that block production remains consistent at ten-minute intervals. On September 19, at block 967,680, the network difficulty climbed from 127.451 trillion to 132.757 trillion. This 4.16% increase meant that miners had to expend more energy and computing power to earn the same amount of Bitcoin.
Prior to this adjustment, market analysts had calculated a "neutralization threshold." A September 15 analysis indicated that Bitcoin would need to reach a price of roughly $82,877 to counteract the revenue-per-hash impact of the then-projected difficulty hike. Because the realized adjustment was slightly less severe than the most aggressive projections, and because the BTC price surged to $84,751, the industry saw a net improvement in gross revenue per unit of computing power.
At the current price of $84,751, Bitcoin is trading roughly 2.26% above the prior model’s threshold. When factoring in the realized difficulty and the current price-to-difficulty ratio, the economic environment for miners has improved by approximately 2.79% relative to mid-September inputs. This creates a temporary "relief zone" for mining firms that were previously facing a tightening margin squeeze.
Analyzing Hashprice and the Role of Transaction Fees
The hashprice, currently sitting at $40.31 per PH/s per day, is the most critical barometer for miner health. It is a derivative of the block subsidy, the current network difficulty, the market price of BTC, and the transaction fees collected by miners. While the price rally has bolstered this figure, a closer look at the data reveals that the "fee floor" remains remarkably thin.
In a recent 144-block sample (blocks 967,828 through 967,971), transaction fees contributed only 2.048 BTC to the total rewards pool. This averages out to 0.0142 BTC per block, accounting for a mere 0.45% of total miner rewards. This data underscores a significant vulnerability in the current mining economy: revenue remains overwhelmingly dependent on the block subsidy and the spot price of Bitcoin.
For the mining industry to achieve long-term sustainability, particularly as the block subsidy continues to halve every four years, transaction fees must eventually comprise a larger share of the revenue. Currently, the lack of high-velocity on-chain activity—such as that seen during periods of high Ordinals or Runes minting—means that miners are essentially "price takers" in a market dictated by global liquidity and institutional demand for the underlying asset.
Chronology of Recent Network Performance
The trajectory of the current mining epoch provides a timeline of how the network has responded to shifting hashrate levels:
- September 15: Analysts project a significant difficulty increase, setting a price target of $82,877 to maintain miner revenue parity.
- September 19: The network difficulty adjusts upward by 4.16%, reaching a new record of 132.757 trillion.
- September 20–24: Bitcoin price begins a steady climb, eventually breaking past the $84,000 mark.
- Late September: The network enters the current observation window. Early data from the first 14.43% of the new epoch shows a slowdown in block discovery, with blocks averaging 10 minutes and 25 seconds.
- October 3 (Projected): The next difficulty retarget is estimated to result in a 2.48% decrease, though this remains a highly volatile projection.
The early signal of a 2.48% decline in difficulty is noteworthy but requires cautious interpretation. With only 291 blocks completed out of the 2,016-block epoch, the sample size is too small to definitively prove that miners are shutting down equipment or "curtailing" operations due to high electricity costs.
Stochasticity and the Noise in Early Epoch Data
The science of Bitcoin block discovery is stochastic, meaning it is subject to random variables. Even if the network hashrate remains constant, the time between blocks can vary significantly due to luck. Technical research, including work by Bitcoin Core developer Pieter Wuille and various academic studies on block arrival times, emphasizes that early-epoch difficulty estimates are often "noisy."
Currently, Mempool’s one-month hashrate estimate fluctuates between 826.1 EH/s and 1.053 ZH/s. The current estimate of 937.5 EH/s does not show a "cliff" or a sudden drop-off that would suggest a mass exit of miners from the network. Instead, the slower block pace observed in the first 14% of the epoch likely reflects a standard statistical deviation rather than a fundamental shift in miner behavior.
However, if the 10-minute and 25-second block average persists through 50% or more of the epoch, it would provide stronger evidence of hashrate softening. Such a scenario would lead to a downward difficulty adjustment, which would further improve the hashprice by reducing the amount of work required to secure a block.
Operational Realities and the AI Pivot
While network-wide data provides a macro view of mining economics, it does not account for the vastly different cost structures of individual operators. Profitability is determined by several factors beyond hashprice:
- Fleet Efficiency: Miners using the latest generation hardware, such as the Bitmain Antminer S21 or MicroBT Whatsminer M60 series, have a much lower "joules per terahash" (J/TH) rating, allowing them to remain profitable at lower hashprices.
- Power Contracts: Large-scale miners often operate on fixed-price power purchase agreements (PPAs) or participate in demand-response programs where they are paid to shut down during peak grid stress.
- Capital Structure: Firms with low debt loads are better positioned to weather periods of low hashprice than those with significant financing obligations.
An emerging trend in the sector is the pivot toward High-Performance Computing (HPC) and Artificial Intelligence (AI) infrastructure. Several major publicly traded mining firms have announced multi-billion-dollar commitments to convert portions of their power capacity to support AI workloads. This shift suggests that some operators are seeking to diversify away from the volatility of Bitcoin mining, prioritizing the steady, "rent-like" income of data center operations over the stochastic rewards of the blockchain.
Broader Impact and Industry Implications
The current state of Bitcoin mining reflects a mature, highly competitive industry that is increasingly integrated with global energy and financial markets. The fact that the BTC price rally was able to outpace the difficulty increase is a positive sign for network security. A healthy hashprice prevents "miner capitulation"—a scenario where a large number of operators shut down simultaneously, potentially leading to a "death spiral" of slowing block times and decreasing network security.
However, the "relief" experienced this week is fragile. The reliance on the block subsidy means that any significant pullback in the price of Bitcoin would immediately put sub-efficient miners back into the "margin trap." If the price were to drop back to $75,000, for instance, the 132.757 trillion difficulty would likely force older hardware, such as the S19 series, into negative territory in many jurisdictions.
Furthermore, the lack of transaction fee growth remains a long-term concern for the network’s security budget. As the block subsidy continues to diminish every four years, the network must find a way to incentivize miners through transaction volume. The current 0.45% fee contribution is insufficient to sustain the current level of hashrate in a future with a near-zero block subsidy.
Conclusion: A Fragile Equilibrium
The Bitcoin mining industry is currently in a state of "unsettled relief." The price rally to $84,751 has successfully neutralized the latest difficulty hike, providing a 2.65% boost to theoretical gross revenue per unit of computing power. Yet, the durability of this reprieve depends on three factors: sustained high BTC prices, an eventual increase in on-chain transaction fees, and the confirmation of hashrate trends as the current difficulty epoch matures.
As the industry looks toward the October 3 retarget, observers will be watching to see if the early signal of a 2.48% difficulty decline holds. If it does, it would suggest a slight easing of competition, further aiding miner margins. For now, the network continues to operate at record-high levels of security, supported by a price action that—at least for the moment—is keeping the economics of the "digital gold" rush in the black.