admin
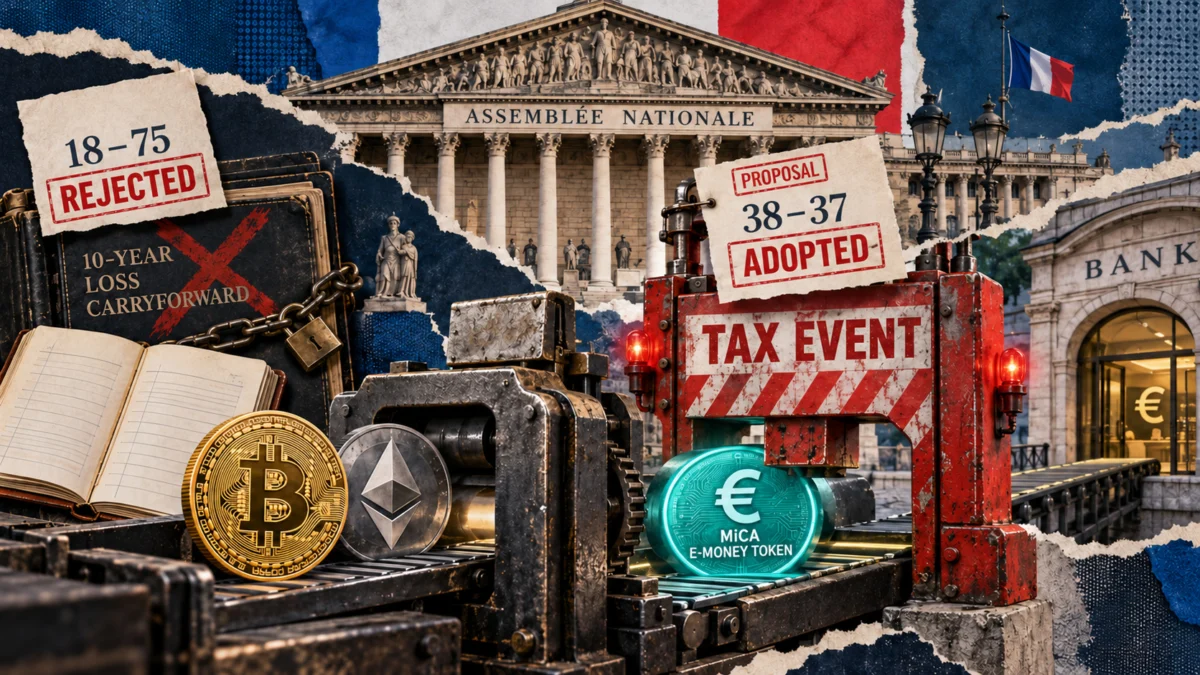
The French National Assembly has taken a significant step in shaping the taxation of digital assets, with members voting on October 16th to approve a proposal that will subject gains from swaps into certain stablecoins to immediate taxation. This decision, made during the first reading of the 2027 finance bill, marks a departure from current tax deferral rules for such transactions. Simultaneously, lawmakers rejected a separate measure that would have allowed cryptocurrency investors to carry forward net losses for a decade, leaving in place existing same-year offset limitations. The proposed changes, if enacted into law, are slated to take effect on January 1, 2027, pending the finalization of the budget.
Key Developments in French Crypto Taxation
The dual votes in the National Assembly represent a pivotal moment for the burgeoning cryptocurrency landscape within France and potentially across the European Union, given France’s role in shaping EU regulatory frameworks. Amendment I-3898, which introduces the tax on gains from swaps into specific stablecoins, passed by a narrow margin of 38 votes in favor to 37 against, with 25 abstentions. This close vote underscores the delicate balance of opinions surrounding digital asset taxation. In contrast, amendment I-3653, proposing a ten-year carryforward for net crypto losses, faced overwhelming opposition, failing by a vote of 75 to 18, with three abstentions.
The provisional text of the 2027 finance bill, as of October 19th, retains the provision concerning stablecoin swaps in Article 4 octies. The ultimate implementation date of January 1, 2027, remains contingent on the bill successfully navigating the legislative process and receiving final enactment.
Understanding the Taxable Event: Stablecoin Swaps
Under the current French tax regime for private investors, a significant portion of crypto-to-crypto exchanges do not trigger an immediate taxable event, provided there is no cash settlement involved. This deferral allows individuals to rebalance their digital asset portfolios, moving from one cryptocurrency to another, without necessarily recognizing capital gains in the year of the swap. This has been a cornerstone of how many investors have managed their digital asset holdings, offering flexibility in navigating market volatility.
The approved amendment, I-3898, fundamentally alters this landscape. It aims to eliminate the tax deferral specifically when an investor exchanges their existing digital assets for e-money tokens that fall under the purview of the EU’s Markets in Crypto-Assets (MiCA) regulation, or for related rights. The MiCA framework defines e-money tokens as crypto assets designed to maintain a stable value pegged to an official currency. This means that if a holder decides to convert, for instance, an appreciated Bitcoin or Ethereum into a stablecoin like a euro-backed token, any capital gain realized from the initial asset’s acquisition cost would become taxable at the moment of the swap.
This change effectively treats such a conversion as a taxable disposal of the original asset, even if the proceeds remain within the digital asset ecosystem and are not immediately converted into fiat currency. The taxable gain would be calculated as the difference between the market value of the acquired e-money token (or related rights) and the acquisition cost of the asset(s) relinquished. Documentation of acquisition costs and any associated transaction fees will be crucial for accurate tax calculations. The proposal also introduces a shift in how acquisition costs are managed. Instead of a portfolio-wide cost allocation, the new rules would necessitate a specific basis for disposed assets, employing a weighted-average acquisition cost for identical assets acquired at different times and prices. For assets held prior to January 1, 2027, investors will have the option to either use documented actual acquisition costs or to irrevocably allocate their existing portfolio’s acquisition cost across all holdings based on their values as of December 31, 2026.
Rejection of Loss Carryforward: A Missed Opportunity for Relief
In parallel to the decision on stablecoin swaps, the French National Assembly’s rejection of amendment I-3653 has significant implications for investors who have experienced losses in their digital asset portfolios. This amendment proposed to allow qualifying net cryptocurrency losses to be carried forward for a period of ten years. Such a provision would have offered a valuable mechanism for investors to offset future gains against past losses, providing a degree of relief and potentially encouraging continued investment in the sector.

However, the failure of this amendment means that the current tax framework remains in place. Under existing French tax authority guidance, cryptocurrency losses can only be offset against cryptocurrency gains within the same tax year. Any net loss that remains after intra-year offsetting cannot be carried forward to subsequent tax years, nor can it be used to reduce taxable gains from other asset classes, such as traditional stocks or bonds.
The practical implication of this dual outcome is that investors who realize gains on stablecoin swaps, which will now be taxed as of the swap date, will not be able to utilize net losses incurred in prior tax years to reduce their tax liability. This creates a scenario where new taxable events are being introduced without a corresponding expansion of loss utilization mechanisms, potentially increasing the tax burden on active traders and investors who frequently rebalance their portfolios.
Background and Broader Context
The legislative actions in France are unfolding within a broader European and global context of increasing regulatory scrutiny and harmonization of digital asset rules. The EU’s MiCA regulation, which came into effect in June 2023, aims to create a comprehensive framework for crypto-asset service providers and issuers, fostering innovation while ensuring investor protection and financial stability. France, as a major European economy, plays a crucial role in the implementation and interpretation of these EU-wide regulations.
The proposal to tax stablecoin swaps can be seen as an effort by French authorities to align the taxation of digital assets more closely with that of traditional financial instruments. In traditional finance, currency exchange gains are often subject to taxation. By treating swaps into stablecoins as taxable events, France is signaling its intention to capture revenue from what it perceives as a form of currency exchange within the digital asset realm.
The debate surrounding crypto taxation has been ongoing globally, with different jurisdictions adopting varying approaches. Some countries have sought to attract crypto businesses and investors with favorable tax regimes, while others have moved towards stricter taxation to ensure fairness and prevent tax evasion. France’s move appears to be leaning towards a more cautious and revenue-focused approach.
Analysis of Implications
The decision to tax stablecoin swaps could have several implications for the French crypto market. Firstly, it may discourage frequent rebalancing of portfolios into stablecoins, potentially leading investors to hold onto their crypto assets for longer periods or to seek alternative, less tax-efficient strategies. This could, in turn, affect the liquidity and trading volumes of stablecoins within France.
Secondly, the absence of a loss carryforward mechanism could deter new investors or those who have previously experienced significant losses. The inability to offset future gains with past losses can make the asset class appear riskier from a tax perspective, potentially slowing down adoption.
The narrow vote margin on the stablecoin tax amendment suggests that the debate is far from settled. It is possible that further discussions and amendments could occur as the finance bill progresses through the legislative process. Industry stakeholders are likely to continue advocating for more favorable tax treatment, particularly regarding loss utilization, to foster a more robust and attractive digital asset ecosystem.
The effective date of January 1, 2027, provides a window for investors to adjust their strategies and for businesses to prepare for the new tax regime. It also allows time for potential revisions to the legislation based on feedback from the market and further parliamentary deliberation.
Official Statements and Industry Reactions (Inferred)
While specific official statements from French financial or tax authorities regarding these votes were not immediately available in the provided content, it is reasonable to infer that the government’s objective is to enhance tax revenue collection and ensure equitable taxation across different asset classes. The close vote suggests that there are differing opinions within the political sphere regarding the optimal approach to regulating and taxing digital assets.
From the perspective of the cryptocurrency industry, these decisions are likely to be viewed with concern. Industry associations and market participants have consistently argued for clear and predictable regulatory frameworks that do not stifle innovation or unfairly penalize investors. The taxation of stablecoin swaps without a corresponding loss carryforward provision could be perceived as an unsupportive measure, potentially leading some businesses and investors to reconsider their presence in the French market.
However, it is also important to acknowledge that the MiCA regulation itself is intended to bring clarity and structure to the crypto market. France’s legislative actions are, in part, an implementation of the broader EU strategy to integrate digital assets into the existing financial and tax systems.
Looking Ahead: The Path to Enactment
The journey of the 2027 finance bill is ongoing. After its first reading in the National Assembly, it will proceed to the Senate for its own deliberations and potential amendments. This process of parliamentary review and negotiation can lead to significant changes in the proposed legislation. Ultimately, both chambers of Parliament must agree on a common text before the bill can be enacted into law.
The provision for taxing stablecoin swaps and the rejection of the loss carryforward are key elements that will be closely watched by the crypto community. The final form of the legislation will have a material impact on how individuals and businesses engage with digital assets in France and could serve as a precedent for other EU member states as they continue to develop their national tax policies for cryptocurrencies. The coming months will be critical in determining the definitive tax landscape for digital assets in France.