
 admin
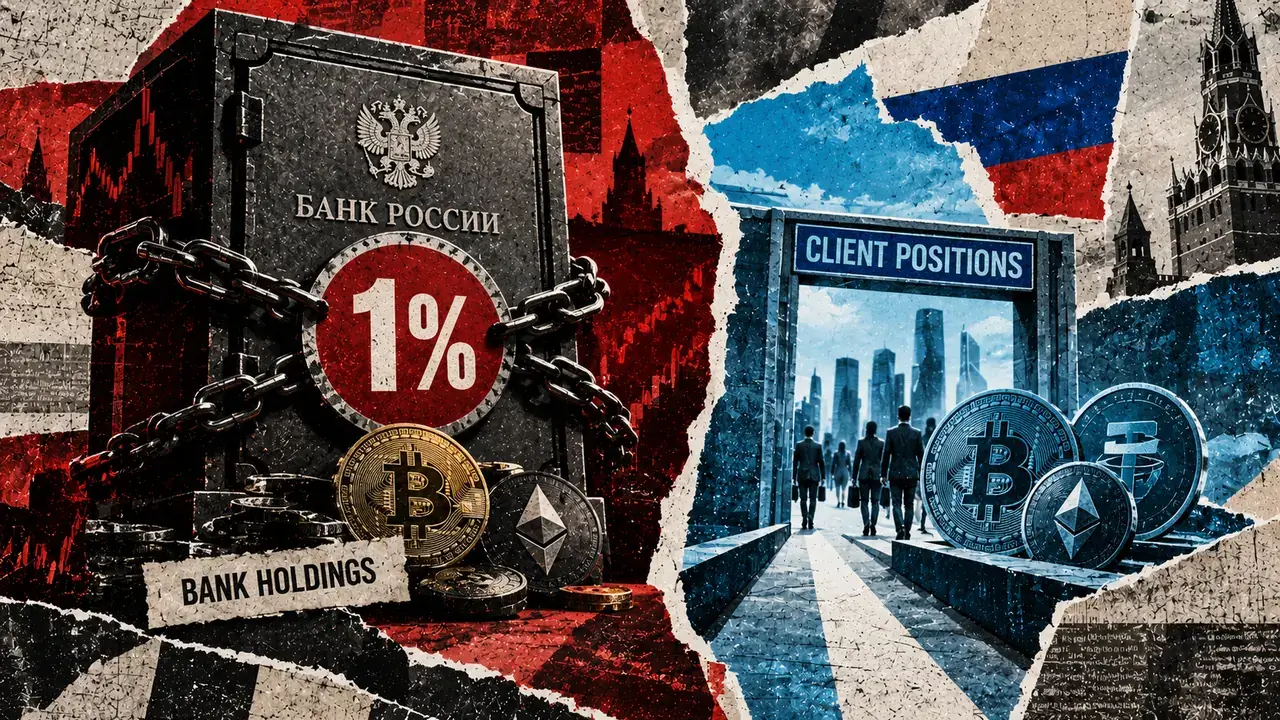
The Bank of Russia has unveiled a significant regulatory proposal that aims to cap the cryptocurrency and foreign digital instrument risk exposure for Russian financial institutions at a mere 1% of their capital. This directive, outlined in a draft regulation released on September 18, 2026, introduces two distinct capital ratios, N31 and N32, designed to segregate the risks associated with a bank’s proprietary crypto holdings and derivatives from those held in custody for clients. Crucially, the proposal carves out certain client custody positions from the stringent 1% limit, provided the bank does not bear the ultimate liability for asset seizure or transaction restrictions.
This nuanced approach signifies a critical development in Russia’s evolving regulatory landscape for digital assets. While the overarching goal appears to be mitigating systemic risk stemming from the volatile cryptocurrency market, the framework demonstrates a strategic effort to differentiate between direct institutional exposure and the safeguarding of customer assets. The draft regulation, currently under review, is expected to be officially published in the fourth quarter of 2026, with its provisions coming into effect just ten days later. Consequently, Russian banks are anticipated to commence reporting instrument turnover and their N31/N32 values in January 2027, though the precise reporting forms are still under development.
Understanding the Dual Capital Ratios: N31 and N32
The proposed framework establishes a two-tiered system to measure and control crypto-related financial risks within Russian banks.
- N31: Individual Credit Institution Ratio: This ratio specifically assesses the crypto and foreign digital instrument risk exposure relative to the capital of an individual credit institution. It focuses on the direct holdings and financial instruments of the single bank.
- N32: Banking Group Ratio: This ratio operates on a consolidated basis, evaluating the crypto and foreign digital instrument risk exposure of an entire banking group against its collective capital. This ensures that the risk appetite of the parent entity and its subsidiaries is managed cohesively.
Both N31 and N32 are designed to limit covered exposure to a maximum of 1% of the institution’s or group’s capital, respectively. This means that the total value of a bank’s direct crypto investments, derivatives linked to crypto prices, and other crypto-dependent financial instruments cannot exceed this small fraction of its own funds. The measurement is explicitly tied to capital, not total assets, a common practice in banking regulation to ensure a robust buffer against losses.
Scope of Covered Exposure: Beyond Direct Coin Holdings
The Bank of Russia’s draft regulation casts a wide net, encompassing a broad spectrum of financial instruments and exposures that are linked to cryptocurrencies and foreign digital instruments. The numerator of these ratios will include:
- Direct and Indirect Investments: This covers outright ownership of cryptocurrencies, as well as investments in entities or funds whose primary assets are digital.
- Derivatives Tied to Crypto Prices: Financial contracts, such as futures, options, and swaps, whose value is directly derived from the price movements of cryptocurrencies will be included.
- Crypto-Linked Instruments: A significant addition is the inclusion of traditional financial instruments that have a direct settlement or value dependency on cryptocurrencies or foreign digital instruments. This includes:
- Loans: Loans where the repayment is denominated or significantly influenced by cryptocurrency values.
- Bonds: Debt instruments whose coupon payments or principal repayment are linked to digital asset performance.
- Guarantees: Guarantees provided for obligations related to crypto transactions.
- Repurchase Agreements (Repos): Agreements where cryptocurrencies are used as collateral.
- Credit Lines: Lines of credit extended where the underlying collateral or repayment is tied to digital assets.
Hedging Strategies and Risk Management
The draft regulation also addresses the mechanisms for hedging against crypto-related risks. Banks will be permitted to net certain long and short positions, but this netting is restricted to a qualifying lower-risk category. This category imposes stringent conditions, including requirements related to the specific asset involved, the settlement process, the maturity of the instruments, and the management of freezing and liquidity risks.
Crucially, direct holdings and other exposures deemed higher-risk will be measured more conservatively. These cannot be fully neutralized by an offsetting position, indicating a deliberate effort by the Bank of Russia to ensure that institutions maintain a clear capital buffer against their most significant crypto-related exposures. This approach acknowledges the inherent volatility and potential for rapid price swings in the digital asset market.
The Critical Distinction: Client Custody vs. Bank Liability
Perhaps the most salient aspect of the proposed regulation is its treatment of customer assets held in custody. The draft clarifies that a custody position enters the N31 or N32 calculation only if the bank, or a digital depository within its group, is liable for potential losses arising from asset seizure or transaction restrictions.
This distinction is paramount:
- Bank Liability: If a bank assumes responsibility for such losses, the client’s digital assets, held in the bank’s custody, will be counted towards the 1% capital limit. This signifies that the bank is effectively taking on a portion of the risk associated with those assets.
- Client Exclusion: Conversely, if the bank explicitly disclaims responsibility for losses due to seizure or restriction, and the client bears that risk, the custody position is excluded from the N31 and N32 calculations. This means that the bank’s capital will not be directly impacted by these client-held assets under the 1% cap.
Prudential Treatment for Non-Liable Client Custody
While excluded from the stringent 1% capital cap, non-liable client custody positions are not entirely outside the prudential oversight of the Bank of Russia. For broader capital-adequacy calculations, these positions will be assigned a 50% risk weight. This is a significantly lower risk weight compared to own-account exposures and client positions for which the bank is liable, which will receive a hefty 1,250% risk weight. This differentiated risk weighting underscores the regulator’s intention to acknowledge the presence of digital assets within the financial system while applying a more cautious approach to the assets directly held and managed by the banks themselves.
Broader Context: Russia’s Developing Crypto Regulatory Framework
This 1% capital cap proposal is not an isolated development but rather an integral part of Russia’s comprehensive strategy to regulate the cryptocurrency market. The Bank of Russia has been actively working on establishing a clear legal and operational framework for digital assets. This initiative follows earlier pronouncements and legislative efforts aimed at defining cryptocurrencies, establishing rules for their circulation, and determining the roles of various financial institutions.

The journey has been complex, with initial debates ranging from outright bans to more permissive approaches. The current direction suggests a measured integration, prioritizing financial stability and consumer protection. CryptoSlate has previously highlighted the ongoing nature of this regulatory build-out, noting that certain aspects of the market framework were still being finalized. The introduction of these capital requirements marks a significant step towards operationalizing that framework.
Timeline and Implementation
The proposed regulation is slated for official publication in the fourth quarter of 2026. The new rules will take effect ten days after their official release. This provides financial institutions with a defined period to adapt their systems and strategies. The practical application will begin in January 2027, when banks are expected to start reporting their cryptocurrency-related activities, including instrument turnover and the calculated N31/N32 values. The development of the detailed reporting forms is ongoing, indicating the Bank of Russia’s commitment to refining the reporting and oversight mechanisms.
Implications and Analysis
The Bank of Russia’s 1% crypto capital cap proposal carries several significant implications for the Russian financial sector and the broader digital asset landscape:
- Risk Mitigation for Banks: The primary objective is to shield banks from the extreme volatility inherent in the cryptocurrency market. By limiting direct exposure to a small fraction of their capital, the central bank aims to prevent a crypto downturn from jeopardizing the solvency of individual institutions or the stability of the entire banking system.
- Encouraging Responsible Custody: The distinction between bank liability and client exclusion for custody services could encourage banks to offer crypto custody services more readily, provided they can structure these services to minimize their own financial exposure. This could lead to a more developed and regulated market for institutional and retail custody of digital assets.
- Chilling Effect on Proprietary Trading: The strict 1% cap will likely dampen enthusiasm for large-scale proprietary trading of cryptocurrencies by Russian banks. The capital requirements are substantial enough to make significant direct investments in crypto financially burdensome and potentially unattractive.
- Focus on Risk-Weighted Assets: The application of a 50% risk weight to non-liable client custody positions, while still a prudential measure, acknowledges that these assets, when properly ring-fenced, do not pose the same level of risk to the bank as directly held assets.
- Alignment with Global Trends: While the specifics are unique to Russia, the underlying principle of applying capital requirements to crypto exposures aligns with efforts by global regulators to bring digital assets under a more structured financial regulatory umbrella. However, the 1% figure is notably stringent compared to proposals in many other jurisdictions.
The Bank of Russia’s methodical approach, as evidenced by this detailed proposal, suggests a commitment to fostering a controlled environment for digital assets within its financial system. The success of this framework will hinge on its effective implementation, the clarity of future guidance, and the ability of financial institutions to navigate the new regulatory landscape while continuing to innovate within the evolving digital economy. The coming years will reveal how this carefully calibrated approach shapes Russia’s engagement with cryptocurrencies and digital finance.