
 admin
Foreign buyers returned to U.S. Treasury bills in July 2026, signaling a partial restoration of confidence in the shortest-dated segment of the U.S. government debt market. However, this rebound did not extend to longer-term securities, revealing a significant divergence in investor sentiment and raising questions about the sustainability of this trend. The data, released by the Treasury Department, indicate a complex interplay between official and private foreign investment, with implications that ripple beyond the bond market, potentially influencing riskier assets like Bitcoin. The continued elevation of long-term yields, particularly for the benchmark 10-year Treasury note, suggests that investors remain cautious about the future trajectory of interest rates and the broader economic outlook.
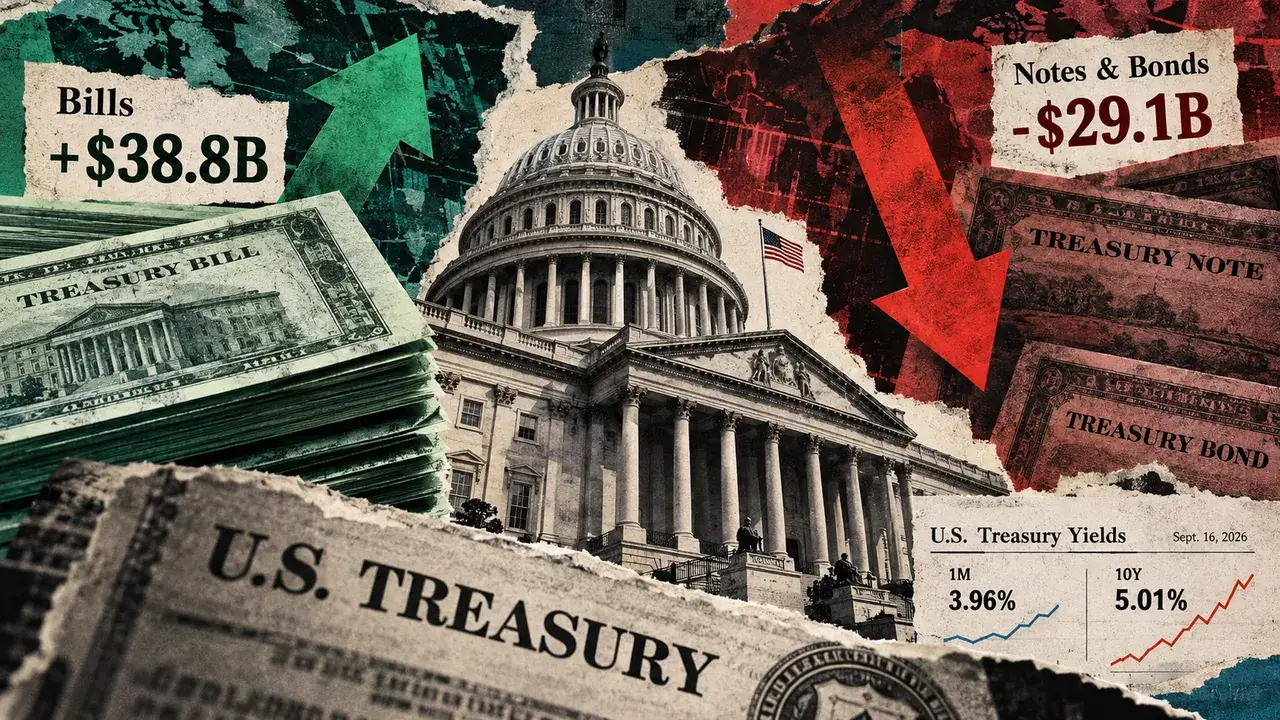
The Treasury International Capital (TIC) data for July 2026 paints a nuanced picture of foreign capital flows into U.S. debt. While total foreign purchases of Treasury bills surged by a net $38.8 billion, reversing a $29 billion outflow in June, a deeper dive into the composition of these flows reveals a bifurcated market. Private foreign investors were the primary drivers of this bill resurgence, injecting $45 billion into short-term debt instruments. This suggests a preference for liquidity and capital preservation in the face of ongoing economic uncertainties. These investors, however, simultaneously divested $29.1 billion from longer-dated Treasury notes and bonds, signaling a clear aversion to the duration risk associated with these securities.
In contrast, foreign official institutions, typically central banks and sovereign wealth funds, adopted a different strategy. They reduced their holdings of Treasury bills by $6.3 billion while significantly increasing their exposure to longer-term notes and bonds by $25.5 billion. This counterbalancing act by official entities managed to offset a substantial portion of the private sector’s selling pressure on longer-dated debt. Despite these opposing forces, the net flow for the combined category of Treasury notes and bonds remained slightly negative, underscoring the persistent demand for shorter-term, less volatile assets among private investors.
When all adjustments, including U.S. purchases of foreign securities, are accounted for, the net foreign acquisition of all long-term U.S. securities registered a deficit of $27.9 billion for July. This figure, which encompasses a broader range of fixed-income investments beyond just Treasuries, reinforces the notion that foreign capital was not broadly embracing long-term U.S. debt. The headline TIC inflow figure of $83.7 billion, while appearing robust, was thus largely a product of short-term bill demand, masking the underlying caution regarding longer-duration assets.
The Distinction Between Bills, Notes, and Bonds
To fully grasp the implications of these flows, it is essential to understand the different maturities of Treasury securities. Treasury bills mature in one year or less and are considered highly liquid and low-risk. Treasury notes have maturities ranging from two to 10 years, offering a balance between yield and duration. Treasury bonds, the longest-dated securities, mature in 20 to 30 years and carry the highest duration risk due to their sensitivity to interest rate changes.
The July TIC data indicates that private foreign investors were primarily seeking the safety and liquidity of bills, effectively shunning the longer-term commitments offered by notes and bonds. This behavior is not necessarily indicative of a direct rotation from one maturity bucket to another within the same investor base. Instead, it reflects a broader sentiment of risk aversion, where investors prioritize capital preservation over potential long-term gains in a market characterized by interest rate uncertainty.
Yield Curve Dynamics Reflecting Investor Caution
The yield curve data for July and September 2026 further corroborates this interpretation. Throughout July, the 10-year Treasury yield, a key benchmark for global borrowing costs, climbed from 4.48% to 4.75%. Simultaneously, the 30-year Treasury yield experienced a more pronounced increase, rising from 4.97% to 5.27%. This widening spread between short-term and long-term yields suggests that investors were demanding higher compensation for holding debt with longer maturities, anticipating potential future interest rate hikes or persistent inflation. In stark contrast, the three-month Treasury bill rate saw a marginal decline, moving from 3.85% to 3.83%, highlighting the demand for short-term instruments.
By mid-September 2026, this trend had solidified. The Treasury yield curve displayed a 3.96% yield for one-month securities, while the 10-year yield had settled around 5.01%. This resulted in a significant 1.05 percentage-point gap between short-term and long-term rates. This steepness in the yield curve is a classic indicator of market expectations for higher interest rates in the future or a premium demanded for holding longer-dated debt in an uncertain economic environment. While these flow and yield curve observations are distinct data points, they collectively paint a consistent picture of foreign investors prioritizing short-term safety over long-term commitments in the U.S. Treasury market.
It is important to note that the Treasury Department itself cautions that its monthly long-term holdings data are primarily custody-based. This methodology can sometimes obscure the ultimate beneficial owner of an asset, as a foreign custodian might hold securities on behalf of investors from various countries. Furthermore, the July flow table is not seasonally adjusted, and the TIC system excludes direct investment, meaning that the data capture portfolio investments rather than direct ownership stakes in U.S. businesses. These caveats do not invalidate the general trends observed, but they do highlight the need for careful interpretation of the granular details.
Bitcoin’s Sensitivity to Treasury Market Dynamics
The implications of these foreign demand patterns in the Treasury market extend to other asset classes, particularly cryptocurrencies like Bitcoin. The Federal Reserve has long identified foreign demand for U.S. Treasuries as a factor influencing Treasury term premiums, which in turn can impact broader financial conditions. The relationship is endogenous, meaning that capital flows and yield movements are interconnected and can influence each other.
From a broader financial conditions perspective, as outlined by the Federal Reserve’s framework, Treasury yields are a critical component alongside private borrowing rates, equity valuations, and the U.S. dollar’s exchange rate. When risk-free returns on safe assets like U.S. Treasuries rise, the opportunity cost of holding non-yielding or higher-risk assets increases. For Bitcoin, which does not generate income, elevated Treasury yields can make it less attractive compared to the guaranteed returns offered by government debt.
Moreover, elevated long-term Treasury yields can also signal tighter credit conditions. As borrowing costs rise across the economy, businesses and individuals may have less capital available for investment in riskier assets. This tightening of liquidity can reduce the overall demand for assets like Bitcoin, potentially hindering its price appreciation. The July TIC data, therefore, suggests that while foreign investors found solace in short-term U.S. debt, the underlying caution about longer-term economic prospects and interest rate trajectories could be a drag on riskier assets.
Broader Economic Context and Potential Scenarios
The current environment is shaped by a complex interplay of factors. Central banks globally, including the Federal Reserve, have been navigating the delicate balance between controlling inflation and avoiding a significant economic downturn. Elevated inflation figures have prompted aggressive monetary tightening in many economies, leading to higher interest rates across the board. This has made longer-dated bonds less attractive due to the risk of capital depreciation if rates continue to rise.
For private foreign investors, the decision to sell $29.1 billion in notes and bonds in July can be interpreted as a strategic move to de-risk portfolios. In an environment where inflation remains a concern and the future path of monetary policy is uncertain, holding shorter-term, more liquid assets provides greater flexibility and reduces exposure to interest rate risk. The fact that these investors are willing to accept lower yields on bills, rather than take on the duration risk of longer-term debt, underscores this cautious sentiment.
The actions of foreign official institutions offer a different perspective. Their increased purchases of notes and bonds could indicate a longer-term investment horizon and a belief that current yields offer attractive entry points for long-term holdings. Alternatively, these institutions may be acting to stabilize markets or fulfill strategic asset allocation mandates, potentially seeing value in U.S. debt as a safe haven despite short-term yield pressures. The interplay between these two distinct investor groups highlights the divided sentiment within the global financial community regarding the future of U.S. debt and the broader economic landscape.
Implications for Future Market Performance
The observed trend in July’s Treasury flows suggests that any significant rally in risk assets, including Bitcoin, would likely require a broader shift in foreign investor sentiment. A sustained decline in long-term Treasury yields, coupled with a clear signal of economic stabilization and potential easing of monetary policy, would be more conducive to risk-on behavior. The continued preference for short-term bills by private foreign investors, while understandable in the current climate, does not provide the robust foundation needed for a sustained risk asset rally.
The market will be closely watching for signs that private foreign accounts are not only maintaining their interest in Treasury bills but are also actively re-engaging with longer-dated Treasury notes and bonds. Such a development, alongside a consistent downward trend in long-term yields, would signal a more optimistic outlook on the economy and a greater willingness to bear duration risk. Until then, the current dynamics in the Treasury market suggest a continued environment of caution, where capital preservation takes precedence over long-term growth strategies, potentially limiting the upside for assets like Bitcoin. The elevated long-term yields serve as a persistent reminder of the underlying economic uncertainties and the cost of capital in the current global financial system. The coming months will be crucial in determining whether this cautious approach by private investors persists or if a more optimistic view of the U.S. economic future will begin to take hold.