admin
US wholesale inflation demonstrated a slowdown in October, a development that, on the surface, might suggest a more favorable financing environment for Bitcoin (BTC) holders. However, a closer examination of the Bureau of Labor Statistics’ (BLS) Producer Price Index (PPI) report for October reveals a more complex picture. Rising freight costs, despite a significant drop in diesel prices, and persistent underlying inflationary pressures indicate that the path to easier financing for Bitcoin, particularly while it remains below the $70,000 mark, is far from straightforward. The interplay of these economic indicators and their potential impact on cryptocurrency markets warrants a detailed analysis.
October PPI Report: A Tale of Two Trends
The BLS released its comprehensive producer-price report on November 13th, offering a nuanced view of wholesale price movements. The headline Producer Price Index (PPI) for final demand saw a notable deceleration, increasing by a seasonally adjusted 0.3% in October. This represents a significant cooling from the revised 1.4% surge recorded in September. This headline figure, often the most closely watched by markets, suggested a broad easing of inflationary pressures at the producer level.
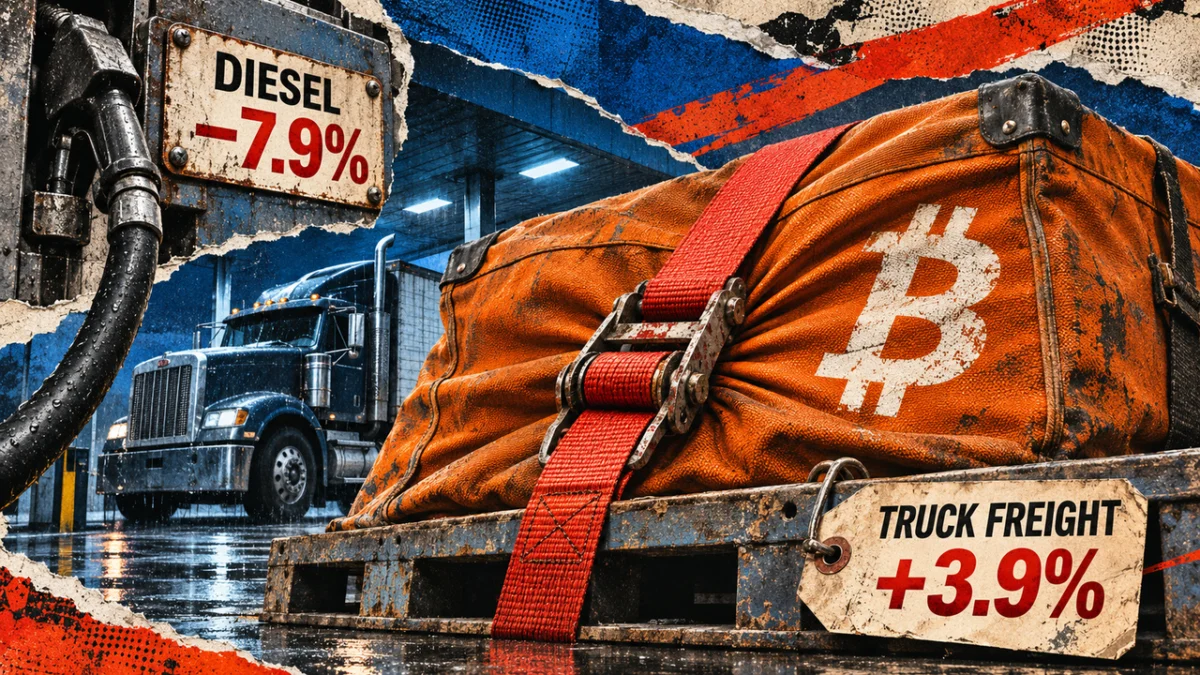
However, the narrative shifts when delving into the details. A critical component of the report highlighted the divergent paths of energy and transportation costs. While diesel prices experienced a substantial decline of 7.9% in October, a move that typically signals a reduction in transportation expenses, truck freight prices concurrently surged by 3.9%. This juxtaposition directly challenges the assumption that falling fuel costs automatically translate into cheaper logistics. The BLS report explicitly attributed over 80% of the 0.2% rise in final-demand services prices in October to the increase in truck freight. Consequently, transportation and warehousing services as a whole rose by 2%, even as final-demand energy prices saw a marginal dip of 0.1%.
Furthermore, the core measure of inflation, which excludes the volatile categories of food, energy, and trade services, continued to exhibit resilience. This "core" PPI measure rose by 0.5% in October, mirroring the pace of increase seen in September. While the annual rate of increase for this exclusion measure eased slightly to 4.9% from 5% in the previous month, the consistent monthly upward trend underscores persistent underlying price pressures within the economy. In contrast, the annual headline PPI accelerated to 6.5% from 6.3% in September, painting a picture of mixed signals where some comparisons improved, but underlying monthly inflationary pressures remained firm.
The report also indicated that unprocessed intermediate goods prices fell by 3.1%. This decline, coupled with the slower headline monthly inflation and the easing annual exclusion measure, provides some tangible evidence for a more optimistic interpretation of the inflationary outlook. The crucial question, however, remains whether this cooling trend will broaden across the economy and prove to be sustainable.
The Inflationary Landscape: PPI, CPI, and PCE
It is crucial to understand the distinctions between various inflation measures and their implications. The PPI, as reported, tracks the selling prices received by domestic producers for their output. This differs from the Consumer Price Index (CPI), which measures the prices paid by consumers for a basket of goods and services. The Federal Reserve, in its monetary policy decisions, primarily targets inflation as measured by the Personal Consumption Expenditures (PCE) price index. While these measures overlap in describing the economic pressures at play, their readings are not interchangeable and can present different perspectives on inflation.
The Federal Reserve’s stance on inflation and potential interest rate policy is a significant factor influencing financial markets, including cryptocurrency. In the lead-up to the CPI release, Federal Reserve Governor Christopher Waller indicated a leaning towards further monetary tightening, suggesting a potential 25-basis-point interest rate increase in December if economic conditions evolved as anticipated. He further stated that a more aggressive 50-basis-point hike would be considered if the October core CPI data showed a continued upward trend, similar to the preceding two readings of around 0.3% or higher.
The subsequent CPI report, released shortly after the PPI data, revealed a 0.4% monthly increase in headline inflation and a third consecutive 0.3% rise in the core CPI (excluding food and energy). This sustained core inflation aligns with the persistent pressures observed in the PPI data and reinforces the complexity of the current economic environment.
The Bitcoin Financing Hurdle: Beyond Wholesale Prices
The path from wholesale price fluctuations to easier financing for Bitcoin holders is multifaceted and contingent on several factors. The Federal Reserve’s monetary policy, driven by its assessment of inflation, plays a pivotal role. The mechanism for this influence is that lower interest rates or a pause in rate hikes can reduce borrowing costs. For Bitcoin, this could translate into lower financing costs for those using leverage or seeking to borrow against their holdings. Moreover, an environment of easier financial conditions can encourage investors to allocate more capital towards riskier assets, such as cryptocurrencies.
However, the current economic data suggests that this route to financing relief remains conditional. Persistent inflation, as evidenced by the sticky core PPI and CPI figures, could compel the Fed to maintain a restrictive monetary policy even as certain commodity prices, like diesel, decline. This means that the anticipated easing of financing conditions might be delayed or less pronounced than some investors hope.
For Bitcoin holders, the expectation of cheaper financing relies on a broader economic narrative of cooling inflation and a less hawkish Federal Reserve. The recent PPI report, with its conflicting signals of falling diesel prices juxtaposed with rising freight costs and resilient core inflation, complicates this narrative. The sustained increase in truck freight prices, in particular, suggests that the cost savings from lower fuel prices are not being fully passed on to businesses, potentially leading to higher operating costs that could eventually filter through to consumer prices.
ETF Flows and Investor Sentiment: A Crucial Indicator
Beyond macroeconomic data, the flow of capital into and out of Bitcoin investment vehicles provides a direct indicator of investor demand and sentiment. Farside Investors’ data revealed that on November 12th, the day preceding the PPI release, US Bitcoin Exchange-Traded Funds (ETFs) experienced net outflows totaling $284.1 million. This outflow signifies that more investors were selling their ETF shares than buying them, indicating a degree of caution or divestment within the market.
While completed ETF inflows would offer more concrete evidence of returning buyers and strengthening demand, the recent outflows suggest that current investor sentiment is not yet overwhelmingly bullish. An optimistic case for Bitcoin, which often hinges on the prospect of easier financing and increased risk appetite fueled by easing inflation, requires more than just the expectation of cheaper fuel. It necessitates observable inflows into key investment channels like Bitcoin ETFs, demonstrating a tangible shift in investor behavior.
Broader Implications for Bitcoin and the Market
The interplay of inflation data, central bank policy, and investor flows creates a complex environment for Bitcoin. For the narrative of "fuel declines becoming useful for Bitcoin holders" to gain traction, several conditions need to be met:
- Broad Cooling of Prices: A sustained deceleration in both consumer and producer prices across a wider range of goods and services is necessary to convince the Federal Reserve that inflation is firmly under control.
- Less Restrictive Policymaker Assessments: Dovish signals from Fed officials and a clear indication that interest rate hikes are definitively over, or that rate cuts are on the horizon, would significantly ease financial conditions.
- Observable Financing Relief: Tangible evidence of lower borrowing costs in the broader financial system, which could then translate into more affordable financing options for Bitcoin investors, is crucial.
- Sustained ETF Inflows: A consistent and significant inflow of capital into US Bitcoin ETFs would provide a strong signal of renewed investor interest and demand, counterbalancing any lingering inflationary concerns.
Conversely, continued underlying inflation pressure, as suggested by the persistent core PPI and CPI figures, coupled with further withdrawals from Bitcoin ETFs, would weaken the case for a bullish turnaround, even if diesel prices continue to decline. The market’s focus will remain keenly on the Federal Reserve’s next moves, the evolution of inflation data across all key metrics, and the ability of Bitcoin to attract and retain investor capital through its primary investment vehicles. The current economic landscape presents a challenging environment where optimism must be tempered with a rigorous examination of the data, recognizing that a simple drop in fuel prices does not automatically unlock an era of easy financing for digital assets. The road ahead for Bitcoin, in terms of financing and broader market sentiment, is contingent on a more comprehensive and sustained improvement in the macroeconomic outlook.