admin
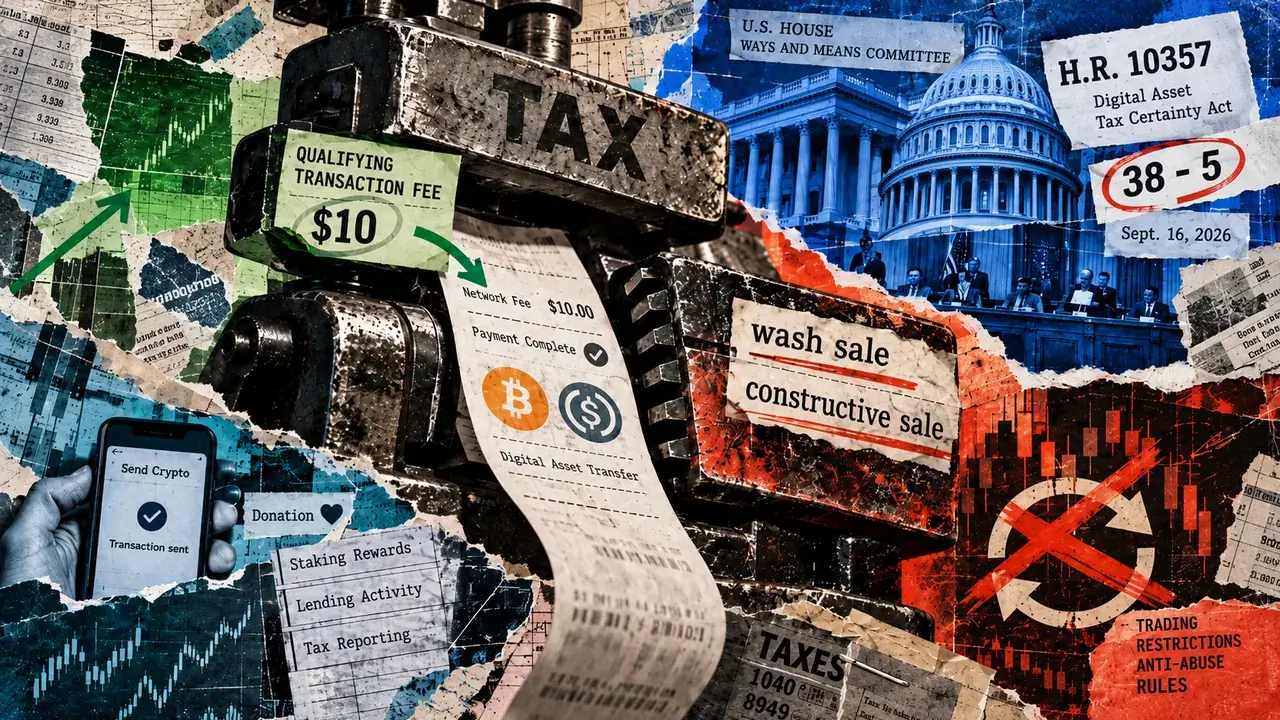
The cryptocurrency industry is actively urging Congress to expand tax relief measures following a significant development in the House of Representatives, where a key committee has advanced the first comprehensive digital-asset tax framework. The House Ways and Means Committee’s approval of H.R. 10357, the Digital Asset Tax Certainty Act, on September 16th marks a pivotal moment, signaling a growing recognition of digital assets within the U.S. tax code. While the legislation, which passed by a substantial margin of 38-5, covers a broad spectrum of crypto-related activities including payments, stablecoins, trading, lending, staking, and mining, industry stakeholders believe it falls short of addressing several critical priorities.
The committee’s endorsement of the amended bill, following the adoption of Chairman Jason Smith’s substitute, sends the legislation to the full House for further consideration. This move was met with cautious optimism by crypto advocacy groups, who lauded the progress while simultaneously highlighting areas where they believe further refinement is necessary to foster wider adoption and innovation. Their primary concerns revolve around achieving broader tax relief for everyday cryptocurrency transactions and adjusting the timing of when income from staking and mining rewards becomes taxable.
Alison Mangiero, Chief Strategy Officer and Head of US Policy at the Crypto Council for Innovation (CCI), acknowledged the committee’s vote as a "historic step." However, she emphasized that lawmakers still have an opportunity to enhance the legislation, particularly concerning the recognition of income from staking and mining rewards and the expansion of de minimis (small-value) exemptions for routine digital asset transactions. CCI had previously communicated these concerns to lawmakers in the lead-up to the markup, underscoring the industry’s desire for a more accommodating tax environment.
The current legislative package represents a significant stride in granting long-sought tax concessions to the digital asset sector. Nevertheless, it falls short of entirely removing certain frictions that crypto proponents argue impede the use of digital assets for payments and active participation in network ecosystems. The industry’s ongoing efforts are now focused on building upon this foundational bill to secure more comprehensive reforms before its final passage.
Expanding Relief for Everyday Crypto Transactions
A key provision within H.R. 10357 aims to alleviate some of the tax burdens associated with using digital assets for transaction fees. The bill proposes to eliminate gain-or-loss recognition when digital assets are used to pay qualifying network and transaction fees up to $10. This provision, slated to take effect for dispositions after December 31, 2027, seeks to address a specific consequence of the Internal Revenue Service’s (IRS) classification of digital assets as property. Under current interpretations, the act of spending cryptocurrency to cover a blockchain fee can itself trigger a taxable event, creating a disincentive for users.
However, the Crypto Council for Innovation and other industry groups are advocating for a more expansive approach. They are pushing for broader de minimis relief that would exempt smaller, everyday digital asset transactions from taxation altogether, rather than limiting the exemption to qualifying fees. The distinction is crucial: H.R. 10357’s $10 provision specifically targets fees, not a general exemption for minor purchases made with crypto. This would allow individuals to use digital assets for a wider range of everyday expenditures without incurring immediate tax liabilities. Such a change, they argue, would significantly enhance the utility and accessibility of cryptocurrencies for consumers.
Special Treatment for Stablecoins and Simplified Accounting
Beyond transaction fees, the legislation introduces special treatment for qualifying U.S. dollar stablecoins, aiming to provide greater clarity and stability in their usage. Furthermore, it establishes a simplified accounting election for widely traded digital assets, which could reduce the compliance burden for businesses and investors holding a diverse portfolio of cryptocurrencies.
The bill also seeks to align the treatment of digital assets with traditional financial instruments by extending existing financial market regulations to various aspects of the crypto industry. This includes introducing lending safe harbors, implementing mark-to-market accounting for eligible dealers and traders, and streamlining rules for certain charitable donations. These measures are intended to create a more predictable and regulated environment, drawing parallels to established practices in traditional finance.
Tightening Rules for Investors
While offering concessions, H.R. 10357 also introduces stricter regulations for investors. The legislation proposes to extend wash-sale and constructive-sale provisions to digital assets. These provisions are designed to prevent taxpayers from claiming artificial tax losses by selling an asset and then repurchasing it shortly thereafter. Historically, cryptocurrencies have operated outside the scope of these rules, which are typically applied to securities and other financial instruments. The inclusion of digital assets under these provisions aims to close potential tax loopholes and ensure a more equitable tax treatment across asset classes.
Addressing Staking and Mining Rewards: A Key Unresolved Issue
One of the most consequential unresolved issues for the industry pertains to the taxation of income generated from mining and staking activities. These processes are fundamental to the operation and security of many blockchain networks, and the rewards generated represent a significant source of income for participants.
The current legislation explicitly classifies income from digital-asset validation activities as ordinary income and establishes sourcing rules based on the taxpayer’s or business operation’s location. It also includes provisions to allow qualifying investment trusts to engage in staking without jeopardizing their trust status solely due to this activity.
However, a critical element that remains absent from the bill is the optional deferral of income recognition that was proposed in earlier discussions. This deferral would have allowed some miners and stakers to postpone recognizing newly created tokens as income until they were sold. The current package clarifies the character of validation income but leaves the timing of its recognition unresolved, a point of significant concern for industry stakeholders like CCI.
The immediate recognition of staking and mining rewards can create tax liabilities for operators even before they have sold the received tokens. This can expose miners and validators to significant price volatility between the time of reward receipt and eventual liquidation. For instance, if a miner receives a reward of newly minted tokens that immediately decrease in value, they could face a tax bill based on the higher initial value, leading to a potential cash-flow crunch and financial risk. The absence of a deferral mechanism means that participants in these crucial network functions may be forced to sell assets prematurely to meet tax obligations, potentially impacting network security and decentralization.
International Entities and the Path Back to the US
In a notable concession, the industry has secured a provision aimed at providing clarity for crypto organizations established outside the United States. The bill directs the Treasury Department to issue guidance within 12 months regarding the tax treatment of foreign entities associated with decentralized autonomous organizations (DAOs). This includes establishing methods for qualifying foundations to reorganize as domestic corporations and potentially offering temporary safe harbors for entities formed prior to September 14th.
Miles Jennings, Head of Policy and General Counsel at a16z crypto, highlighted the potential of this provision to offer clearer rules for entrepreneurs and create a pathway for crypto foundations to return to the U.S. under a domestic tax structure. This could encourage innovation and job creation within the United States, fostering a more competitive environment for the burgeoning digital asset sector.
CCI’s Mangiero echoed this sentiment, identifying the DAO provision as a significant step that could incentivize innovation and job growth to return to the U.S. However, she reiterated that the broader legislative package still requires technical adjustments to fully realize its potential and address all industry concerns.
Background and Broader Implications
The advancement of H.R. 10357 comes after years of the crypto industry lobbying for clearer tax regulations. The IRS’s initial guidance, issued in 2014 and updated in 2019, has been criticized for being insufficient and creating uncertainty. The lack of a specific legislative framework has led to a patchwork of interpretations and compliance challenges for individuals and businesses operating in the digital asset space.
The proposed legislation aims to address this by providing a dedicated framework, treating digital assets similarly to other financial assets while also acknowledging their unique characteristics. The inclusion of provisions related to stablecoins, lending, and charitable donations suggests an effort to integrate digital assets more seamlessly into the existing financial system.
The debate over the taxation of staking and mining rewards is particularly complex. Unlike traditional employment income or investment gains, these rewards are often received in kind and can fluctuate significantly in value. Finding a balance between recognizing income and avoiding undue financial strain on network participants is a key challenge.
The broader implications of this legislation, should it pass the full House and Senate, are substantial. It could provide much-needed clarity and certainty for the growing digital asset economy in the United States, potentially spurring further investment and innovation. However, the industry’s ongoing advocacy for more expansive de minimis relief and deferral of staking and mining income suggests that the conversation around digital asset taxation is far from over. The effectiveness of these new rules in fostering mainstream adoption and encouraging technological development will depend on continued engagement between policymakers and the industry to refine the framework. The path forward will likely involve further amendments and potentially subsequent legislative actions to address the evolving nature of digital assets and their integration into the global economy.