Dwi Wanna
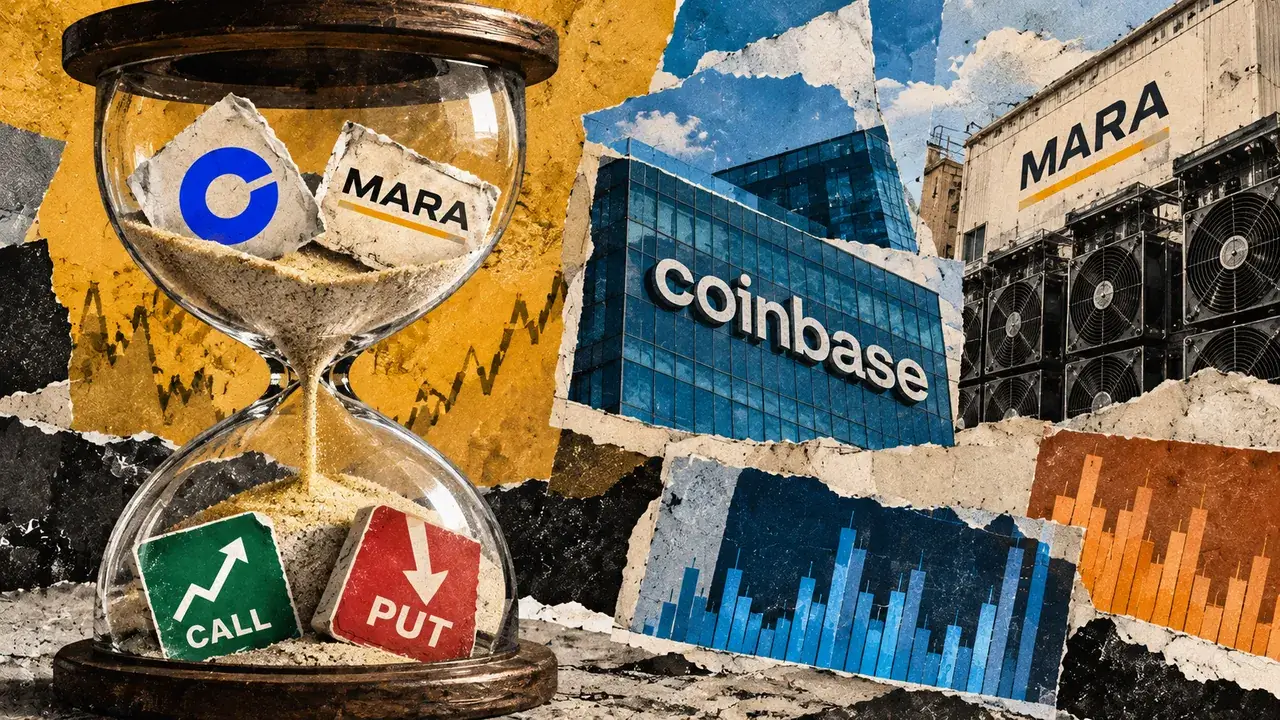
A defining characteristic of this regulatory approval is the "finality" provision regarding settlement figures. According to the approved rules, once a contract has expired and the payout has been distributed based on the company’s initially reported figures in SEC filings, a subsequent correction or restatement by the company will not trigger a reversal of the payout. This ensures that the derivatives market remains liquid and certain, preventing long-term disputes or clawbacks resulting from accounting revisions that occur months or years after a trading period ends.
The Architecture of KPI Contracts
The newly approved binary options function on a simplified payout structure. Each contract carries a standard gross payout of $1.00 if the underlying condition is met, and $0.00 if it is not. This binary nature aligns the product more closely with prediction markets than with traditional complex derivatives.
For Coinbase, the eligible metrics for these contracts include:
- Transaction Revenue: The total fees earned from users trading on the platform.
- Subscription and Services Revenue: Revenue derived from staking, stablecoin interest, and other non-trading services.
- Total Trading Volume: The total dollar value of all assets traded on the exchange during the specified reporting period.
For MARA Holdings, the metrics focus on the core of the Bitcoin mining business:
- Bitcoin Produced: The total number of BTC tokens successfully mined during the quarter.
- Total Bitcoin Holdings: The aggregate amount of Bitcoin held in the company’s treasury at the end of the reporting period.
The Cboe will designate the specific metric and the reporting period (typically a fiscal quarter) when listing the option series. This provides a clear, objective target for traders to speculate on or hedge against.
Chronology of Regulatory Milestones
The path to this approval involved a multi-step coordination between Cboe, retail brokers, and federal regulators. The timeline reflects a rapid push to bring prediction-style markets into a regulated exchange environment.
- September 30, 2026: Cboe and Robinhood jointly announce a planned launch of KPI contracts. The announcement signals a strategic partnership aimed at bringing sophisticated event-based trading to retail investors. Cboe reveals plans to eventually expand this to 23 major companies, pending further approvals.
- October 8, 2026: Cboe issues a secondary update, reiterating the conditional nature of the launch and confirming that the rollout is contingent upon the SEC’s final sign-off on exchange rules and clearing procedures.
- October 13, 2026: The SEC formally signs the order (34-106659) approving the rule changes required for Cboe to list these specific Coinbase and MARA series.
- October 16, 2026: The approval is officially published in the Federal Register, the daily journal of the United States government, providing the legal foundation for the new market.
- October 17, 2026: Market participants await confirmation of the specific "go-live" date for trading and the verification of Robinhood’s platform readiness to host these contracts for retail users.
Settlement Mechanics and the Finality Rule
The settlement process is anchored to official corporate disclosures. Under ordinary circumstances, the Cboe uses the designated metric as reported in the company’s 10-Q (quarterly report) or 10-K (annual report) filed with the SEC.
A "call" option pays out the full $1.00 if the reported figure is equal to or greater than the contract’s pre-defined threshold. Conversely, a "put" option pays out if the reported figure falls below that threshold. The profit for a trader is the difference between the $1.00 payout and the premium paid to buy the contract, minus any brokerage fees.
The most controversial yet practical aspect of the filing is the treatment of restatements. Corporate accounting is often subject to revisions. If a company like Coinbase were to report a trading volume of $150 billion, triggering a payout for a $145 billion threshold contract, and then three months later revise that figure down to $140 billion due to an accounting error, the original payout stands. The SEC’s approval of this provision recognizes that for a derivative market to function, "settlement finality" is more important than "perfect accuracy" regarding historical data that changes after the fact.
Handling Market Disruptions and Missing Data
The SEC filing also outlines contingency plans for scenarios where data is unavailable or delayed. Transparency and predictability are central to the Cboe’s operational rules for these contracts.
If a company delays its earnings release or fails to include the specific metric in its SEC filing, the settlement process can be postponed. While the settlement is delayed, trading on the contract still ceases on the originally scheduled expiration date to prevent insider trading or speculation on leaked data.
In more extreme cases—such as a company permanently omitting a metric or a failure to file—alternative clearing procedures are invoked. The Options Clearing Corporation (OCC) or Cboe Clear U.S. may determine a settlement value based on the option’s last closing price. This is a significant departure from the binary $1 or $0 outcome, as it essentially "cashes out" the contract at its fair market value prior to the reporting failure. If the closing price is deemed unreliable or is unavailable, the option may be declared expired, unexercised, and worthless, resulting in a total loss for the holder.
Strategic Implications for the Crypto Industry
The approval of these contracts is particularly significant for the cryptocurrency sector. Coinbase and MARA are often viewed as proxies for the broader health of the digital asset market. By allowing direct bets on their operational output, the SEC is providing a new tool for "pure-play" exposure.
Institutional investors can use these KPI contracts to hedge specific risks. For example, a Bitcoin mining pool might buy "put" options on MARA’s Bitcoin production to hedge against a network-wide increase in mining difficulty that could lower overall output. Similarly, a crypto hedge fund might use Coinbase volume "calls" to speculate on a surge in retail participation during a bull market without having to take a direct position in the volatile COIN stock.
For retail investors, particularly those on platforms like Robinhood, these contracts represent a regulated alternative to unregulated offshore prediction markets. Following the legal battles surrounding platforms like Polymarket and Kalshi, the SEC’s move to bring event-based contracts under the umbrella of the Cboe suggests a shift toward integrating "prediction market" mechanics into the traditional financial system.
Broader Economic Context and Future Outlook
The SEC’s decision reflects a growing trend toward the "gamification" and "atomization" of financial products. By breaking down corporate performance into tradable units of $1, the barrier to entry for sophisticated financial speculation is lowered.
However, this also raises questions about market integrity and the potential for companies to "manage" their numbers to hit certain thresholds. While the SEC has strict rules against market manipulation and fraudulent reporting, the existence of a high-volume derivatives market tied to specific line items in a balance sheet adds a new layer of pressure on corporate reporting teams.
The initial rollout focusing on Coinbase and MARA is likely a test case. Cboe’s stated goal of expanding this to 23 companies suggests that if these contracts prove popular and stable, investors could soon be trading on the "iPhone units sold" for Apple or "subscriber growth" for Netflix.
The approval signals a maturing of the U.S. derivatives market, where the definition of an "underlying asset" is expanding from physical commodities and stock prices to include the very data points that define corporate success. As the Cboe Clear U.S. completes its final filings, the financial industry will be watching closely to see if these KPI contracts become a staple of modern trading or remain a niche product for the crypto-adjacent elite. For now, the SEC has cleared the way for a new era of "settled" bets, where the finality of the payout is as certain as the volatility of the metrics being traded.