Dwi Wanna
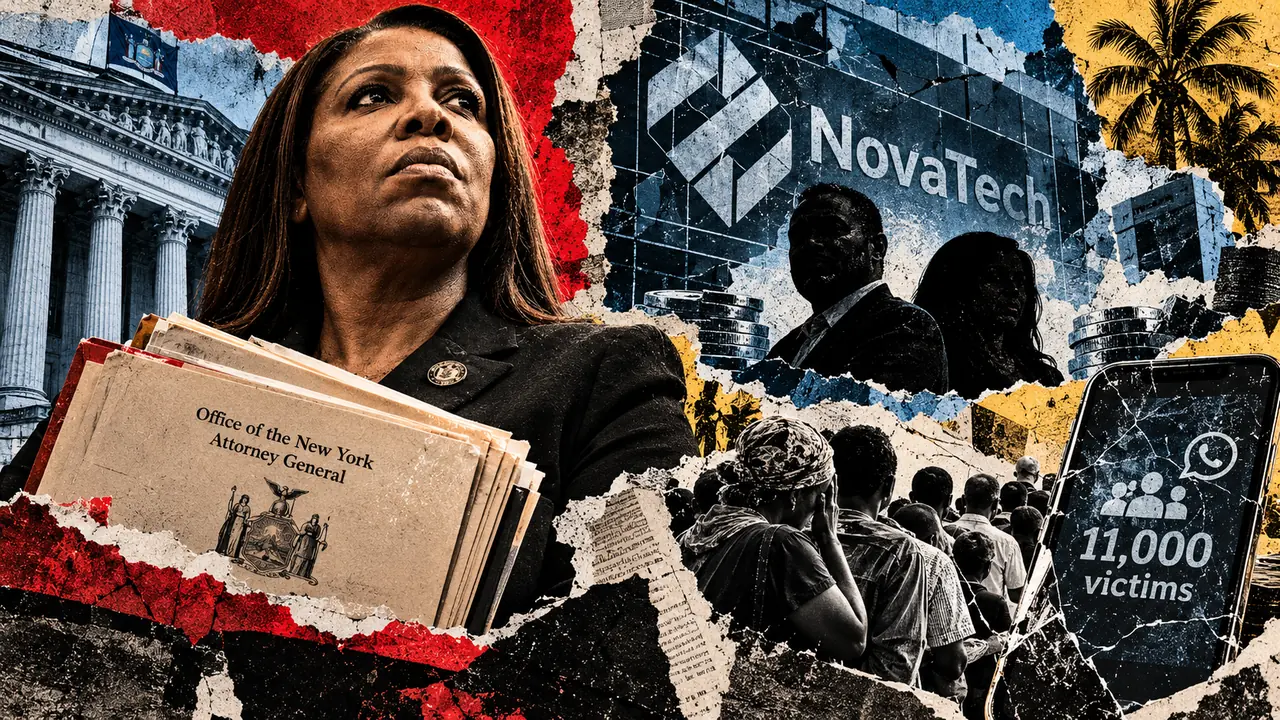
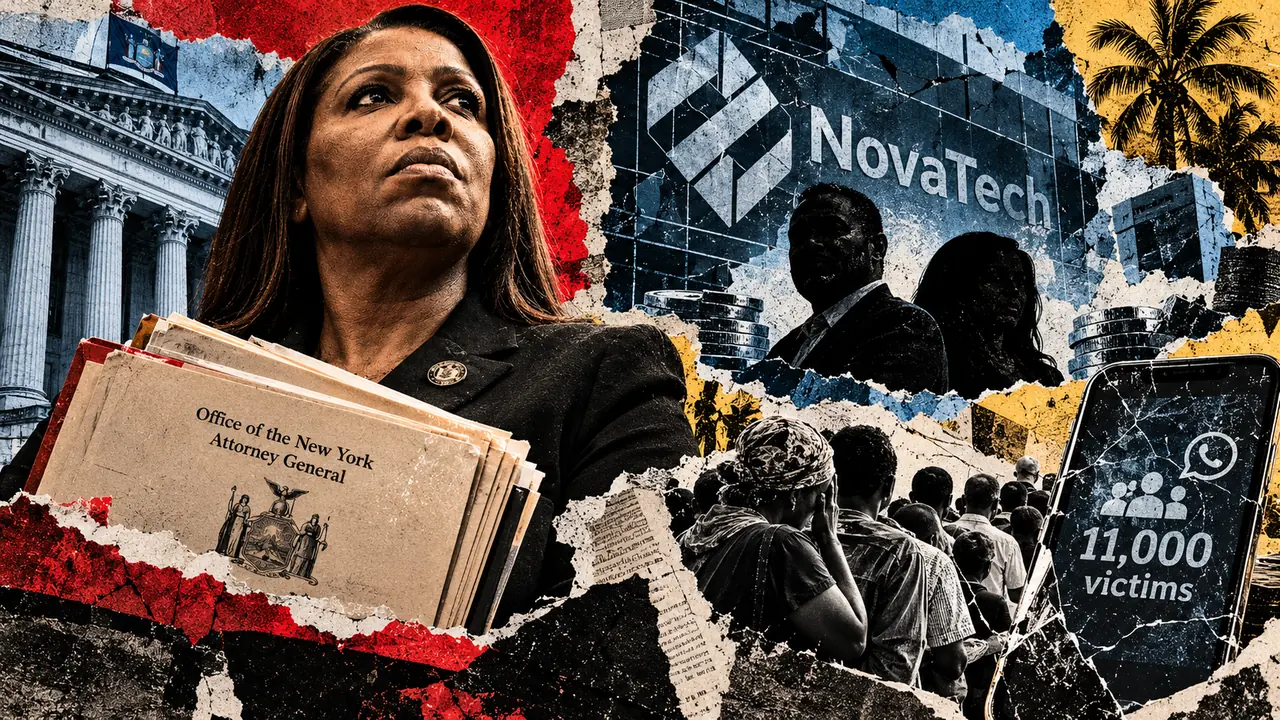
The New York Attorney General’s Office, led by Letitia James, has escalated its legal offensive against the cryptocurrency investment firm NovaTech, its founders, and several high-level promoters. In a motion filed on October 22, 2026, the state requested a court order requiring the company and its principals, Cynthia and Eddy Petion, to pay more than $1.3 billion in restitution and disgorgement. This filing serves as the latest chapter in a multi-year legal battle aimed at dismantling what prosecutors describe as a massive Ponzi scheme that systematically drained life savings from thousands of vulnerable investors, particularly within the Haitian-American and religious communities.
The motion follows a pivotal August 4, 2025, default judgment in which the court found NovaTech and the Petions liable for fraud. Because the defendants failed to adequately contest the charges or provide a comprehensive accounting of their financial activities, the court moved to the damages phase. The current filing seeks a specific total of $1,367,023,585, a figure that includes $1,134,549,691 in principal damages and an additional $232,473,894 in accrued interest. While the filing represents a significant milestone for the state’s recovery efforts, officials cautioned that the request does not guarantee the immediate collection or distribution of funds to the estimated 11,000 New York victims.
The Mechanics of the NovaTech Fraud
NovaTech operated by presenting itself as a sophisticated cryptocurrency and foreign exchange (forex) trading platform. The company lured investors with the promise of high weekly returns—often cited between 2% and 3%—claiming that these profits were generated through expert trading in the digital asset markets. However, the Attorney General’s investigation revealed a starkly different reality. According to the state’s filings, of the approximately $1.161 billion in cryptocurrency deposited by investors, only about $26 million was ever actually transferred to a trading platform.
Instead of generating wealth through market activity, NovaTech functioned as a classic Ponzi scheme. The "profits" paid out to early investors and the commissions paid to recruiters were funded directly by the deposits of newer participants. This cycle allowed the scheme to maintain an appearance of legitimacy for several years, as investors saw their internal account balances grow and some were able to successfully withdraw funds. This illusion of success was critical for the company’s expansion, as it relied heavily on word-of-mouth recruitment and "affinity fraud."
Affinity fraud occurs when a scammer targets members of a specific group, such as a religious organization or an ethnic community. The Petions and their promoters specifically targeted Haitian New Yorkers, utilizing shared language, culture, and faith to bypass traditional skepticism. The Attorney General’s office noted that the scheme was promoted through prayer groups, WhatsApp chats, and social media platforms, where the founders often couched their financial promises in religious rhetoric, framing the investment opportunity as a divine blessing for the community.
A Chronology of Legal and Regulatory Action
The downfall of NovaTech was preceded by a series of warnings from regulators across the globe. As early as 2022, various Canadian securities regulators and several U.S. state agencies issued cease-and-desist orders against the company, noting that it was not registered to sell securities. Despite these red flags, NovaTech continued to operate, often rebranding its marketing materials or moving its digital infrastructure to evade oversight.
The collapse of the scheme became apparent in early 2023 when the platform began experiencing "technical difficulties" with withdrawals. By mid-2023, the Petions had reportedly ceased active communication with the bulk of their investor base, leading to a flood of complaints to law enforcement agencies.
The New York Attorney General’s office filed its initial lawsuit in June 2024, utilizing the Martin Act—New York’s powerful and expansive securities fraud law. The Martin Act allows the state to pursue civil and criminal charges for fraudulent practices in the sale of securities and commodities without having to prove that the defendants had a specific intent to defraud, though the evidence in the NovaTech case suggested a deliberate and calculated deception.
The timeline of the litigation reflects the complexity of tracking digital assets:
- June 2024: Initial lawsuit filed by the NY AG against NovaTech, the Petions, and AWS Mining.
- August 2025: The court issues a default order finding the defendants liable after they failed to mount a viable legal defense.
- November 2025: Promoter Martin Zizi enters into a stipulation and consent agreement.
- May 2026: Promoter Frantz Ciceron enters into a settlement agreement involving a $2 million obligation.
- October 22, 2026: The NY AG files the formal motion for $1.3 billion in damages and disgorgement against the primary defendants.
Accountability for High-Level Promoters
While the founders remain the primary targets, the New York Attorney General has also focused on the "top of the pyramid"—the promoters who facilitated the scheme’s growth. These individuals, including Frantz Ciceron, James Corbett, Ricardo Roy Sr., and Martin Zizi, were instrumental in bringing in thousands of new victims.
The state has secured nearly $6 million in total obligations from these promoters. The terms of these settlements vary, reflecting the level of cooperation and the assets available for recovery. For instance, Frantz Ciceron’s agreement is particularly extensive. It includes a $1.35 million cash relief component combined with the transfer of his rights to present and future distributions from the EminiFX receivership—another high-profile crypto-fraud case that targeted the same community.
Ciceron’s payment schedule underscores the long-term nature of the recovery process. His cash obligations include an initial $850,000 payment, followed by four annual installments of $125,000 due every December 31 from 2026 through 2029. These multi-year payment plans mean that even if the state is successful in its legal motions, the actual pool of funds available for victims will grow slowly over several years.
Challenges in Victim Restitution and Data Gaps
One of the most significant hurdles facing the Attorney General’s office is the lack of reliable data. The October 22 filing highlights a critical issue: the defendants have failed to provide the court-ordered accounting of their operations. This has left investigators with a massive dataset of cryptocurrency wallet addresses and usernames that cannot be easily linked to real-world identities.
The filing explains that most deposit usernames on the NovaTech platform cannot be reliably matched to specific individuals without the internal records the Petions have withheld. Furthermore, the nature of cryptocurrency transactions—where funds are often moved through multiple "hop" addresses or mixers—makes it difficult to verify exactly how much each individual lost versus how much they may have withdrawn during the life of the scheme.
The state argues that any withdrawals made by investors should not reduce the total amount NovaTech is required to surrender. This "gross disgorgement" approach is intended to ensure the defendants do not benefit from the money they circulated to keep the Ponzi scheme afloat. However, for the 11,000 victims, this legal complexity translates into a frustrating delay. The state cannot distribute funds until it can verify claims, a process that is stalled by the defendants’ non-compliance.
Broader Implications for the Crypto Industry
The NovaTech case serves as a stark warning about the dangers of the "crypto-frontier," where lack of regulation and high-yield promises create a fertile ground for fraud. The $1.3 billion demand is one of the largest sought by a state regulator in the history of cryptocurrency-related litigation, signaling that New York intends to remain the most aggressive jurisdiction for digital asset oversight.
Financial analysts suggest that this case may set a precedent for how "affinity fraud" is prosecuted in the digital age. By targeting the promoters alongside the founders, the Attorney General is sending a message that individuals can be held financially liable for the products they market, even if they were not the primary architects of the fraud.
Furthermore, the involvement of the EminiFX receivership in the Ciceron settlement reveals a troubling trend of "re-victimization." In many instances, individuals who lost money in one crypto scam were targeted by promoters of another, leading to a compounding financial crisis within the affected communities.
Conclusion and Future Outlook
As the court reviews the motion for the $1.3 billion judgment, the focus remains on the eventual distribution of recovered assets. The Attorney General’s office has emphasized that its priority is returning money to the victims, but the road ahead is fraught with logistical and legal obstacles. The Petions’ current whereabouts remain a subject of intense speculation, and if they have moved their assets into unhosted wallets or jurisdictions beyond U.S. reach, the actual collection of the $1.3 billion may prove difficult.
For the 11,000 New Yorkers who saw their savings vanish into the NovaTech ecosystem, the October 22 filing is a bittersweet development. It provides a formal validation of the scale of the fraud they endured, but it also confirms that the timeline for restitution is measured in years, not months. As the state continues to pursue the remaining promoters and seeks to uncover hidden assets, the NovaTech saga remains a cautionary tale of how the intersection of new technology and ancient deceptive practices can devastate entire communities.