admin
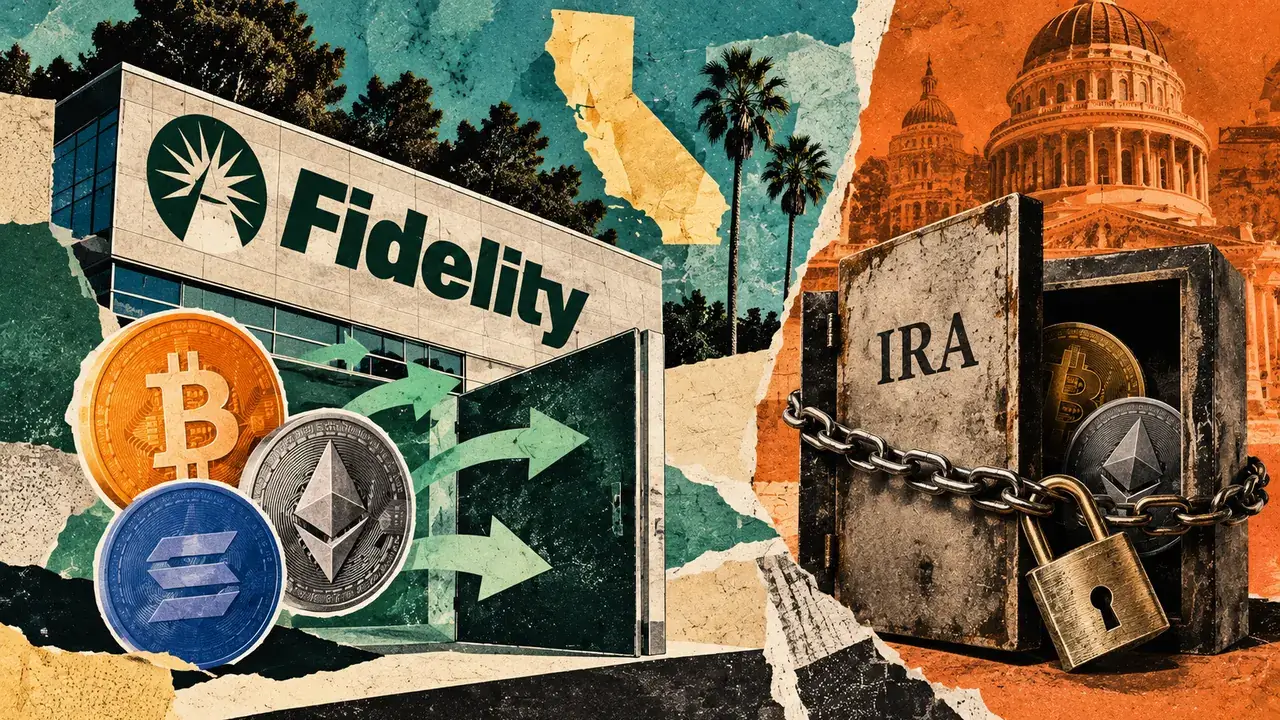
Fidelity Digital Assets’ recent $500,000 settlement with the state of California introduces a new requirement for written notification should the company discontinue its retail cryptocurrency transfer feature. Crucially, this agreement preserves existing security restrictions and explicitly excludes tax-advantaged accounts, such as Individual Retirement Accounts (IRAs), from its transfer obligations. This development, announced by California Attorney General Rob Bonta on October 16, addresses past concerns regarding withdrawal limitations at Fidelity Digital Asset Services. The settling entity, Fidelity Digital Assets, National Association, is the successor to the operational arm involved in the alleged issues. Fidelity has maintained its innocence, entering into the agreement without admitting any legal violations. The settlement includes a $500,000 payment to the Attorney General, intended to cover investigation-related fees and costs, and to resolve potential claims. It is important to note that the agreement does not establish a customer compensation fund.
The settlement agreement details a specific period, from November 2022 through April 2025, during which California retail customers were able to purchase and sell cryptocurrencies but were restricted from transferring them directly off the Fidelity platform. Regulatory approvals for such transfers were obtained in April 2025, and the feature was progressively rolled out to all California customers by June 2025. The agreement now acknowledges Fidelity’s existing capability to facilitate crypto transfers to external wallets, contingent upon adherence to applicable laws. Should Fidelity elect to cease offering this transfer functionality for its retail clientele, the company is now obligated to provide its California customers with reasonable written notice in advance. Furthermore, Fidelity retains the prerogative to implement restrictions or entirely disallow transfers when necessary to safeguard its platform’s integrity or the security of individual account holders. As of October 18, Fidelity’s state-availability page continues to list both crypto deposits and withdrawals as available for standard Fidelity Crypto accounts in California, indicating the ongoing operational status of these services.
Background and Chronology of the Agreement
The investigation leading to this settlement stemmed from allegations concerning Fidelity Digital Assets’ past practices regarding the transferability of cryptocurrencies for its retail customers in California. Between November 2022 and April 2025, a notable gap existed in the services offered: while clients could trade digital assets, the ability to move these assets to external wallets was curtailed. This period coincided with a dynamic and evolving regulatory landscape for digital assets, prompting scrutiny from state financial regulators concerned about consumer protection and market access.
The California Department of Justice, under Attorney General Rob Bonta, initiated an inquiry into these practices. The investigation focused on whether Fidelity’s policies during this timeframe constituted unfair or deceptive business practices, particularly in light of the growing interest in cryptocurrency ownership and the desire for greater control over digital assets through self-custody.
The resolution of this matter came in the form of a settlement agreement, executed on October 14, 2026, and publicly announced on October 16, 2026. This agreement stipulated a payment of $500,000 from Fidelity Digital Assets, National Association, to the State of California. This sum is designated to reimburse the state for expenses incurred during the investigation and to settle any potential claims that might have arisen from the alleged issues. A key point of clarification within the agreement is the explicit exclusion of customer compensation, indicating that the settlement is primarily regulatory in nature rather than compensatory for individual losses.
The settlement mandates that if Fidelity decides to withdraw the retail crypto transfer feature in the future, it must provide California customers with advance written notification. This clause aims to provide customers with adequate time to manage their digital assets and make alternative arrangements if necessary. This notice period is intended to mitigate any sudden disruption to customers who rely on the transfer functionality.
Exclusions for Tax-Advantaged Accounts
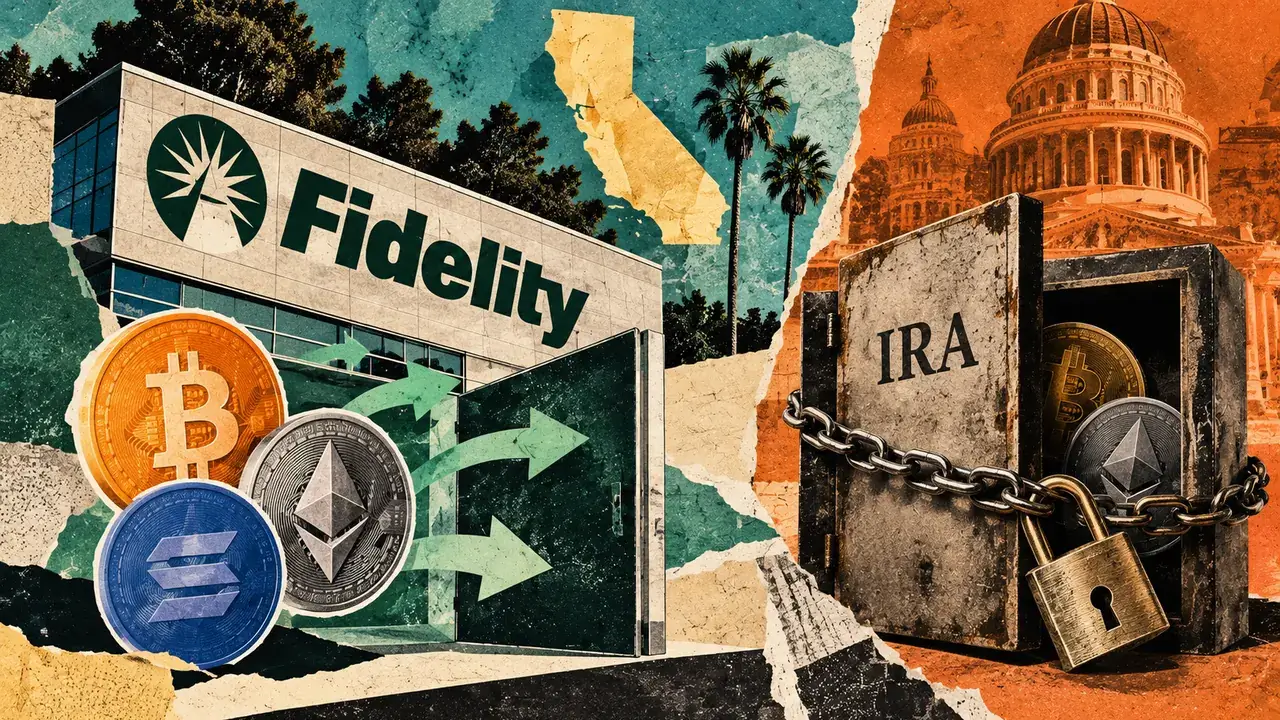
A significant aspect of the Fidelity settlement is its clear delineation regarding tax-advantaged accounts, most notably Individual Retirement Accounts (IRAs). The agreement expressly states that Fidelity’s obligations concerning crypto transfers do not extend to these accounts. This exclusion is critical for several reasons, primarily related to the distinct regulatory frameworks governing retirement accounts and the complexities associated with tax-deferred or tax-free growth.
Fidelity Digital Assets has indicated plans to introduce Fidelity Crypto IRA accounts in California, though a specific launch date has not yet been announced. The settlement agreement explicitly removes these future IRA offerings, as well as existing ones subject to federal regulations for non-taxable transfers between retirement accounts, from the scope of the transfer obligation. This means that even if Fidelity offers standard retail crypto transfers, the rules for moving cryptocurrencies within or out of a Fidelity Crypto IRA may remain subject to different, and potentially more restrictive, protocols.
Current information available on Fidelity’s website, as of October 18, 2026, confirms that Fidelity Crypto IRAs are not yet available in California and Oregon. For states where Fidelity Crypto IRAs are offered, the company’s Frequently Asked Questions (FAQs) outline specific limitations. These include the unavailability of direct crypto transfers out of the IRA and the inability to withdraw cash or cryptocurrency directly from the account. Instead, customers are directed to move their U.S. dollar holdings to a linked Fidelity brokerage IRA. This brokerage IRA can then be utilized for its established withdrawal features, providing an indirect route for liquidity. This structured approach is designed to align with the stringent rules governing retirement accounts, which prioritize long-term investment and penalize early or unauthorized withdrawals.
The distinction between standard crypto accounts and crypto IRAs is a crucial point for consumers to understand. While the settlement offers enhanced transparency and notice for retail account holders regarding transfer features, the operational guidelines for retirement accounts remain under a different, more specialized set of compliance requirements. This separation ensures that Fidelity navigates the complex regulatory environment governing both retail investment products and tax-advantaged retirement vehicles.
Supporting Data and Market Context
The settlement arrives at a time when the cryptocurrency market continues to mature, with increasing institutional and retail adoption. As of late 2026, the total market capitalization of cryptocurrencies hovers around $X trillion, with Bitcoin and Ethereum remaining the dominant assets by market share. Fidelity, as a major player in traditional finance with a growing presence in digital assets, plays a significant role in shaping consumer access and trust in this emerging asset class.
The period between November 2022 and April 2025, highlighted in the settlement, was a particularly volatile phase for the crypto market. Following the collapse of major entities like FTX in late 2022, regulatory scrutiny intensified globally. Many jurisdictions, including U.S. states, began to reassess their oversight of cryptocurrency exchanges and custodians, focusing on issues of customer asset protection, transparency, and operational resilience. During this time, several platforms faced challenges with withdrawals and transfers, leading to increased caution among regulators.
Fidelity’s entry into the crypto space, particularly with its offerings for retail investors and its foray into IRAs, reflects a broader trend of established financial institutions integrating digital assets into their product suites. The company’s commitment to providing secure and compliant solutions is paramount, especially when dealing with sensitive financial products like retirement accounts. The $500,000 settlement, while a relatively modest sum for a firm of Fidelity’s size, signifies the importance of regulatory compliance and consumer protection in the digital asset sector.
The ability to transfer cryptocurrencies to external wallets is a fundamental aspect of digital asset ownership, often referred to as self-custody. This feature allows users to have full control over their private keys and thus their assets, a core tenet of the cryptocurrency ethos. Restrictions on this functionality can be a point of contention for users who value this level of autonomy. The settlement’s focus on ensuring adequate notice for the discontinuation of such a feature addresses this user concern.
Analysis of Implications and Broader Impact
This settlement carries several significant implications for Fidelity and the broader cryptocurrency industry. For Fidelity Digital Assets, it represents a regulatory resolution that clarifies its obligations regarding retail crypto transfers in California. The commitment to provide written notice before discontinuing the feature enhances transparency and builds trust with its California customer base. The exclusion of IRAs from these transfer obligations underscores Fidelity’s adherence to the specialized regulatory demands of retirement accounts, ensuring that its crypto IRA offerings are structured in a manner compliant with federal tax laws. This distinction is vital, as the rules governing IRAs are more stringent and carry different enforcement mechanisms than those for standard brokerage or crypto accounts.
The settlement also sets a precedent for how state regulators will approach similar issues with other cryptocurrency platforms. The emphasis on clear communication and customer notification in the event of service changes is likely to become a standard expectation across the industry. This could lead to more proactive engagement between crypto firms and state regulatory bodies to ensure compliance and avoid future disputes.
For consumers, particularly those in California, the settlement brings a degree of certainty. They are assured that Fidelity will not arbitrarily remove the ability to transfer their retail crypto assets without prior warning. The explicit exclusion of IRAs, while perhaps disappointing for some who might have envisioned seamless crypto transfers within their retirement portfolios, reinforces the unique nature of these accounts and the regulatory safeguards that surround them. It also highlights the current limitations of integrating cryptocurrencies directly into IRA structures, often requiring indirect methods like moving funds to a linked brokerage account.
The broader impact on the cryptocurrency market involves the ongoing effort to legitimize and integrate digital assets into the traditional financial system. By engaging with regulators and reaching settlements, firms like Fidelity contribute to the development of a more robust and regulated ecosystem. This, in turn, can foster greater investor confidence and pave the way for wider adoption of cryptocurrencies, including their use within retirement planning. The case underscores the critical need for transparency, clear communication, and adherence to the distinct regulatory frameworks that govern different types of financial products, especially in the rapidly evolving digital asset landscape.
As Fidelity continues to expand its digital asset offerings, including the planned introduction of Crypto IRAs in California, its adherence to this settlement will be closely watched. The company’s approach to managing customer expectations and navigating the complex regulatory environment will be a key factor in its long-term success in the cryptocurrency sector. The settlement serves as a reminder that while innovation is crucial, it must be balanced with a steadfast commitment to consumer protection and regulatory compliance.