admin
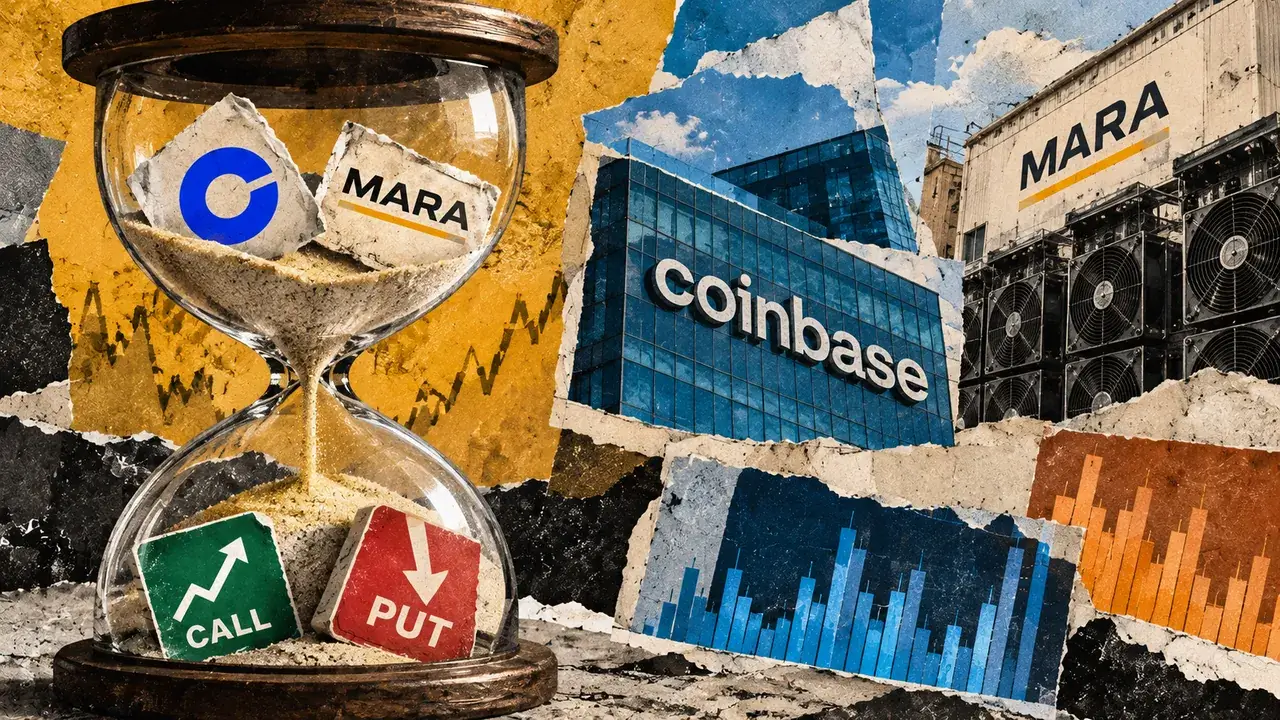
The SEC has officially approved new rules that will allow the options exchange Cboe to list binary options contracts tied to the reported financial metrics of major cryptocurrency-related companies, specifically Coinbase and Marathon Digital Holdings (MARA). This landmark decision ensures that once these options contracts have expired and their payouts have been determined, any subsequent corrections or restatements of the underlying company’s reported figures will not alter the settled outcome. This regulatory green light marks a significant development in the intersection of traditional finance and the burgeoning digital asset market, offering new avenues for sophisticated investors to speculate on key performance indicators (KPIs) of publicly traded crypto firms.
The order, officially dated October 13, 2026, was subsequently published in the Federal Register on October 16, 2026, signaling the final step in the approval process. While the regulatory framework is now in place, the exact date for the trading availability of these specific Coinbase and MARA series, and importantly, the eligibility for retail investors utilizing platforms like Robinhood, remained unconfirmed as of October 17, 2026. Industry observers are keenly awaiting further announcements from Cboe and its partners regarding the precise launch timeline and the scope of accessibility for these novel financial instruments.
Defining the Contested Metrics: Coinbase and MARA
The approved rules delineate specific metrics that will underpin these new binary options. For Coinbase, the eligible metrics encompass crucial aspects of its business operations, including its transaction revenue, subscription and services revenue, and its total trading volume. These indicators provide a comprehensive snapshot of the cryptocurrency exchange’s commercial activity and its ability to generate revenue from both its trading platform and its expanding suite of digital asset services.
For Marathon Digital Holdings (MARA), a prominent Bitcoin mining company, the focus will be on its operational output and asset base. The permitted metrics include the amount of Bitcoin produced during a given period and its total Bitcoin holdings. These figures are central to assessing the efficiency and scale of MARA’s mining operations, as well as its strategic reserve of the cryptocurrency it mines.
The Mechanics of Binary Options and Settlement Finality
The core of these new contracts lies in their binary nature, offering a straightforward "yes" or "no" proposition based on whether a reported metric meets or falls below a predetermined threshold. The settlement process is designed to be robust and final. Ordinary settlement relies on the designated metric as reported by the company in its earnings-related filings with the Securities and Exchange Commission (SEC). Cboe, at the time of listing an option contract, clearly defines both the specific metric and the reporting period it pertains to. This clarity ensures that each contract has a precise figure against which its outcome will be resolved.
A "call" option, in this context, pays out if the reported company figure for the specified period equals or exceeds the contract’s pre-set threshold. Conversely, a "put" option pays out if the reported figure falls below that threshold. The standard gross payout for a successful contract is set at $1, although this amount is subject to potential adjustments and adherence to alternative settlement rules that may be invoked under specific circumstances. The ultimate profit or loss for the buyer of such an option is, naturally, contingent upon the initial purchase price of the contract and any associated trading costs that may apply.
The critical aspect of the newly approved rules is the "restatement provision." This provision explicitly states that once an option contract has expired and its settlement has been finalized, any subsequent correction or restatement of the company’s reported figure will have no bearing on the outcome. This means that if an option settled without a payout because the reported number was below the threshold, a later revision by the company to a figure that would have met the threshold will not retroactively trigger a payout. Similarly, if an amount was already paid out based on the initial report, that payout is considered final and cannot be reclaimed or adjusted due to a later revision. This "set-it-and-forget-it" approach to settlement aims to provide certainty and reduce the potential for disputes arising from fluctuating or corrected financial data.
Navigating Delays and Alternative Settlement Procedures
The regulatory framework also addresses potential disruptions to the reporting and settlement process, particularly concerning delayed disclosures or unavailable metrics. A delayed disclosure of a key metric can lead to a postponement of the settlement process. In such scenarios, the clearinghouse will typically wait for the required metric to become available before proceeding. It is important to note that while settlement may be delayed, the trading of the option itself still ceases on the scheduled expiration date, and this expiration date remains immutable.
In instances where a metric will simply not become available, or in other exceptional cases, the rules allow for the invocation of alternative clearing procedures. These alternative procedures can significantly alter the settlement outcome. One such procedure may involve using the option’s last closing price on the trading platform as the basis for the settlement amount. This differs from the ordinary all-or-nothing payout structure and can lead to a more nuanced financial resolution, reflecting the market’s valuation of the option contract at the close of trading.
However, the rules also provide a safeguard against unreliable pricing information. If the last closing price is deemed unavailable or if the clearinghouse, Cboe Clear U.S., determines it to be unreliable, the option contract may expire unexercised and consequently, be deemed worthless. This ensures that settlements are based on as accurate and reliable information as possible, even when standard reporting channels are compromised.
A Phased Rollout and Strategic Partnerships
The development and proposed launch of these KPI contracts have been a deliberate and phased process. A significant announcement from Cboe on September 30, 2026, outlined a planned October rollout that would encompass contracts for 23 different companies, subject to the necessary regulatory approvals. In this initial announcement, Robinhood was prominently identified as the first retail broker that would offer these contracts to its customer base upon launch.
Further reinforcing this plan, an update on October 8, 2026, reiterated the conditional nature of the rollout, underscoring the ongoing dependency on regulatory clearance. The approval record itself includes a commitment from Cboe to refrain from listing these options until all applicable filings and documents with Cboe Clear U.S. have undergone SEC review and have been approved or declared effective. This meticulous approach highlights the exchange’s dedication to ensuring full compliance and operational readiness before introducing these new financial products to the market.
Background and Broader Implications
The introduction of these binary options represents a natural evolution in the financial landscape, driven by the increasing sophistication of both market participants and the underlying assets they trade. For years, investors have sought ways to gain exposure to the performance of companies and sectors that were not traditionally served by standard derivatives. The rise of cryptocurrencies and blockchain technology has presented unique challenges and opportunities, leading to the development of new financial instruments designed to capture the specific dynamics of this evolving market.
The inclusion of Coinbase and MARA is particularly noteworthy. Coinbase, as one of the largest publicly traded cryptocurrency exchanges, is a bellwether for the health of the digital asset trading ecosystem. Its transaction volumes and revenue streams are directly correlated with retail and institutional adoption of cryptocurrencies. MARA, on the other hand, represents the vital infrastructure of the Bitcoin network – the mining sector. Its production levels and holdings are critical indicators of the profitability and operational capacity of Bitcoin mining. By allowing bets on these specific KPIs, Cboe is enabling investors to directly engage with the fundamental drivers of success for these companies.
Potential Impact on Market Dynamics
The implications of these approved rules are multifaceted. For institutional investors and sophisticated traders, these binary options offer a new and potentially highly liquid avenue for expressing views on specific aspects of companies within the cryptocurrency industry. They can be used for hedging, speculation, or as part of more complex derivative strategies. The fixed payout structure simplifies risk assessment, making it easier to calculate potential gains and losses.
For retail investors, particularly those active on platforms like Robinhood, the introduction of these contracts could democratize access to a new form of market participation. The ability to make relatively small, binary bets on concrete metrics could appeal to a broad range of individuals who are interested in the cryptocurrency space but may not have the expertise or capital for traditional options trading.
However, the inherent simplicity of binary options also carries risks. The all-or-nothing payout structure means that a small misjudgment can result in the complete loss of the invested capital. The emphasis on financial reporting means that understanding accounting practices and the nuances of SEC filings will be crucial for successful participation. Furthermore, the speculative nature of these contracts means that they could contribute to increased volatility in the underlying stock prices if significant trading volumes emerge, although this remains to be seen.
Regulatory Scrutiny and Future Outlook
The SEC’s approval process for such novel financial products is typically rigorous, involving extensive review of the proposed rules, the underlying mechanics, and the potential impact on market integrity and investor protection. The inclusion of the restatement provision, ensuring settlement finality, is a key element designed to address concerns about data integrity and potential disputes.
The success of these Coinbase and MARA binary options will likely pave the way for Cboe to expand its offerings to other companies within the digital asset ecosystem and potentially beyond. As the lines between traditional finance and the burgeoning digital asset markets continue to blur, financial innovation is expected to accelerate. Regulatory bodies will play a critical role in navigating this evolving landscape, ensuring that new products are introduced responsibly and with adequate safeguards for investors. The coming months will be critical in observing how these new contracts are received by the market and whether they fulfill their promise of providing innovative and accessible investment opportunities tied to the performance of key players in the cryptocurrency industry.