admin
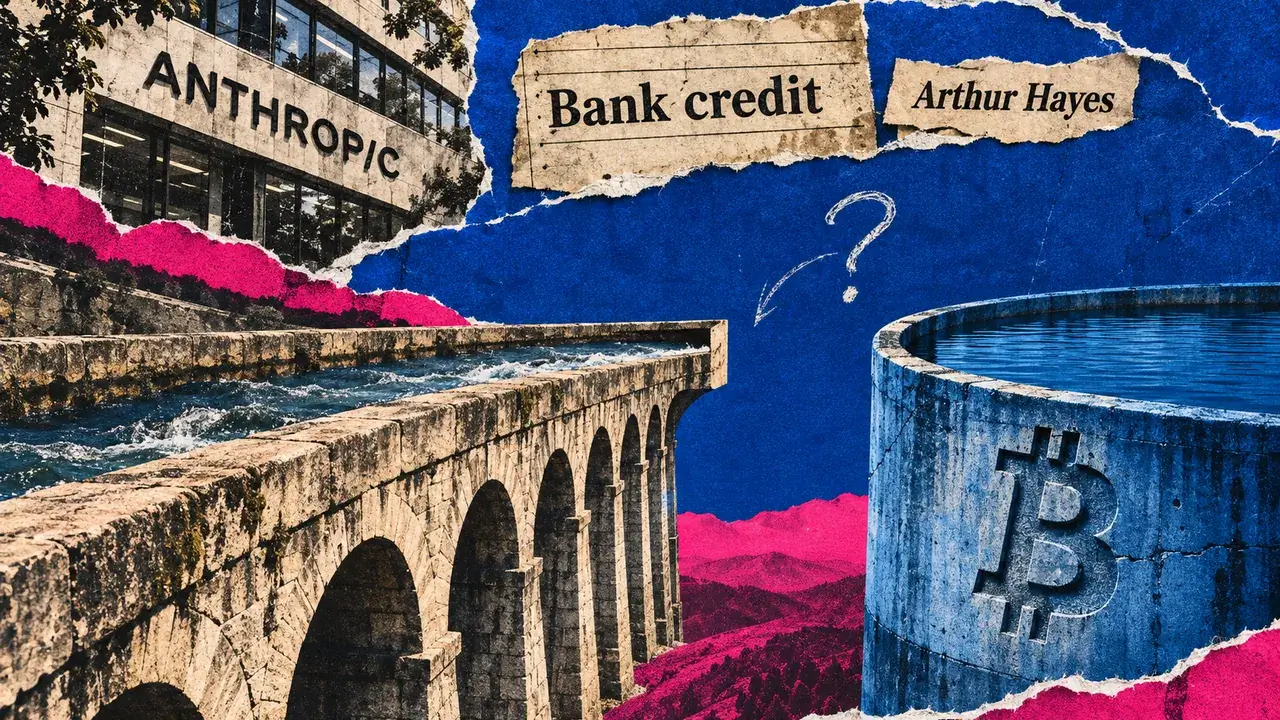
The impending Initial Public Offering (IPO) of Anthropic, a prominent artificial intelligence company, has ignited discussions about the significant risk of insider selling. While the company’s proposed share-release schedule is still under scrutiny, its implications for Bitcoin liquidity remain a subject of intense analysis. Arthur Hayes, a notable figure in the cryptocurrency space, has posited that the potential decline in AI company share prices could herald a broader credit crunch, with insider sales playing a pivotal role in weakening stock markets, escalating borrowing costs, restricting bank balance sheet expansion, and ultimately diminishing the dollar liquidity that underpins the cryptocurrency ecosystem.
Hayes’s analysis, presented in a widely circulated essay on November 5th, projects a substantial dilution for Anthropic, estimating it to reach 83% by June 2027. He further calculated that absorbing potential selling pressure at a hypothetical IPO valuation of $1.5 trillion would necessitate approximately $1.245 trillion in new capital. Anthropic’s upcoming offering serves as a tangible test case for the initial link in Hayes’s chain of reasoning. The creation of new shares during the IPO, coupled with subsequent releases of existing holdings by early investors and employees, presents a complex dynamic of supply and demand. These distinct changes in share availability carry differing consequences for the company’s fundraising capabilities and the ownership stakes of its investors.
Understanding the Dynamics of Share Supply
Anthropic’s announcement on November 10th outlined a proposed IPO of 825 million Class A shares. Of this total, 801,351,354 shares are slated to be offered by the company itself, with the remaining 23,648,646 shares to be sold by existing stockholders. Crucially, Anthropic will not receive any proceeds from the sales conducted by these existing holders. The preliminary price range for these shares has been set between $70 and $78, with an additional option for underwriters to purchase up to 123.75 million shares, a common practice to meet unexpected demand or stabilize the stock price post-listing.
The distinction between new company shares and secondary shares is fundamental to understanding the financial flows. When a company issues new shares, it increases the total number of outstanding shares and, more importantly, injects fresh capital directly into the company’s coffers, funding its operations, research, and development. In contrast, secondary shares are existing shares that are being sold by current owners, such as founders, early investors, or employees. The proceeds from these secondary sales go directly to the selling holders, not to the company. While secondary sales can provide liquidity for early stakeholders and signal confidence in the company’s future, they do not contribute to the company’s capital base.
A subsequent "unlock" period, often referred to as a lock-up expiration, is another critical factor. This phase removes restrictions on selling shares that were previously held by insiders or early investors. During a lock-up period, these shareholders are contractually prevented from selling their shares, thereby limiting the immediate supply of stock on the open market. When the lock-up expires, these shares become eligible for sale, potentially increasing the available float and creating downward pressure on the stock price if significant selling occurs. It is this subsequent eligibility for resale, rather than the initial sale of existing shares, that represents a potential drain on external liquidity.
Quantifying the Potential Dilution and Share Floats
Under the preliminary assumptions of the IPO and a concurrent private placement, the total number of legal Class A and Class N shares is projected to increase from approximately 11.9 billion to over 13 billion. This represents an increase of roughly 9.66%. This figure reflects the new shares issued by the company and the secondary shares being offered.
However, the total pool of securities potentially subject to future sales is considerably larger. The approximately 15.5 billion Class A-equivalent securities, which include Class N shares, employee stock awards, and convertible notes, represent a broader measure of potential future supply. This pool encompasses more securities than are currently outstanding as Class A stock and differs significantly from the freely tradable float available immediately after the IPO. Employee stock awards and convertible instruments, when certain conditions are met (such as performance milestones or conversion triggers), can lead to the issuance of additional shares, further expanding the total share count.
The preliminary resale disclosures provide a clearer picture of the staggered release of shares held by existing stockholders. From the first trading day, up to approximately 316 million additional shares may become eligible for sale. This is followed by further tranches: 299 million shares at 27 days after the U.S. prospectus date, another 299 million at 48 days, 349 million at 62 days, and a final 349 million at 76 days.
Beyond these fixed timelines, the release of shares held by non-founder personnel and certain other holders is tied to specific triggers. These restrictions typically end at the earlier of the announcement of the company’s first-quarter financial results or a 180-day post-IPO period. For co-founders and certain larger, more significant holders, the lock-up periods are generally longer, ending at the earlier of the third-quarter results announcement or a 365-day post-IPO period. Importantly, these timelines can include staged early-release exceptions, adding another layer of complexity to the anticipated supply dynamics.
The earnings-linked triggers are particularly noteworthy, as they depend on the timing of public earnings announcements and subsequent trading day intervals. Furthermore, representative waivers granted by the company and other contractual restrictions can introduce further conditions and variations to these release schedules.
The theoretical value calculated by Hayes, which multiplies a hypothetical $1.5 trillion IPO valuation by an 83% dilution factor to arrive at $1.245 trillion, is a valuable exercise but relies on several assumptions. The actual capital required to absorb selling pressure will depend on a multitude of factors, including which specific holders decide to sell, the prices at which buyers are willing to purchase the stock, and the overall demand for Anthropic’s shares in the market. A strong market appetite for AI companies could absorb significant selling pressure without a drastic price decline, whereas a weaker market sentiment could exacerbate the impact of insider sales.
The Evolving Credit Landscape: Evidence and Scenarios
The Federal Reserve’s H.8 release on November 13th, published after Hayes’s essay, provided a snapshot of the banking sector’s credit activity. Seasonally adjusted bank credit rose from $20.02 trillion on October 28th to $20.08 trillion on November 4th, marking an increase of $58 billion. This data indicates an aggregate expansion of bank credit during the reported week. While this specific release does not offer a breakdown of lending specific to the AI sector, nor does it provide direct causal evidence linking it to Bitcoin liquidity, it offers a point of reference for the broader credit environment.
Hayes’s warning about a potential credit crunch remains a valid scenario that warrants close observation. A confluence of factors, including significant insider selling from a prominent AI firm like Anthropic, leading to weaker share prices, higher financing costs for businesses, and consequently reduced lending by financial institutions, would indeed support the successive links in his proposed chain of economic disruption. The interconnectedness of financial markets means that distress in one sector can ripple through others.
The conditional IPO timetable for Anthropic brings the immediate test of insider selling risk into sharper focus. However, the transmission mechanism from changes in share supply to the liquidity of Bitcoin remains an area that requires further empirical evidence. While the theoretical links are plausible, the actual impact will depend on market reactions, investor behavior, and the broader macroeconomic context.
Broader Implications and Market Reactions
The IPO of a company as prominent as Anthropic is not just a financial event for the company and its investors; it is a bellwether for the broader technology and venture capital markets. The valuation achieved by Anthropic, and the subsequent trading performance of its stock, will undoubtedly influence investor sentiment towards other AI companies seeking to go public or raise further funding.
If Hayes’s predictions of a credit squeeze materialize, the increased cost of borrowing could have a chilling effect on startup funding. Companies reliant on venture capital or debt financing might find it more challenging to secure the capital they need to operate and grow. This could lead to a slowdown in innovation and potentially a wave of down rounds or even insolvencies for less well-capitalized businesses.
For the cryptocurrency market, a reduction in dollar liquidity could translate into decreased investment inflows. Bitcoin and other cryptocurrencies often attract capital from investors seeking higher returns or diversification. If dollar liquidity tightens, investors may reallocate capital away from riskier assets like cryptocurrencies towards more traditional or safer investments. This could put downward pressure on crypto prices and reduce trading volumes.
Reactions from related parties, such as venture capital firms that have invested heavily in Anthropic, are likely to be carefully managed. While they would benefit from a successful IPO, they are also acutely aware of the potential for insider selling to depress stock prices. Their public statements are likely to emphasize the long-term growth prospects of AI and Anthropic’s unique position in the market, while privately strategizing on how to navigate the post-IPO trading environment.
The broader economic implications extend beyond financial markets. A sustained credit crunch could lead to slower economic growth, increased unemployment, and a general tightening of financial conditions for consumers and businesses alike. The AI sector, which is seen as a major engine of future economic growth, could itself face headwinds if funding dries up and demand for its products and services softens.
Conclusion: A Watchful Eye on the AI IPO and Crypto Nexus
Anthropic’s planned IPO presents a critical juncture for assessing the interconnectedness of the technology sector and the cryptocurrency market. The detailed examination of its share-release schedule highlights the tangible risk of significant insider selling, which could indeed exert downward pressure on its stock price. However, the extent to which this translates into a drain on Bitcoin liquidity is a more complex question that hinges on a multitude of macroeconomic and market-specific factors yet to fully unfold. The Federal Reserve’s data on bank credit provides an initial, albeit broad, indication of the prevailing credit conditions, but a direct causal link to Bitcoin’s liquidity remains to be conclusively established. As the IPO process progresses and more information becomes available regarding share allocations, lock-up expirations, and market demand, a clearer picture of these potential impacts will emerge. The financial world will be watching closely to see if the speculative scenarios discussed by analysts like Arthur Hayes materialize, and how the AI IPO phenomenon ultimately shapes the liquidity landscape of the digital asset markets.