Dwi Wanna
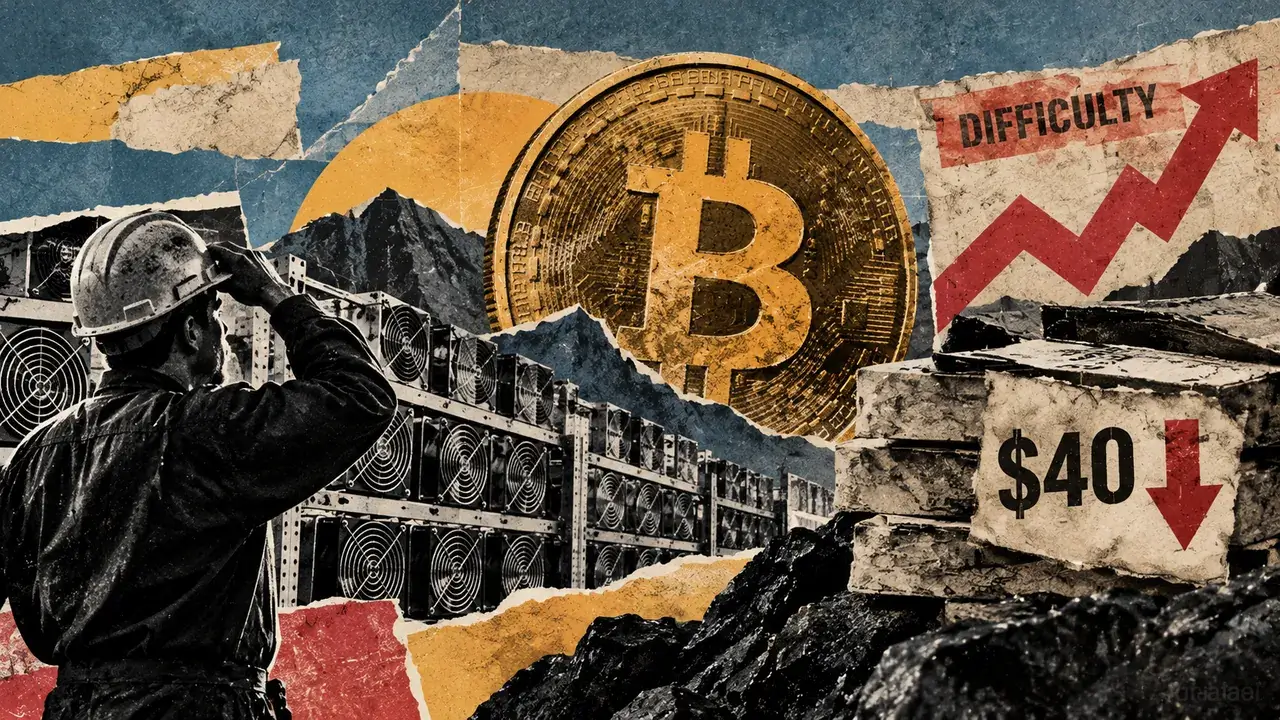
If the market price of Bitcoin, the block subsidy, and average transaction fees remain static, the expected revenue per unit of computing power—commonly referred to as "hashprice"—is forecasted to drop by approximately 5.37%. This adjustment comes at a time when the mining industry is still grappling with the long-term effects of the April 2024 halving, which slashed the block reward from 6.25 BTC to 3.125 BTC. As the difficulty rises, the "cushion" between operational costs and gross revenue is thinning to a point of near-transparency for many market participants.
The Mechanics of the Difficulty Adjustment
The Bitcoin network is designed to maintain a consistent block production rate of approximately one block every ten minutes. To ensure this consistency, the protocol automatically adjusts its mining difficulty every 2,016 blocks—a period roughly equivalent to two weeks. When the aggregate hashrate (the total computational power dedicated to the network) increases, blocks are found faster than the ten-minute target. In response, the network increases the difficulty of the mathematical puzzles miners must solve, thereby slowing down production.
The upcoming adjustment follows a period of significant hashrate expansion. As of October 14, 2024, the network difficulty stood at 132.72 trillion. The projected 5.68% rise would push this figure to new heights, reflecting a surge in global mining capacity as institutional players deploy more powerful, next-generation ASICs (Application-Specific Integrated Circuits). While a rising hashrate is a sign of network security and long-term miner confidence, it presents an immediate existential threat to those operating on thin margins.
The Erosion of Hashprice and the $40 Threshold
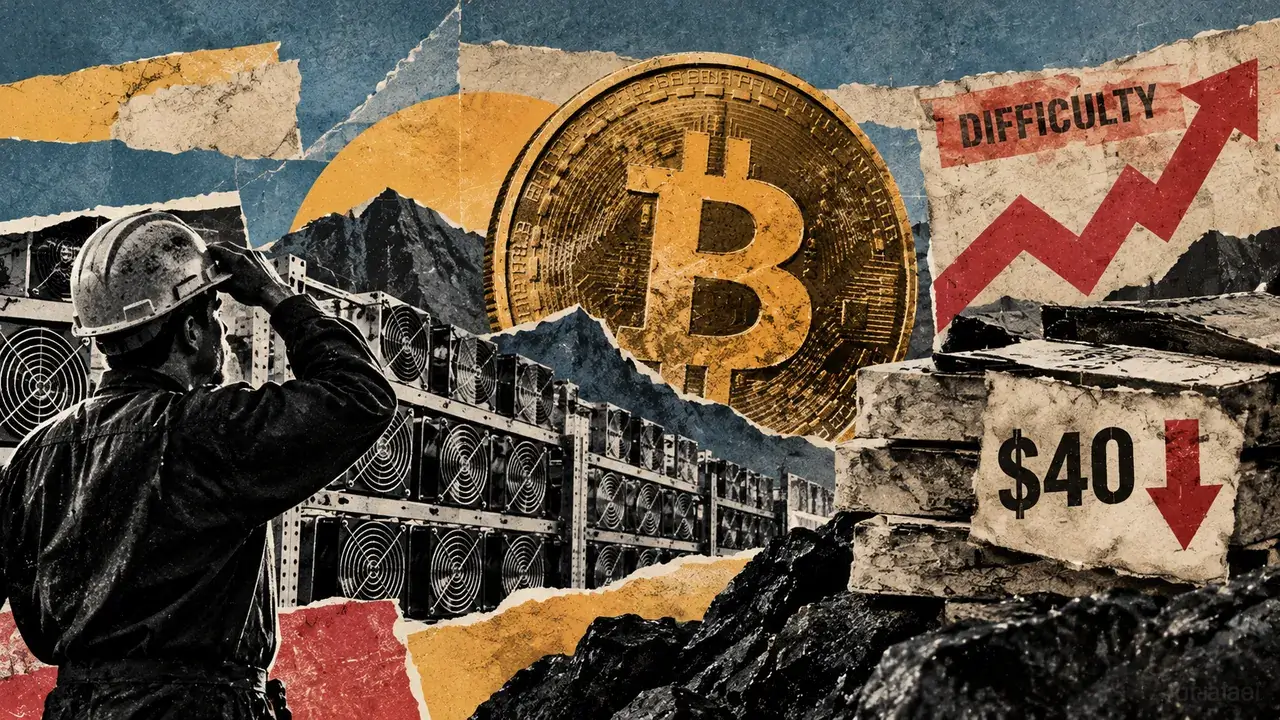
In the mining industry, "hashprice" is the primary metric used to gauge daily revenue potential. It represents the expected dollar value earned from one petahash per second (PH/s) of computing power over a 24-hour period. Recent data from Startmining’s network dashboard and Luxor’s Hashrate Index show that the hashprice has been hovering precariously near the $40 mark.
On October 14, the hashprice was recorded at $39.77 per PH/day. Following the projected difficulty increase, and assuming all other variables remain equal, this figure is expected to retreat to approximately $37.63. This 5.37% reduction in revenue per unit of work is a direct mathematical consequence of the difficulty rise; as the probability of finding a block decreases for a fixed amount of work, the revenue generated by that work must necessarily decline.
The significance of the $40 level cannot be overstated. For many operators using hardware from the previous generation—such as the Bitmain Antminer S19 series—the $40 hashprice represents the "break-even" point. When revenue dips below this level, the cost of the electricity required to run the machines begins to cannibalize the entire reward, leaving nothing for maintenance, staff, or debt service.
Efficiency Tiers and Electricity Ceilings
The impact of the difficulty adjustment is not felt equally across the industry. Profitability is determined by two primary factors: the efficiency of the mining hardware (measured in Joules per Terahash, or J/TH) and the cost of electricity (measured in cents per kilowatt-hour, or kWh).
To illustrate the severity of the upcoming squeeze, consider a mining rig with an efficiency of 20 J/TH. At an electricity cost of 8 cents per kWh, this machine incurs a daily power bill of $38.40 per PH/s. At the October 14 hashprice of $39.77, the operator retains a modest "cushion" of $1.37 per day. However, once the difficulty adjusts and the hashprice falls to the projected $37.63, that cushion vanishes, replaced by a daily shortfall of $0.77. In this scenario, the miner is effectively paying $0.77 a day for the privilege of keeping the machine running, a situation that is unsustainable for any commercial enterprise.
The following table demonstrates the maximum electricity price an operator can pay to remain at a "gross-zero" profit level (where revenue exactly covers electricity) before and after the projected adjustment:
| Hardware Efficiency | Pre-Adjustment Ceiling (cents/kWh) | Post-Adjustment Ceiling (cents/kWh) |
|---|---|---|
| 15 J/TH (High-End) | 11.05 | 10.45 |
| 20 J/TH (Standard) | 8.29 | 7.84 |
| 25 J/TH (Mid-Tier) | 6.63 | 6.27 |
| 30 J/TH (Older Gen) | 5.52 | 5.23 |
These "ceilings" are conservative estimates. They do not account for pool fees (typically 1-2%), cooling costs, site overhead, hardware repairs, or the interest on loans used to purchase the equipment. For a miner using 30 J/TH equipment, an electricity rate of just 5.5 cents per kWh becomes unprofitable after the adjustment. Given that average industrial electricity rates in many regions of the United States and Europe exceed 7 cents per kWh, a significant portion of the global hashrate is currently standing on the edge of a financial precipice.
Chronology of Recent Network Trends
The road to the October 16 adjustment has been marked by a steady climb in network competition.
- August 2024: Following a mid-summer lull where hashrate dipped due to heat-related curtailment in Texas and other mining hubs, the network began to see a resurgence in active machines.
- September 2024: Difficulty adjustments remained relatively flat, providing a brief window of stability for miners. However, Bitcoin’s price volatility during this month kept hashprice suppressed near $40.
- October 9, 2024: Hashprice briefly surged above $40 as Bitcoin’s price saw a localized rally. This provided temporary relief and led to an increase in the number of machines being turned back on.
- October 14, 2024: With only 347 blocks remaining until the next retarget, the hashrate remained high, locking in the projection for a substantial difficulty increase.
The increase in difficulty is a lagging indicator of miner confidence. The fact that hashrate has risen enough to trigger a 5.68% difficulty jump suggests that large-scale, institutional miners are continuing to deploy capital and new hardware, despite the low hashprice.
Industry Response and Strategic Shifts
Market analysts from firms like Luxor and Hashrate Index have noted a growing divergence in the mining sector. On one side are the "industrial titans"—publicly traded companies like Marathon Digital, Riot Platforms, and Core Scientific—who have secured low-cost power contracts and are aggressively upgrading to 15 J/TH or 17 J/TH machines (such as the Antminer S21 or MicroBT Whatsminer M60 series). These players can withstand a $37 hashprice because their operational costs are significantly lower.
On the other side are the independent and "legacy" miners. For these participants, the upcoming difficulty rise is a signal to either "evolve or exit." Many are choosing to pivot their strategies. Some are engaging in "curtailment," where they shut down machines during peak electricity pricing hours to save costs. Others are seeking to move their operations to regions with stranded energy or lower regulatory costs, such as parts of Africa or South America.
There is also a growing reliance on transaction fees to bolster the block subsidy. The emergence of protocols like Ordinals and Runes has occasionally caused fee spikes, momentarily doubling or tripling the hashprice. However, these spikes are unpredictable and do not provide the consistent revenue floor needed for long-term financial planning.
Broader Impact and Network Implications
The immediate implication of a difficulty rise during a period of stagnant price action is "miner capitulation." If a significant number of rigs become unprofitable and are turned off, the network hashrate will drop. This, in turn, will lead to a difficulty decrease in the following adjustment cycle (late October or early November).
While some critics point to these cycles as a sign of Bitcoin’s instability, proponents argue that this is the protocol working exactly as intended. The "difficulty bomb" ensures that only the most efficient and fiscally responsible miners survive, which ultimately makes the network more resilient. However, there is a risk of increased centralization. If only the largest companies with the cheapest power can afford to mine, the decentralized nature of Bitcoin’s security could be challenged.
Furthermore, the pressure on miners often translates to sell-side pressure in the Bitcoin market. Miners are frequently forced to sell their hoarded BTC to cover operational deficits during these "squeezes," which can act as a headwind for Bitcoin’s price.
As block 971,712 approaches, the mining community remains focused on the only two variables that can offset the difficulty rise: a significant increase in the price of Bitcoin or a sustained surge in network transaction fees. Without one of these catalysts, the October 16 retarget may mark the end of the line for a generation of Bitcoin mining hardware.