admin
The United States Senate delivered a significant policy setback to the decentralized finance (DeFi) sector on September 15th when it failed to advance the CLARITY Act, a comprehensive digital-asset market-structure bill. In the immediate aftermath of this procedural vote, Aave founder Stani Kulechov pivoted the disappointment into a call to action, proposing a new product-centric strategy for DeFi to gain political relevance. Aave, a prominent decentralized lending protocol, has been actively developing a suite of consumer and institutional products through its subsidiary, Aave Labs.
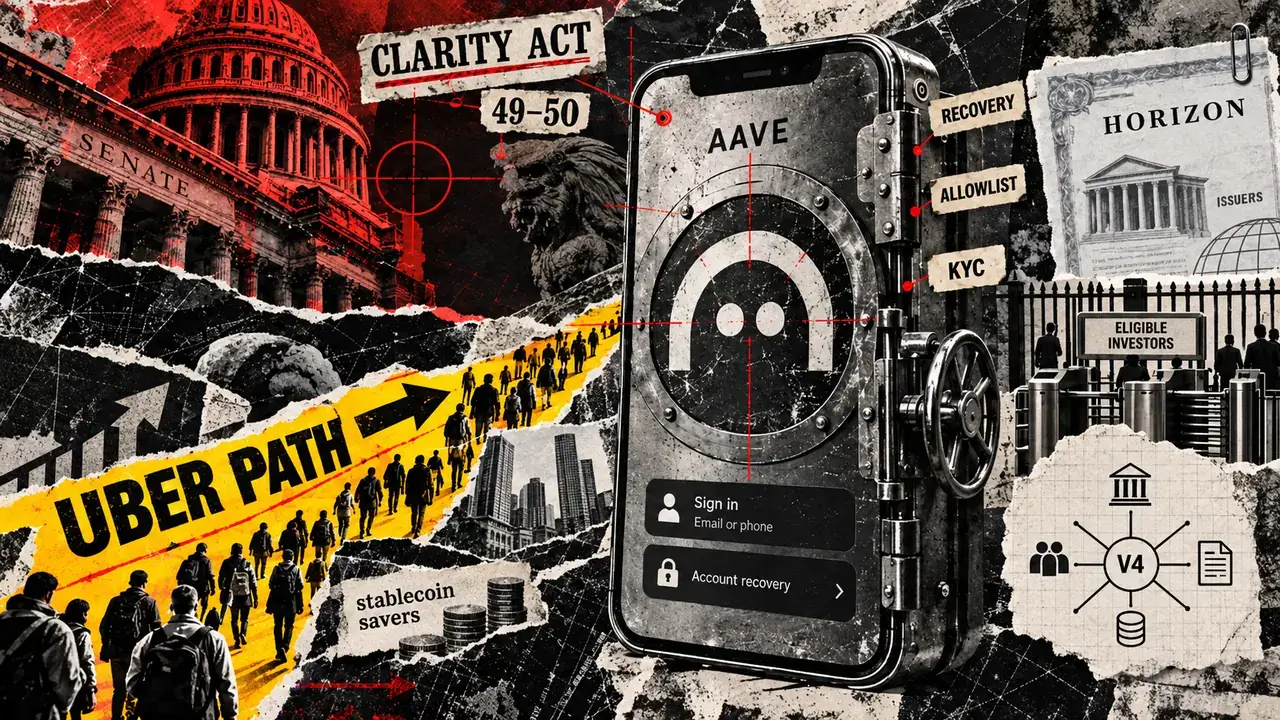
The pivotal procedural vote occurred at 2:19 p.m. Eastern time. Senators voted 49-50 to reject cloture on the motion to proceed to H.R. 3633, the CLARITY Act. This outcome required a three-fifths majority, effectively blocking the bill’s immediate path to floor consideration. It is crucial to note that this was not a final vote on the bill’s merits, nor did it diminish the existing regulatory authority held by various agencies.
Approximately 46 minutes after the Senate’s decision, Kulechov took to the social media platform X (formerly Twitter) to articulate his vision. He argued that the DeFi industry should respond to legislative hurdles by focusing on building products that resonate with millions of users, thereby becoming "too important to ignore." He aptly described this strategic approach as "The Uber path." This analogy signifies a deliberate strategy to build political leverage through widespread adoption, rather than implying that popularity alone can dictate legal frameworks.
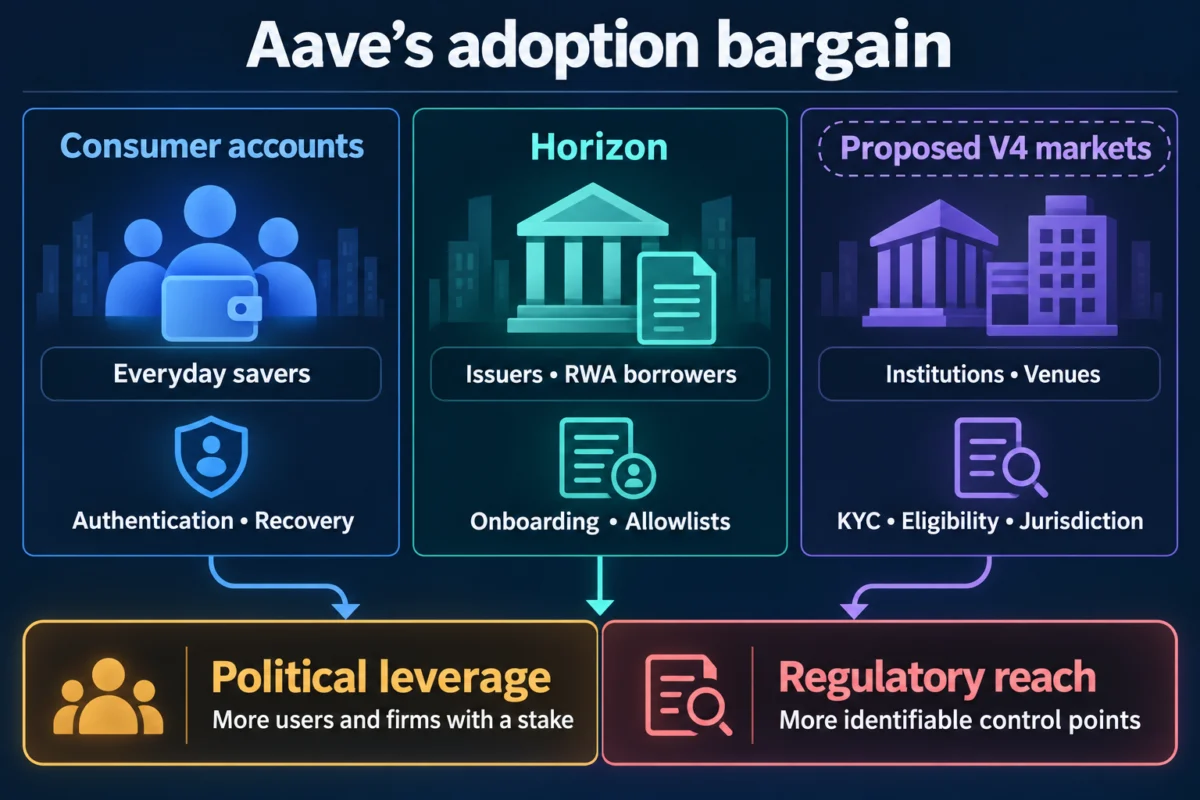
Aave’s own evolving product roadmap underscores the critical distinction Kulechov highlighted. The company is actively developing initiatives aimed at broadening DeFi’s appeal, including user-friendly consumer accounts, institutional lending solutions that utilize tokenized real-world assets as collateral, and a proposed architectural framework for securities finance. These endeavors are designed to expand the number of individuals and firms with a vested interest in the DeFi ecosystem. However, each of these growth avenues also necessitates the integration of specific functions into identifiable corporate entities, issuers, service providers, and permissioned venues. This integration, while crucial for mainstream adoption, also creates identifiable points of contact for regulatory oversight.
Aave’s strategic direction suggests a potential pathway to make DeFi more difficult for Washington policymakers to dismiss. Concurrently, the introduction of regulated interfaces within its ecosystem could also inadvertently make the system more accessible to regulatory scrutiny.
The Consumer Path: Building a Service Layer for Mass Adoption
Aave Labs is actively working to transform the experience of engaging with on-chain financial activities, aiming to make it feel less like navigating a complex cryptocurrency wallet and more akin to using a familiar modern financial application. Their innovative account design allows users to sign in using conventional methods such as an email address or phone number, coupled with a password, and offers optional passkey integration for enhanced security. These "smart accounts" possess advanced functionalities, including the ability for Aave to sponsor transaction gas fees, batch multiple transactions into a single operation, and enable users to pre-authorize specific withdrawal destinations, thereby enhancing security and user experience.
The recovery mechanism for these accounts serves as a clear illustration of the inherent trade-offs involved in building user-friendly interfaces. Aave asserts that its application maintains self-custodial principles, meaning users retain ultimate control over their assets. However, the convenience of features like account recovery is contingent upon an underlying infrastructure that extends beyond the core DeFi protocol itself. In the event a user forgets their password or loses access to their primary authentication device, a password- and authentication-encrypted signer is stored on Aave’s backend servers. If a user still possesses a previously authenticated device, they can regain access from that device. For scenarios involving the loss of all authorized devices, a more intricate recovery process is in place. Encrypted private key material is divided and entrusted to two separate entities: CoinCover, a digital asset recovery specialist, and Aave. Upon successful biometric verification and a one-time password check, these two services collaboratively release the necessary components to reconstruct the user’s access.
It is important to clarify that this arrangement does not grant Aave Labs the unilateral ability to reconstruct a user’s private key, seize assets, or reverse blockchain transactions. Aave’s publicly available app disclosures explicitly state that users remain in control of their assets and issue a stern warning: the permanent loss of all credentials and recovery options can result in an irretrievable lockout from the account.
Despite the self-custodial claims, the product possesses an operational perimeter. The smart account design grants Aave Labs limited permission to move incoming stablecoin deposits into a designated vault, thereby enabling them to begin earning yield without requiring further user intervention. The integration of email and phone number authentication, the backend storage of encrypted data, the CoinCover recovery process, and the implementation of withdrawal allowlists all represent identifiable services. These components are instrumental in making the product appealing to a mainstream customer base, and crucially, they offer a more tangible presence for policymakers to observe compared to the abstract nature of smart contract code.
A critical distinction must be maintained between the corporate and protocol layers of Aave’s operations. Aave Labs’ terms of service clearly delineate the Aave Protocol as an open-source, self-executing infrastructure that the company does not own, operate, or control. Aave Labs’ role is confined to developing software, user interfaces, and ancillary services that interact with this underlying infrastructure. Meanwhile, the governance of the Aave DAO and the integration of third-party solutions operate within their own distinct spheres of influence. This separation of responsibilities intentionally limits the extent to which control can be definitively attributed to any single entity. However, it does not render all layers of the ecosystem equally inaccessible to regulatory inquiry.
Horizon: Expanding the Coalition and Defining Gatekeepers
Aave’s initiative, branded as Horizon, applies a similar strategic tension to the institutional sector. This market allows eligible borrowers to leverage tokenized securities or other verified real-world assets (RWAs) as collateral to secure stablecoin loans. The published architecture of Horizon is designed to pool stablecoin liquidity while maintaining compliance protocols that are specific to each type of collateral asset.
The stablecoin provisioning side of the market remains largely open, permitting virtually anyone to supply stablecoins. Similarly, any wallet holding an approved asset can interact with the lending contracts, provided it adheres to the market’s defined parameters. Conversely, the collateral side of the operation is intentionally structured with access controls. Asset issuers are responsible for onboarding and verifying investors, establishing eligibility criteria, and managing the wallet allowlists that dictate who is permitted to hold the tokenized collateral.
Other critical responsibilities are explicitly delineated. LlamaRisk, a risk assessment firm, conducts due diligence on assets and maintains or recommends key parameters such as loan-to-value ratios, liquidation thresholds, and supply or borrow caps. Chainlink provides essential on-chain validation of net-asset values, ensuring the accuracy of collateral valuations. The core lending logic is then executed through smart contracts.
This carefully allocated division of duties has the potential to facilitate the integration of asset managers, issuers, and qualified investors into the DeFi space without demanding that they abandon their existing compliance obligations. Furthermore, it could broaden the coalition of stakeholders who would actively resist policy measures aimed at excluding tokenized-asset lending from the United States market.
However, the expansion of the political constituency and the establishment of a regulatory perimeter appear to grow in tandem. The processes of issuer onboarding, Know Your Customer (KYC) decisions, the management of allowlists, price validation, and the definition of risk parameters are not merely abstract features of a decentralized network. Instead, they represent functions directly tied to identifiable actors within the ecosystem.
| Aave Initiative | Constituency it could widen | Controlled Function | Practical Point of Contact |
|---|---|---|---|
| Aave App Accounts | Everyday stablecoin savers | Authentication, recovery, and withdrawal allowlists | Aave Labs and recovery service providers |
| Horizon | Issuers and qualified RWA borrowers | Investor eligibility, asset allowlists, and risk settings | Issuers and risk-service providers |
| Proposed V4 Securities Finance | Brokers, lenders, and tokenized-asset venues | Venue rules, jurisdiction, and collateral eligibility | Permissioned venue operators |
Aave Labs’ research, published in June 2026, on rebuilding securities finance using its V4 architecture, delves even deeper into these structural considerations. It proposes a hub-and-spoke design for facilitating lending against tokenized securities, repurchase agreements (repos), and securities lending.
One proposed configuration involves a single, deep liquidity hub situated beneath multiple specialized spokes. Each spoke could manage its own distinct set of assets, risk parameters, and operational rules while drawing liquidity from the common pool. An alternative model suggests the use of several distinct hubs, each categorized by asset class and associated risk levels. This approach would allow for a Treasury market, for example, to remain structurally separate from a higher-risk equities market.
The Aave V4 proposal frames this architectural choice as a strategic trade-off. A single hub maximizes liquidity depth but necessitates that risk isolation be meticulously configured at the individual spoke level. Conversely, multiple hubs establish structural risk isolation but potentially fragment liquidity across different pools. The design also allows for spokes to connect to more than one hub, offering a degree of flexibility.
From a regulatory perspective, the most salient feature of these proposed structures resides at the periphery. A permissioned spoke or a jurisdiction-specific hub could be engineered to enforce KYC requirements, eligible-asset criteria, and location-based rules, all while leveraging shared liquidity from an underlying pool. It is important to emphasize that this represents a proposed market structure, not an assertion that Aave has already deployed a fully functional securities finance network. However, it clearly indicates that achieving institutional scale will not be accomplished by making regulated functions disappear. Instead, it involves translating those functions into configurable software parameters and clearly defined operator roles.
This approach could significantly enhance the efficiency of compliance processes. It could also make the identification of responsibility more straightforward for regulatory bodies.
CLARITY’s Failure Did Not Create a Legal Vacuum
The Senate’s vote on the CLARITY Act undoubtedly removed the bill’s immediate legislative path forward for digital-asset market structure. However, it did not remove interfaces, issuers, or intermediaries from the purview of existing laws. The relevant regulatory authority continues to follow the specific function or activity in question, regardless of the legislative stalemate.
The U.S. Securities and Exchange Commission (SEC) retains the authority to apply federal securities laws when an asset or arrangement meets the definition of a security. In April, SEC staff issued a conditional statement concerning certain self-custodial crypto interfaces. While this statement is non-binding and specifically addresses broker-dealer registration under Section 15 of the Exchange Act, its outlined conditions clearly articulate a policy stance: activities such as solicitation, order routing, fee structures, handling of defaults, and disclosure practices can have significant regulatory implications at the interface layer. A separate staff statement on tokenized securities further clarifies that the mere act of placing a security on a blockchain does not alter the fundamental analysis under existing securities laws.
The Commodity Futures Trading Commission (CFTC) operates within its own distinct regulatory domain. The CFTC asserts its continued enforcement authority over anti-fraud and anti-manipulation activities in spot digital-commodity markets, alongside its comprehensive regulatory and enforcement powers over derivatives. While this does not equate to general supervision over every spot lending product, it provides an established avenue for regulatory action when specific conduct or instruments fall within the agency’s jurisdiction.
The Financial Crimes Enforcement Network (FinCEN) also has established guidance relevant to this space. Its virtual-currency guidance is activity-based. The mere development of software does not automatically classify an individual or entity as a money transmitter. However, a business that utilizes or operates software to accept and transmit value may be subject to Bank Secrecy Act (BSA) obligations, depending on the specific facts and circumstances of its operations.
State laws introduce an additional layer of complexity. Licensing requirements vary significantly by jurisdiction and the specific activities undertaken. The Conference of State Bank Supervisors (CSBS) offers a model framework for modernizing money transmission rules. New York’s virtual-currency regulations, for instance, encompass activities such as transmission, custody, customer exchange, and the issuance or administration of virtual currency, while also providing for certain exemptions.
The existence of these existing regulatory frameworks does not automatically mean that Aave App, Horizon, or a future V4 venue will fall into every regulatory category. However, it underscores a critical point: the absence of the CLARITY Act does not simplify the regulatory analysis to solely examining protocol code.
Kulechov’s "Uber path" accurately describes a tangible political mechanism. A product that gains widespread adoption by millions of users cultivates a constituency of voters, customers, counterparties, and businesses. This broad base can then exert pressure on lawmakers to enact workable regulations rather than outright prohibitions. Institutional adoption further strengthens this coalition by incorporating issuers and established financial firms.
Aave’s strategic product development is exceptionally well-suited to test this proposition, as it actively targets both consumer savings and institutional collateral markets. If these products achieve significant scale, policymakers will undoubtedly face a broader spectrum of interests when deliberating on the future regulatory landscape for DeFi.
However, it is crucial to understand that adoption alone does not resolve fundamental legal questions. It does not determine whether a tokenized instrument constitutes a security, whether a derivative falls under CFTC jurisdiction, whether a specific service is transmitting value, or whether a state-issued license is required. These questions are intrinsically linked to the specific functions performed and the factual circumstances of each case.
Aave’s most user-friendly products are instrumental in making this regulatory reality more visible. Features such as robust recovery systems, intuitive corporate interfaces, carefully managed issuer allowlists, integrated risk management tools, and permissioned venues can enable DeFi to serve individuals and institutions who would likely not engage with a bare-bones protocol. Simultaneously, these components provide regulators with discernible points of interaction where disclosures, qualifications, controls, or registration requirements can be mandated, aligning with existing legal frameworks.
The likely outcome is not that Aave will become so integral to the financial system that it becomes "too important to regulate." Rather, Aave has the potential to become important enough to actively shape the contours of what regulation targets. While the core protocol may remain decentralized, the consumer and institutional layers of Aave’s offerings are poised to engage in a dynamic negotiation with Washington, as these are the very layers where widespread adoption, demonstrable responsibility, and effective political leverage converge.