admin
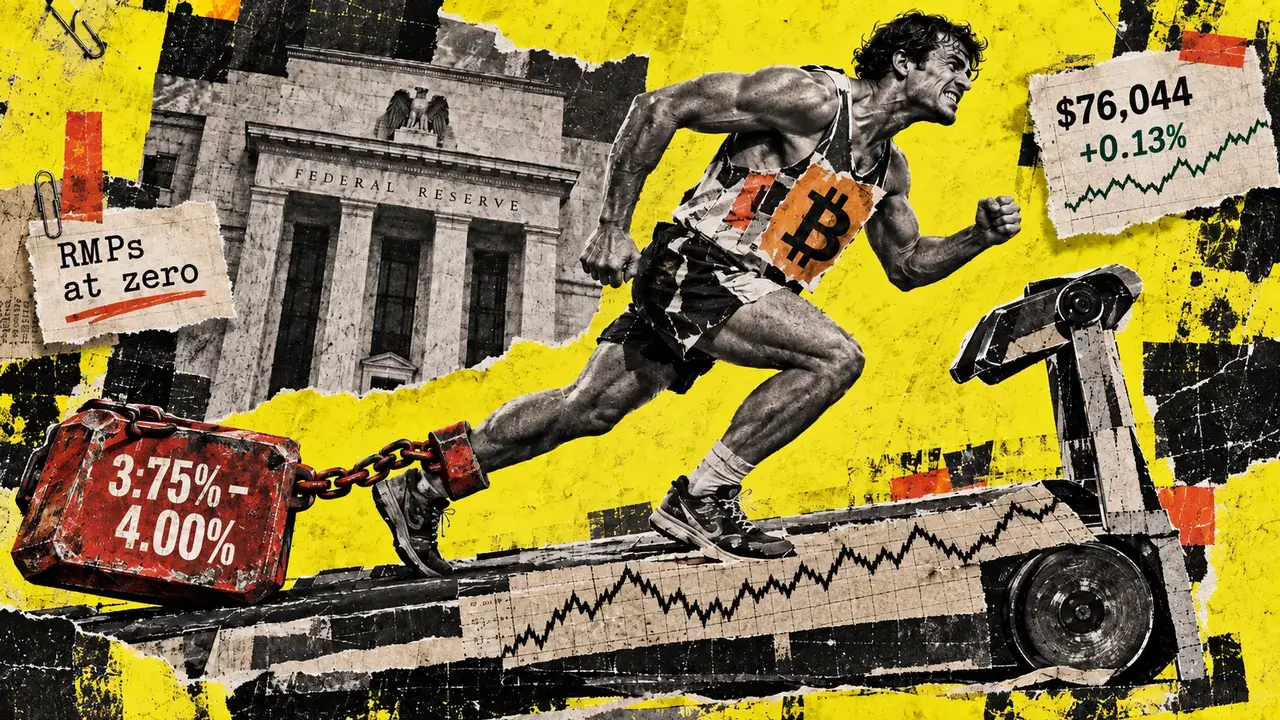
On September 16th, the Federal Reserve implemented a significant adjustment to its monetary policy by raising the federal-funds target range, a key lever for influencing short-term interest rates. Simultaneously, the central bank reaffirmed its commitment to an ample reserves framework, a strategy designed to maintain stability and control within the banking system. This dual approach signals a tightening of monetary conditions while preserving the operational infrastructure that underpins the Fed’s ability to manage overnight rates effectively. The Federal Open Market Committee (FOMC) voted to increase the federal-funds target range by a quarter of a percentage point, bringing it to a new level of 3.75% to 4.00%. This move marks a continuation of the Fed’s efforts to curb inflationary pressures that have been a persistent concern for policymakers.
Accompanying this adjustment to the target range was a directive that set the interest rate paid on reserve balances to 3.90%, effective September 17th. This administered rate is a critical component of the ample reserves framework, ensuring that banks have sufficient incentives to hold reserves at the Fed, thereby anchoring the federal-funds rate within the target range. Furthermore, the directive maintained the Federal Reserve Bank of New York’s trading desk’s conditional authority to engage in open market operations. This authority allows the desk to purchase Treasury bills, and if necessary, other Treasury securities with maturities of no more than three years, with the primary objective of maintaining ample reserves in the financial system. This reserve management, distinct from broader asset purchase programs, is designed to fine-tune liquidity conditions without fundamentally altering the overall monetary policy stance.
The distinction between these two policy tools – the administered rate adjustments and the reserve management operations – is crucial for understanding the Fed’s current strategy. The increase in the administered rate directly transmits the tighter monetary policy stance to the broader financial markets. It signals to banks and other financial institutions that the cost of borrowing overnight has increased, which in turn influences lending rates and other financial conditions. Concurrently, the reserve management authority acts as the operational backbone, ensuring that the banking system has sufficient liquidity to function smoothly and that the Fed can effectively implement its desired short-term interest rate. The impact of these policies on assets like Bitcoin, which are sensitive to liquidity conditions and risk appetite, hinges on how these Fed actions propagate through financial markets, irrespective of the sheer size of the Federal Reserve’s balance sheet.
Understanding Reserve Management Operations vs. Quantitative Easing
To fully grasp the implications of the Fed’s recent actions, it is essential to differentiate between quantitative easing (QE) and reserve management purchases (RMPs). Quantitative easing is a monetary policy tool employed to ease financial conditions and stimulate the economy, particularly during periods of economic distress or when traditional interest rate cuts are no longer effective. QE typically involves large-scale purchases of longer-term Treasury securities and agency mortgage-backed securities. The primary objectives of these purchases are to remove duration risk from private portfolios, thereby lowering longer-term interest rates, and to inject liquidity into the financial system, encouraging investment and economic activity. By absorbing these assets from the market, the Fed aims to reduce the supply of these securities available to private investors, pushing their prices up and their yields down. This process effectively loosens broader financial conditions, making it cheaper for businesses and individuals to borrow money.
Reserve management purchases, on the other hand, serve a more narrowly defined purpose. RMPs are designed to add reserves to the banking system through the acquisition of short-dated Treasury securities, primarily Treasury bills. This is done to ensure that the Federal Reserve can implement its chosen short-term interest rate target effectively, even as currency in circulation, Treasury balances at the Fed, and other liabilities fluctuate. The ample reserves framework, which RMPs support, ensures that banks have ample liquidity, thereby preventing excessive volatility in the federal-funds rate and maintaining orderly functioning of money markets.
This fundamental difference was articulated by Federal Reserve Vice Chair Philip Jefferson in January 2026. He characterized QE as a stimulus tool aimed at removing duration risk and easing financial conditions, while describing RMPs as an instrument specifically for maintaining ample reserves and ensuring effective short-rate control. Roberto Perli, a markets chief at the New York Fed, further elaborated on this distinction, noting that reserve management purchases in 2026 had exclusively involved Treasury bills, contrasting them with the longer-duration asset purchases utilized during periods of monetary easing.
This division of labor allows the Federal Reserve to tighten its monetary policy stance – as indicated by rising interest rates – while simultaneously managing the size and composition of its balance sheet. The direction of the Fed’s balance sheet, reflecting changes in its assets and liabilities, provides insights into its operations. However, the true meaning of these changes for monetary policy is determined by the purpose, maturity, and transmission mechanisms of the underlying asset purchases.
The September directive continued the RMP framework that was initiated in December 2025. The New York Fed has stated that the monthly amount of RMPs is not set on a predetermined path, offering flexibility in its implementation. The published operational schedule for the period of September 15th to October 14th indicated zero net RMPs. However, this schedule did include approximately $15.6 billion in Treasury bill purchases funded by principal payments from agency securities. These reinvestments represent a flow of funds that is separate from net RMP buying, highlighting the nuances of balance sheet accounting.
Crucially, the trading desk retains the capacity to increase its holdings of short-dated Treasuries when deemed necessary to maintain ample reserves. The fact that the published schedule showed this capacity currently unused for net RMPs suggests a deliberate approach to reserve management, limiting immediate claims of a significant new injection of reserves into the system.
The accounting for these operations requires careful consideration, as evidenced by earlier purchase totals. The Federal Reserve’s Monetary Policy Report, covering the period up to July 1st, indicated that the System Open Market Account had purchased nearly $250 billion of Treasury bills since the beginning of January 2026. Of this total, approximately $160 billion were attributed to RMPs, and $90 billion stemmed from agency-security reinvestments. During this comparative period, the Fed’s total assets saw an increase of $151 billion, while reserve balances grew by $54 billion, influenced by various other balance sheet movements.
More recently, the H.4.1 release, a weekly report detailing the Fed’s balance sheet, showed total assets at $6.740619 trillion as of September 9th. This represented an increase of $3.415 billion from the preceding week and $134.657 billion from a year prior. These figures provide a snapshot of the overall size and trajectory of the balance sheet. However, classifying these changes as QE depends more on the announced purpose and the specific composition of the assets being purchased rather than just the absolute increase in asset holdings.
Market Reactions and Implications for Bitcoin
The Bitcoin market, a closely watched indicator of liquidity and risk appetite, reacted to the Federal Reserve’s policy announcement. The quarter-point rate hike was absorbed by the market, alongside the continued reinforcement of the ample reserves framework. This framework’s explicit intention to support reserve supply and short-rate control, coupled with the upward adjustment in the target rate and the interest paid on reserve balances, signaled a clear shift towards tighter monetary conditions.
Prior to the Fed’s decision, money market indicators suggested that the central bank was effectively managing overnight rates. On September 15th, the secured overnight financing rate stood at 3.64%, and the effective federal-funds rate was 3.63%. These figures were notably close to the prevailing interest rate on reserve balances of 3.65%, indicating a well-anchored federal-funds rate. The overnight reverse-repo facility, another tool used to manage liquidity, saw a take-up of approximately $0.7 billion, further underscoring the Fed’s control over short-term funding markets.
These funding market readings provide a crucial lens through which to classify the Fed’s reserve policy. They confirm that the ample reserves framework is functioning as intended, ensuring that the Fed can implement its policy rate effectively. The response of the cryptocurrency market, particularly Bitcoin, offers a contemporaneous context rather than direct evidence of transmission. Bitcoin was trading near $76,044, showing a modest 0.13% gain over the preceding 24 hours, according to data from CryptoSlate. Concurrently, Farside Investors reported net outflows of $450.4 million from U.S. spot Bitcoin exchange-traded funds on September 15th. Attributing these market movements directly and causally to the Federal Reserve’s policy decision remains challenging and unsupported by definitive evidence at this juncture.
Looking ahead, any future growth in the Federal Reserve’s balance sheet should be primarily assessed based on the announced purpose and design of the underlying programs. The decisive evidence for classifying such operations will stem from their stated objectives, the scale of purchases, and the maturity composition of the acquired assets. Furthermore, the New York Fed’s operational schedules, particularly whether they signal planned net reserve-management purchases, will be critical indicators. A program explicitly designed to ease policy by removing substantial duration risk from the market would be materially different from conditional purchases of short-dated bills aimed at maintaining ample reserves.
While the direct transmission of monetary policy to Bitcoin is complex, broader financial conditions undoubtedly influence its trajectory. A convincing case for a "liquidity pivot" – a scenario where the Fed shifts towards more accommodative policies – would typically involve easier longer-term financial conditions alongside increased demand for risk assets like Bitcoin. Bitcoin prices and ETF flows can offer insights into investor sentiment and capital allocation decisions. However, the ultimate classification of the Fed’s balance sheet operations as QE or something else will depend on the specific design and execution of its programs.
For the present, the policy package implemented on September 16th represents a tightening of monetary policy, executed within the framework of an ample reserves system. Applying the label of quantitative easing to these actions risks collapsing two distinct operational functions into a single balance sheet metric. This oversimplification may overstate the extent of the monetary stimulus, or indeed the easing of financial conditions, that the Federal Reserve has delivered to markets, including those for digital assets like Bitcoin. The Fed’s current strategy prioritizes precise control over short-term rates and maintaining financial stability, utilizing tools that are distinct from the large-scale asset purchases historically associated with quantitative easing.