admin
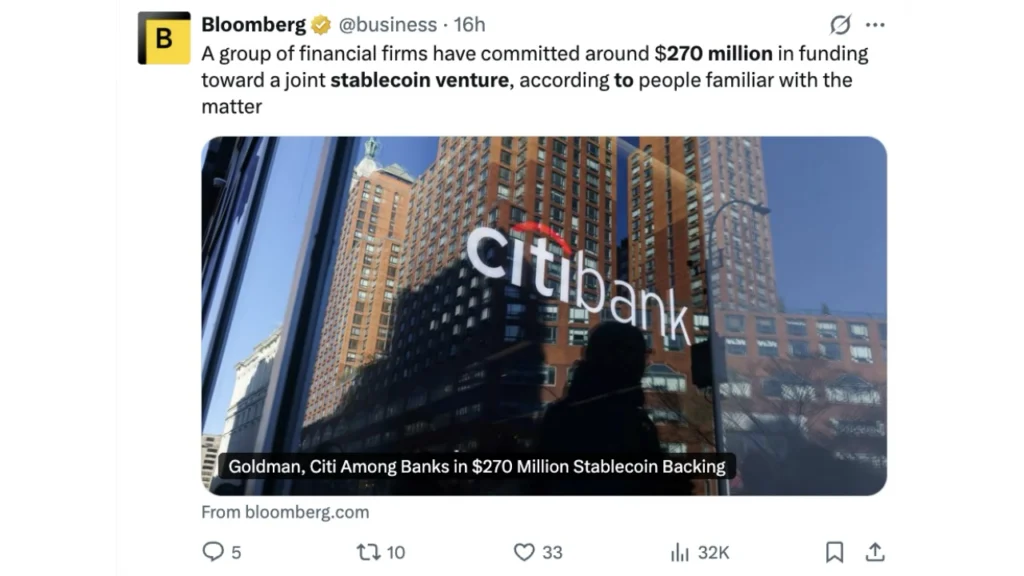
A formidable consortium of 21 global financial institutions, spearheaded by industry titans Goldman Sachs and Citigroup, has collectively committed approximately $270 million to Project Faro. This ambitious U.S.-incorporated venture aims to launch its proprietary dollar stablecoin in the first half of 2027, marking a pivotal shift in how traditional finance engages with digital currencies. The strategic intent behind this significant investment transcends mere participation in the burgeoning digital payments landscape; it represents a calculated maneuver by the world’s leading banks to assert control over critical financial infrastructure, secure lucrative revenue streams from reserve assets, dictate compliance frameworks, and ultimately position themselves at the heart of the rapidly emerging tokenized-asset markets. This move signals an end to passive observation and tentative experimentation, transitioning into a direct, collaborative effort by Wall Street to build its own digital monetary rails.
The Genesis of Project Faro: A Strategic Imperative for Traditional Finance
The journey towards bank-backed digital currencies has been a gradual yet inevitable one, driven by the accelerating digitalization of finance and the disruptive rise of crypto-native stablecoins. For years, financial institutions grappled with the implications of cryptocurrencies, often viewing them with skepticism. However, the consistent growth and utility of stablecoins like Tether’s USDT and Circle’s USDC, which collectively command roughly 85% of a market valued at approximately $290 billion, presented a stark reality: digital dollars were gaining traction outside the traditional banking system. USDT alone accounts for nearly $176 billion, with USDC close to $70 billion, demonstrating robust liquidity and widespread integration across major blockchains. This ecosystem, while efficient, presented a critical challenge to banks: it siphoned off potential revenue and control.
Recognizing this evolving landscape, major banks began exploring their options. Initial discussions around what would become Project Faro reportedly commenced as early as October 2025, involving a smaller group of ten institutions, including BNP Paribas. The expansion to 21 members, including global powerhouses like Banco Santander, Deutsche Bank, Wells Fargo, Fidelity, MUFG, Standard Bank, and BBVA, underscores the broad industry consensus on the strategic necessity of this initiative. The $270 million commitment is earmarked to cover the new company’s operating costs for its initial five years, providing a substantial runway for development, regulatory navigation, and market penetration. The decision to incorporate in the United States highlights a focus on operating within a well-defined, albeit evolving, regulatory perimeter, aiming for legitimacy and trust from the outset.
Beyond the Dollar: A Vision for Global Digital Currencies
While the immediate focus of Project Faro is the launch of a U.S. dollar stablecoin, the consortium’s ambitions extend far beyond a single currency. The venture plans to issue stablecoins pegged to every G7 currency, with a euro coin next in line. This multi-currency strategy is a clear indication of the banks’ intent to establish a global digital cash utility that can facilitate seamless cross-border payments and settlements across major economic blocs. Such a framework would directly address the inefficiencies and high costs associated with traditional international transactions, offering a faster, more transparent, and potentially cheaper alternative.
The development of G7-pegged stablecoins could have profound implications for international trade, foreign exchange markets, and the broader global financial architecture. By offering a standardized, compliant digital representation of major reserve currencies, Project Faro aims to create an interoperable system that could streamline global commerce, reduce settlement risks, and foster greater financial inclusion by making cross-border transactions more accessible and efficient. This vision positions Faro not merely as a stablecoin issuer but as a potential architect of a new global monetary infrastructure, built on the foundations of existing financial powerhouses.
The Control Premium: Why Banks Shun Existing Stablecoins
A fundamental question arises: why embark on such a complex and costly endeavor when highly liquid and battle-tested stablecoins like USDC and USDT already exist? The answer lies in the core tenets of banking: revenue, control, and compliance.

- Yield on Reserves: At the heart of the banking business model is the management of deposits and the generation of yield from those assets. Stablecoin issuers, such as Circle (USDC) and Tether (USDT), earn the interest on the reserves backing their tokens, typically held in cash and short-term U.S. Treasuries. In an environment of rising interest rates, this yield represents a significant revenue stream. Every dollar a corporate client parks in USDC is a dollar whose float accrues to Circle, not to the bank that maintains the client relationship. For institutions fundamentally built on deposits and interest income, this represents a "slow leak" of capital and profit that they can ill afford to ignore. By issuing their own stablecoin, the Faro consortium ensures that this yield remains within the traditional banking ecosystem, bolstering their collective bottom line.
- Regulatory Compliance and Autonomy: The current stablecoin market operates with varying degrees of regulatory oversight. While some issuers, like Circle, have made strides in adhering to financial regulations, the banks in Project Faro desire direct control over the compliance framework. A bank-owned issuer allows members to write their own rules regarding Know Your Customer (KYC), Anti-Money Laundering (AML) checks, sanctions screening, and the handling of frozen funds. This autonomy is crucial for institutions operating under stringent regulatory mandates across multiple jurisdictions. The consortium has explicitly stated that its token is designed to comply with the U.S. GENIUS Act (Generating Innovative New User-friendly Stablecoins Act) and, where relevant, the European Union’s Markets in Crypto-Assets (MiCA) regime. This proactive alignment with established and emerging regulatory perimeters provides a level of certainty and comfort that existing crypto-native stablecoins, despite their efforts, may not fully offer to risk-averse financial institutions. MiCA, for instance, provides a comprehensive regulatory framework for crypto-assets, including stablecoins, within the EU, setting precedents that global players must consider.
- Trust and Brand Reputation: For banks, trust is paramount. By issuing their own stablecoin under the aegis of a consortium of reputable financial institutions, they aim to leverage their established brand credibility and regulatory standing to foster greater confidence among institutional and retail clients. This "trusted issuer" model could be a significant differentiator, especially for entities wary of the perceived risks associated with purely crypto-native firms.
The Real Prize: Reshaping the Architecture of Tokenized Assets
While payments represent an immediate application, Project Faro’s true strategic prize lies in its potential to become the foundational "cash leg" for the rapidly expanding market of tokenized assets. The consortium’s September announcement explicitly highlighted cross-border payments and digital asset settlement as core use cases, signaling their foresight into the future of finance.
- Real-World Asset (RWA) Tokenization: The tokenization of real-world assets (RWAs) is poised to revolutionize capital markets. Assets such as bonds, money market funds, real estate, commodities, and private equity are increasingly being digitized and moved onto blockchain networks. This process promises enhanced liquidity, fractional ownership, reduced settlement times, and greater transparency. Financial institutions like BlackRock, through initiatives such as their BUIDL fund, are actively exploring and investing in RWA tokenization, with projections suggesting the market could reach trillions of dollars in the coming years.
- On-Chain Settlement and the "Cash Leg": Every tokenized trade, whether it’s a digital bond or a tokenized share, requires an on-chain cash equivalent to settle against. Whoever issues that cash token effectively controls the "plumbing" of these new markets. They sit at the center, seeing the flows, dictating the rules of settlement, and capturing valuable data. Banks, which currently dominate traditional custody, clearing, and correspondent banking services, have a vested interest in ensuring they retain this central role in the digital future. Handing this critical infrastructure over to a crypto-native firm would mean ceding immense strategic advantage and potential revenue streams. Project Faro aims to be that neutral, bank-backed cash token, ensuring that the control of settlement rails remains firmly within the traditional finance ecosystem.
- Industry Utility vs. Proprietary Product: A significant challenge in the early days of institutional digital assets has been interoperability. A digital token minted by a single bank often remains confined within that bank’s internal systems or client network, limiting its broader utility. A neutral stablecoin backed by a consortium of 21 institutions spanning North America, Europe, East Asia, the Middle East, and Africa has a far greater chance of becoming common settlement money between them. This collaborative model transforms the stablecoin from a proprietary product of one bank into an industry utility, capable of facilitating widespread, seamless settlement across a diverse array of financial players and geographical regions. This utility function is critical for achieving the network effects necessary for widespread adoption in institutional markets.
A Crowded and Evolving Landscape: Other Players in the Digital Cash Race
Project Faro is not operating in a vacuum. The race to define the future of digital cash is crowded and dynamic, with multiple initiatives emerging globally.
- Open USD and Qivalis: In June, over 140 companies, including payments giants Stripe, Visa, and Mastercard, alongside asset manager BlackRock, publicly backed Open USD, another business-focused dollar stablecoin initiative. Concurrently, in Europe, the Qivalis banking consortium has expanded to 37 members and, in October, secured authorization as an electronic money institution from the Dutch central bank, preparing for its own euro token launch.
- Overlapping Memberships and "Buying Options": A striking feature of this landscape is the significant overlap in memberships. BBVA, for instance, is a participant in Faro, Open USD, and Qivalis. Rabobank belongs to both Faro and Qivalis, and BNP Paribas, an early explorer of the Faro concept, later joined Qivalis. This phenomenon suggests that rather than committing to a single winner, major banks are strategically "buying options" on several versions of the future of digital cash. They are hedging their bets, participating in multiple initiatives to ensure they have a seat at the table regardless of which model ultimately prevails. This multi-pronged approach reflects the uncertainty and rapid evolution of the digital asset space.
- Solo Ventures and CBDCs: Beyond consortia, some institutions are pursuing independent paths. Fidelity has launched its own FIDD dollar token, while Societe Generale’s crypto arm already issues both euro and dollar stablecoins. These solo ventures underscore that the consortium model is one path among several being explored. Furthermore, central banks globally are actively researching and developing Central Bank Digital Currencies (CBDCs), which, while distinct from private stablecoins, contribute to the broader conversation around the digitalization of national currencies. The interplay between private stablecoins and potential CBDCs remains a key area of discussion and potential future integration.
Challenges and Opportunities on the Road to 2027
Despite the significant investment and powerful consortium behind Project Faro, the path to a successful launch in the first half of 2027 is fraught with challenges, yet ripe with opportunities.
- Distribution and Adoption: Faro’s strongest card is the unparalleled distribution network of its members, who collectively serve vast retail and corporate client bases worldwide. This inherent advantage means the token will not need to build an audience from scratch, unlike crypto-native issuers. However, the harder task will be converting these existing relationships into genuine on-chain activity. USDT and USDC have accumulated years of network effects, deep liquidity, and integration across numerous decentralized finance (DeFi) protocols and centralized exchanges. Faro will need to demonstrate superior utility, cost-effectiveness, and seamless integration with existing banking systems to entice clients to shift their digital asset flows. The user experience, ease of access, and interoperability with other digital asset platforms will be critical.
- Governance and Consensus: Managing a consortium of 21 major financial institutions, each with diverse home regulators, distinct strategic priorities, and often rival side bets in other initiatives, presents a formidable governance challenge. Reaching consensus on key decisions – such as the selection of a CEO, the public brand name, the choice of underlying blockchain technology, and the precise management of reserve assets – all within a launch window now less than a year away, will require exceptional leadership and diplomatic skill. Any significant disagreement could lead to delays or fragmentation.
- Regulatory Evolution: While Faro aims for compliance with the GENIUS Act and MiCA, the regulatory landscape for stablecoins is still evolving globally. New regulations or interpretations could emerge, requiring adjustments to the project’s structure or operational model. Navigating these complexities across multiple jurisdictions will be an ongoing task.
- Technological Infrastructure and Interoperability: Choosing the right blockchain technology, ensuring its scalability, security, and interoperability with existing banking systems and other digital asset platforms, will be crucial. The consortium will need to build robust infrastructure that can handle institutional-grade transaction volumes and security requirements.
Conclusion: The Shifting Center of Gravity
Project Faro represents a watershed moment in the intersection of traditional finance and digital assets. If successful, it has the potential to fundamentally shift the center of gravity in the stablecoin market, moving it away from crypto-native firms towards the established banking institutions that already underpin global finance. The $270 million investment is not merely a bet on a technology; it’s a strategic long-term play for control, revenue, and relevance in the digital economy.
Even if Faro encounters significant hurdles or only achieves partial success, the investment will have undoubtedly bought its members something invaluable: a guaranteed seat at the table while the foundational rails for tokenized money and future financial markets are being laid. Their active participation ensures that the architecture of tomorrow’s finance will be shaped, at least in part, by the institutions that have historically governed the flow of capital, rather than being solely dictated by emerging fintech or crypto-native entities. The world watches as Wall Street’s titans embark on this ambitious journey to build their own digital dollars, signaling a new era where traditional finance seeks to reclaim its central role in the decentralized future.