
 admin
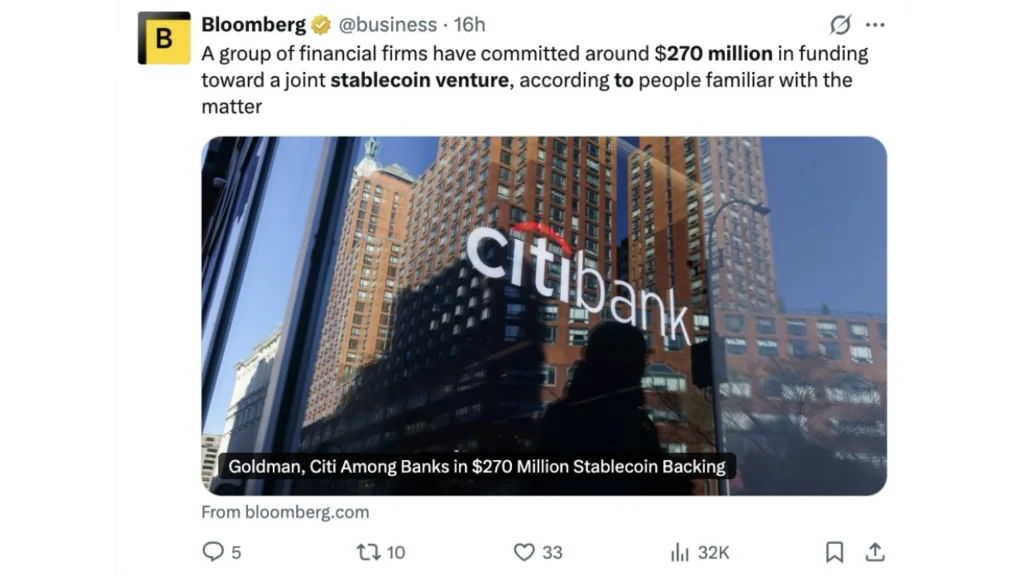
A powerful consortium of 21 leading global financial institutions, spearheaded by industry titans Goldman Sachs and Citigroup, has committed an estimated $270 million to Project Faro, an ambitious U.S.-incorporated issuer poised to launch its own U.S. dollar-pegged stablecoin in the first half of 2027. This significant investment signals a profound shift in Wall Street’s engagement with digital currencies, moving beyond mere experimentation to actively shape the infrastructure of future finance. The strategic impetus behind this venture is less about merely facilitating payments and more about securing control: by issuing their own digital tokens, these banks aim to retain the substantial revenue generated from reserve assets, establish their own comprehensive compliance frameworks, and, critically, stake a foundational claim to the indispensable "cash leg" of the rapidly emerging tokenized-asset markets.
A Bold New Chapter: Wall Street Funds Its Own Digital Dollar
The announcement, initially reported by Bloomberg based on insights from sources familiar with the matter, underscores a decisive turn for traditional finance. After years of observing and cautiously exploring the burgeoning cryptocurrency landscape, a formidable group of financial heavyweights has now pooled resources to create a bespoke digital currency solution. The $270 million capital injection into Project Faro is earmarked to cover five years of operational expenses for the newly formed entity, which will be strategically incorporated in the United States, emphasizing a commitment to operating within established regulatory perimeters. Beyond Goldman Sachs and Citigroup, the impressive roster of participating institutions includes prominent names such as Banco Santander, Deutsche Bank, Wells Fargo, Fidelity, MUFG (Mitsubishi UFJ Financial Group), Standard Bank, and BBVA. When the initiative first publicly surfaced in September, the group also counted Bank of America and UBS among its initial explorers, though the current composition reflects a refined alignment of strategic interests.
This U.S. dollar stablecoin is envisioned as just the initial foray. Project Faro harbors broader aspirations to issue stablecoins pegged to every G7 currency, with a euro-pegged token next on its developmental roadmap, indicating a global ambition to underpin cross-border digital transactions. Despite the substantial investment and clear strategic direction, the venture is still in its formative stages, actively searching for a chief executive officer to steer its course, and has yet to settle on a public-facing brand name. The specific contribution breakdown from each member institution remains undisclosed, and the banks involved have, to date, not issued official statements in response to media inquiries, maintaining a tightly controlled narrative as the project progresses.
The Strategic Imperative: Why Banks Are Building Their Own Stablecoin
The fundamental question arises: in a market already dominated by established stablecoins like Tether’s USDT and Circle’s USDC, why would a consortium of global banks commit such significant capital and effort to create a new one? On the surface, existing stablecoins, which collectively represent approximately 85% of a roughly $290 billion market (according to DefiLlama data, with USDT at nearly $176 billion and USDC at around $70 billion), offer liquidity, robustness, and broad blockchain compatibility. However, for banks, the calculus extends far beyond mere functionality.
The primary "catch" lies in the economic model: who accrues the yield on the reserves backing these tokens? Stablecoin issuers typically invest the collateral—often cash and short-term U.S. Treasuries—and earn the interest. This yield, known as "seigniorage," represents a significant revenue stream. Every dollar a corporate client parks in USDC, for example, generates float that accrues to Circle, not to the bank that manages the client relationship. For financial institutions fundamentally built upon deposit-based models, this outflow of potential revenue represents a "slow leak" that, over time, becomes unsustainable and strategically unacceptable. By issuing their own stablecoin, the Faro consortium directly reclaims this crucial revenue stream, ensuring that the economic benefits of digital dollar liquidity remain within the traditional banking ecosystem.
Beyond revenue, the issue of control is equally paramount. A bank-owned stablecoin issuer provides its members with the autonomy to define and enforce their own rules regarding compliance, customer due diligence (KYC/AML), and the handling of frozen funds. This eliminates dependence on a third-party’s policies, which may not always align perfectly with the banks’ existing risk frameworks or regulatory obligations. The consortium explicitly states its token is being designed to comply with the U.S. GENIUS Act (a hypothetical or placeholder reference, likely implying robust U.S. federal regulatory standards for stablecoins) and, where applicable, the European Union’s comprehensive Markets in Crypto-Assets (MiCA) regime. This proactive alignment with familiar regulatory perimeters is a critical factor for bank risk committees, offering a level of comfort and predictability that crypto-native stablecoins often struggle to provide within traditional finance.
The Real Prize: Settlement Rails for Tokenized Assets
While cross-border payments are a stated core use case for Faro’s stablecoin, the consortium’s ambitions extend far deeper into the future of finance: establishing the foundational settlement rails for tokenized assets. The group’s September announcement highlighted "digital asset settlement" as a pivotal application, signaling a long-term vision that transcends conventional payment systems.
The tokenization of real-world assets (RWAs)—such as bonds, money market funds, real estate, and other traditionally illiquid assets—onto blockchain networks is gaining significant momentum. Industry projections suggest the market for tokenized securities could reach trillions of dollars within the next decade. As these assets migrate onto distributed ledgers, every tokenized trade will necessitate an "on-chain cash leg" for instantaneous and immutable settlement. The entity that issues and controls this on-chain cash token will effectively sit at the very center of this new financial plumbing, gaining unparalleled visibility into transaction flows and wielding significant influence over how settlement mechanisms are designed and executed. Banks, which have historically dominated critical functions like custody, clearing, and correspondent banking in traditional markets, have little appetite to cede this central role to nascent crypto-native firms in the emerging tokenized economy. Project Faro represents their collective effort to maintain this strategic dominance.
Furthermore, a shared, industry-backed issuer like Faro addresses a significant coordination problem inherent in individual bank-issued tokens. A stablecoin minted by a single bank often remains largely confined within that bank’s internal ecosystem or its direct client network. A neutral, multi-bank-backed coin, supported by 21 institutions spanning diverse geographies including North America, Europe, East Asia, the Middle East, and Africa, possesses a far greater potential to achieve widespread adoption as common settlement money across the global financial system. This positions Faro not merely as another proprietary product, but as a critical industry utility, fostering interoperability and efficiency across a broad spectrum of financial participants.
Regulatory Landscape and Compliance: Navigating the New Frontier

The banking consortium’s emphasis on regulatory compliance is a cornerstone of Project Faro’s strategy. By designing their stablecoin to adhere to frameworks like the U.S. GENIUS Act (an anticipated or proposed regulatory framework for stablecoins) and the EU’s MiCA, the banks are proactively addressing one of the most significant hurdles for digital asset adoption within traditional finance: regulatory uncertainty. MiCA, in particular, provides a comprehensive regulatory regime for crypto-assets across the European Union, offering a clear path for compliant stablecoin issuance and operation. This approach aims to provide the necessary legal and operational clarity that will encourage institutional adoption and mitigate regulatory risks.
The involvement of major global banks in this initiative also suggests a collaborative dialogue with regulators. It indicates a preference for a supervised, regulated stablecoin environment, rather than the more decentralized and often less regulated landscape of existing crypto stablecoins. This alignment could potentially smooth the path for regulatory approvals and foster greater trust among institutional investors who prioritize compliance and stability.
A Crowded, Yet Collaborative, Field: The Multi-Option Strategy
Project Faro is by no means operating in a vacuum. The landscape for institutional digital dollars and euros is becoming increasingly dynamic and competitive. In June, for instance, a broad coalition of over 140 companies, including prominent players like Stripe, Visa, Mastercard, and BlackRock, coalesced behind Open USD, another business-focused dollar stablecoin initiative. Across the Atlantic, the Qivalis banking consortium in Europe has expanded to 37 members and, in October, secured authorization as an electronic money institution from the Dutch central bank, signaling its readiness for a planned euro token launch.
What is particularly intriguing is the significant overlap in membership across these various consortia. BBVA, for example, is a participant in Project Faro, Open USD, and Qivalis, demonstrating a multi-faceted approach to exploring the digital currency space. Similarly, Rabobank belongs to both Faro and Qivalis, while BNP Paribas, one of the ten banks that first explored the Faro concept in October 2025, subsequently joined Qivalis. This phenomenon suggests that rather than betting on a single winner in the race for institutional digital cash, major banks are strategically "buying options" on several versions of the future. This diversified strategy allows them to gain insights, influence development, and hedge their bets across different models and regulatory jurisdictions, ensuring they remain at the forefront of innovation regardless of which specific initiative ultimately gains critical mass.
Beyond consortia, some individual banks are also pursuing their own proprietary digital token initiatives. Fidelity, for instance, has launched its own FIDD dollar token, while Societe Generale’s dedicated crypto arm has already issued both euro and dollar stablecoins. This underscores that the consortium model, while powerful, is but one of several viable pathways for traditional financial institutions seeking to engage with and capitalize on the digital asset revolution.
The Broader Context: Digital Currencies and the Future of Money
Project Faro and similar initiatives are unfolding against a backdrop of intense global interest in the future of money, particularly concerning central bank digital currencies (CBDCs) and private stablecoins. While many central banks worldwide are exploring or piloting CBDCs, the development and deployment of such sovereign digital currencies often face complex policy, privacy, and technological hurdles, leading to slower progress. Private stablecoins, backed by high-quality reserve assets, offer a complementary or alternative path to digitizing national currencies, potentially leveraging existing financial infrastructure and private sector innovation.
The banks’ move into stablecoins can be seen as a strategic response to both the potential threat of CBDCs disintermediating traditional banks and the opportunity to provide a more efficient, compliant digital form of money that integrates seamlessly with their existing services. It represents an assertion by the private sector that it can, and will, play a central role in the evolution of digital cash, rather than ceding the entire field to central banks or purely crypto-native entities.
Critical Milestones Before 2027: Challenges and Opportunities
Before Project Faro’s targeted launch in the first half of 2027, several critical factors will determine its ultimate success.
Firstly, distribution is arguably Faro’s strongest inherent advantage. Its member banks collectively serve immense retail and corporate client bases globally. Unlike crypto issuers who had to painstakingly build audiences from scratch, Faro’s token will enter the market with immediate access to a vast existing network. The more challenging task, however, will be converting these established relationships into genuine, active on-chain activity. Existing stablecoins like USDT and USDC benefit from deep liquidity pools and years of entrenched network effects within the crypto ecosystem, posing a significant hurdle for a newcomer, even one backed by financial giants, to overcome in terms of organic usage.
Secondly, governance will be a formidable test. Coordinating 21 shareholders, each with potentially differing home regulators, unique strategic priorities, and even rival side bets in other digital currency initiatives, will require exceptional leadership and consensus-building. Key decisions—including the appointment of a CEO, the final brand identity, the choice of underlying blockchain technology, and the precise management of reserve assets—must all be meticulously agreed upon and executed within a launch window that is now less than a year away. The complexity of multilateral decision-making could significantly impact the project’s agility and speed to market.
If Project Faro successfully navigates these challenges, its impact could be transformative. The center of gravity for the global stablecoin market could undeniably shift, moving away from its current locus within crypto-native firms towards the traditional banks that have long governed global finance. This would represent a significant re-assertion of control by incumbent institutions over the digital future of money. Conversely, if the initiative stalls or fails to gain significant traction, the $270 million investment will still have provided its members with something invaluable: a privileged "seat at the table" during the crucial period when the foundational rails for tokenized money and a new digital financial infrastructure are being designed and laid. This early involvement ensures that traditional finance will have a voice, and a strategic position, in shaping the next evolution of global commerce and capital markets, regardless of the ultimate success of this particular venture.