admin
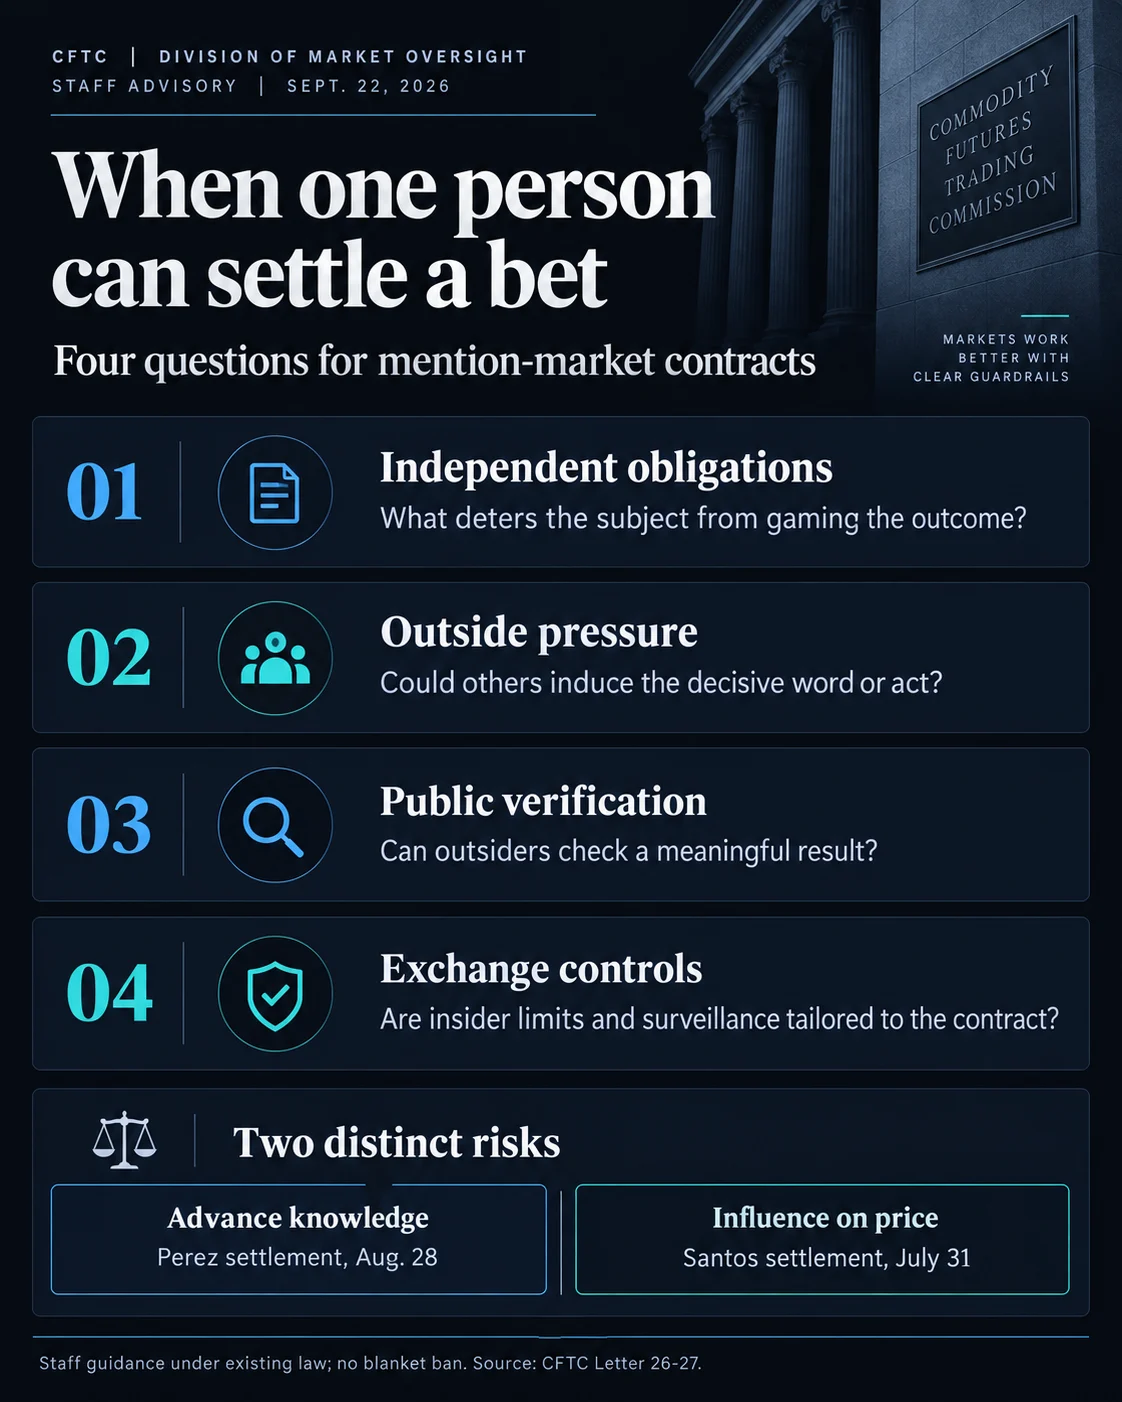
A clear video can settle whether a public figure said a particular word. It cannot show who knew the script beforehand or whether the speaker chose a word to affect a bet. That fundamental gap is at the center of a September 22 advisory on speech markets issued by staff at the Commodity Futures Trading Commission (CFTC). The advisory signals heightened scrutiny for prediction markets that center on the words, appearances, or interactions of named individuals, raising concerns about potential manipulation and the adequacy of existing safeguards.
The CFTC’s Division of Market Oversight articulated its concerns in an advisory that asks exchanges to provide detailed explanations of contract-specific safeguards. While this advisory represents a staff view and does not establish binding rules or outright prohibit such contracts, it clearly indicates a regulatory direction that could significantly impact the operation of prediction markets. The advisory suggests that contracts tied to a named person’s pronouncements or actions may be viewed as "presumptively readily susceptible to manipulation," a phrase directly drawn from the existing regulatory duty of exchanges to list contracts that are not easily manipulated. Exchanges are now tasked with demonstrating how they are equipped to manage the unique risks associated with these types of contracts.
Despite the advisory, exchanges like Kalshi continued to list speech markets the day following its release, suggesting a period of adjustment and interpretation will be necessary as the industry grapples with the CFTC staff’s guidance. The core of the issue lies in distinguishing between verifiable public statements and the potential for insider information or direct influence to skew market outcomes.
Exchanges Under Scrutiny: Demands for Enhanced Safeguards
The CFTC staff advisory outlines four non-exhaustive questions that exchanges must address regarding their speech-based prediction markets. These questions are designed to probe the robustness of the mechanisms in place to prevent manipulation:
- Independent Obligations of Outcome Determinants: Does the individual or entity responsible for determining the outcome of a contract face independent legal, professional, or other obligations that would deter them from gaming the system? This probes whether inherent ethical or professional duties provide a sufficient buffer against manipulation.
- Vulnerability to External Pressure: Could an individual or entity tasked with determining the outcome be pressured or induced by external parties to influence the contract’s resolution? This question addresses the risk of coercion or bribery.
- Verifiability Under Public Scrutiny: Can the outcome be verified under substantial public scrutiny, and does the decisive word or act hold any genuine significance within its relevant context? This focuses on the transparency and relevance of the event being bet upon.
- Adequacy of Exchange Controls: Are the exchange’s trading restrictions, surveillance systems, and other controls specifically suited to mitigate the particular risks associated with the contract? This is a critical question about the practical effectiveness of the exchange’s internal governance.
The advisory emphasizes that public proof of what transpired is only one piece of the puzzle. Staff guidance highlights that a speaker’s professional obligations, while important, cannot serve as a complete substitute for effective exchange-level controls. Exchanges are expected to provide detailed explanations of their measures and articulate how they identify individuals who control an outcome or possess privileged access to information.
Kalshi’s Speech Markets Under the Spotlight
A recent examination of Kalshi’s "mention markets" reveals the types of contracts now facing heightened scrutiny. These markets often involve bets on specific statements made by public figures, pronouncements during corporate events, or outcomes of significant public appearances. For instance, markets have covered Donald Trump’s remarks at state arrival ceremonies, Treasury Secretary Scott Bessent’s television interviews, and outcomes of corporate earnings calls, such as BlackBerry’s.
During checks conducted on September 23, three specific market pages showed varying levels of trading volume. A contract betting on whether Donald Trump would say the word "China" at least five times during an official capacity event had approximately $125,776 in volume. A market related to Treasury Secretary Scott Bessent’s television interview saw around $5,333 in volume, while a contract focused on BlackBerry’s next earnings call registered approximately $23,973 in volume. These figures are dynamic and change with ongoing trading activity.
The Trump contract, for example, stipulated that its outcome would be determined by live video or streams of a specific ceremony, with official transcripts serving as a fallback if consensus could not be reached from video evidence. Crucially, only speeches made by Trump in an official capacity were to be considered. The contract’s rules also explicitly barred employees of source agencies and individuals possessing material nonpublic information about the event from trading.
While these terms provide a clear framework for verifying what was said publicly and establish who should refrain from trading, they do not, in themselves, definitively explain how an exchange would detect, for example, a script holder trading through an alternative account or how it would identify and prevent pressure on a speaker to utter a specific, incidental word to influence market prices. The Bessent and BlackBerry listings further demonstrate that this regulatory concern extends beyond presidential remarks to encompass government interviews and corporate financial communications. The publicly visible listings alone do not offer a transparent view into how surveillance is tailored to the unique risks of each specific event.
Kalshi has stated that it implements a multi-layered approach to market integrity. This includes screening certain political figures and relevant government employees, restricting trading by individuals with inside information or influence over contract outcomes, and actively monitoring trading patterns. The exchange claims that accounts flagged for suspicious activity can be frozen, and cases can be referred to regulatory authorities. However, these are Kalshi’s self-reported controls, and the CFTC staff advisory implies a need for an independent assessment of their effectiveness in the context of these specific contracts.
A spokesperson for Kalshi, Elisabeth Diana, commented on September 23, stating, "We’ve addressed this guidance based on a prior discussion with the CFTC." She did not, however, specify any immediate changes made to the sampled markets in response to the advisory.

The Crucial Distinction: Knowing vs. Changing the Outcome
The CFTC’s enforcement actions provide concrete examples of the risks highlighted in the advisory. A settlement reached in August with Gabriel Perez serves as a stark illustration of the "advance information" problem. The CFTC’s order detailed how the White House teleprompter operator, by virtue of his access to presidential speeches prior to their delivery, used this privileged information to trade on mention contracts between December 2025 and February 2026, realizing profits of $107,539. It is important to note that the order did not allege that Perez altered the speeches; his advantage stemmed solely from possessing information that other traders did not have before the speeches were made public.
A separate settlement in July with former Rep. George Santos illuminated a different facet of manipulation risk. In that case, the CFTC found that Santos traded a contract related to his own attendance at the State of the Union address while simultaneously posting misleading statements about his intentions. This conduct demonstrably influenced market prices in his favor. The core issue here was the subject’s ability to control his attendance and, critically, to influence public perception and market expectations regarding his participation.
Neither of these settlements directly establishes misconduct in the three Kalshi contracts examined. However, they underscore the fundamental concerns guiding the CFTC staff’s advisory. For speech markets, the central question posed to exchanges is whether their verification processes, insider trading restrictions, and surveillance mechanisms are sufficiently robust to address both the individual who can directly influence or choose the outcome and those who may possess foreknowledge. Until such clarity is unequivocally demonstrated, market participants and regulators alike may view prices on optional or speculative words with a significant degree of caution, treating them as forecasts that carry inherent risks of being influenced by factors beyond verifiable public information.
Broader Implications for Prediction Markets
The CFTC staff’s advisory on speech markets represents a significant development in the regulatory landscape for prediction markets. By focusing on the specific vulnerabilities inherent in contracts tied to public figures, the agency is signaling a more granular approach to oversight. This could lead to increased compliance burdens for exchanges, requiring them to develop more sophisticated surveillance tools and to provide more detailed justifications for the safeguards they employ.
The distinction between verifiable information and insider knowledge is paramount. As prediction markets continue to evolve and offer contracts on an ever-wider array of real-world events, regulators are likely to maintain their focus on ensuring market integrity. The CFTC’s stance suggests that the onus is on exchanges to proactively demonstrate that their markets are not susceptible to manipulation, particularly when the underlying events involve individuals who may have direct or indirect influence over the outcomes.
The future of speech markets on these platforms will likely depend on the exchanges’ ability to satisfy the CFTC’s concerns through enhanced transparency and demonstrably effective risk-management strategies. Failure to do so could result in more stringent regulatory action, potentially limiting the scope or availability of such contracts. The advisory serves as a clear warning shot, urging the industry to prioritize robust controls and transparent operations in the face of potential manipulation risks.