Dwi Wanna
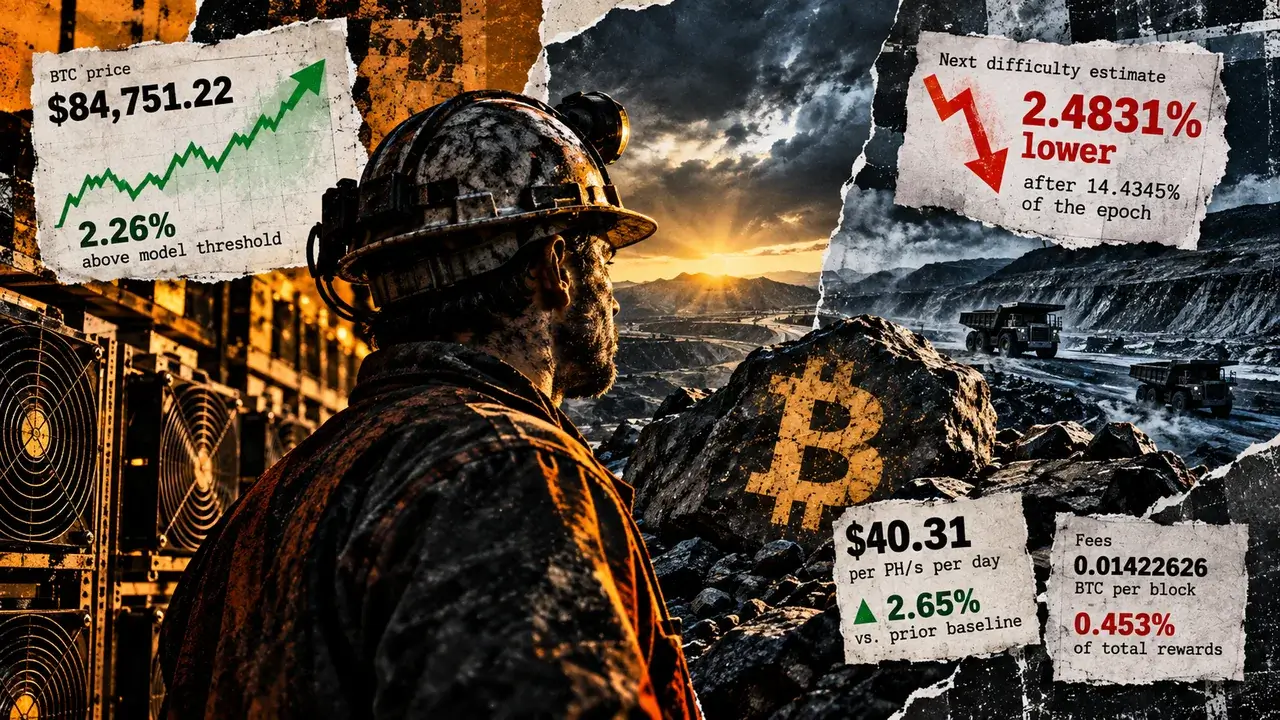
The Bitcoin mining sector experienced a measurable reprieve following the most recent network difficulty adjustment, as a significant price rally successfully neutralized the increased competitive pressure on the network. With Bitcoin trading at approximately $84,751, the theoretical gross hashprice—a primary metric for miner revenue—rose to $40.31 per petahash per second (PH/s) per day. This figure represents a 2.65% improvement over previous modeled baselines, suggesting that while the network is becoming more difficult to mine, the market value of the rewards is currently sufficient to keep pace with rising operational demands.
This development follows a period of heightened anxiety within the mining community, particularly as the network approached its September 19 retarget. Analysts had previously warned that without a corresponding increase in Bitcoin’s market price, the scheduled difficulty hike could trigger a margin squeeze, potentially forcing less efficient operators to shutter their hardware. However, the realized market conditions have provided a narrow but vital window of stability for the industry.
The Mechanics of the September 19 Difficulty Adjustment
Bitcoin’s difficulty adjustment is a fundamental component of its protocol, designed to ensure that blocks are discovered roughly every ten minutes. Every 2,016 blocks, or approximately every two weeks, the network evaluates the total computational power (hashrate) contributed by miners and adjusts the difficulty of the cryptographic puzzles accordingly. On September 19, at block 967,680, the network implemented an upward adjustment of 4.1634%. This moved the difficulty from 127.451 trillion to a new high of 132.757 trillion.
This increase reflects a growing influx of hashrate, likely driven by the deployment of next-generation application-specific integrated circuits (ASICs) and the expansion of industrial-scale mining facilities. While a higher difficulty signifies a more secure and robust network, it simultaneously raises the "cost of entry" for miners, as more computational work is required to earn the same 3.125 BTC block subsidy.
Prior to this adjustment, modeling from September 15 indicated that Bitcoin would need to reach a price of roughly $82,877 to maintain revenue neutrality for the average operator. By the time the difficulty had settled, the actual price had climbed to $84,751, approximately 2.26% above the required threshold. This price action was critical; it allowed the industry to absorb a 4.16% increase in competition while actually seeing a net improvement in the price-to-difficulty ratio of roughly 2.79%.
Analyzing Theoretical Gross Hashprice and Revenue Streams
The "hashprice" is the most comprehensive way to view the current state of mining economics. It combines the fixed block subsidy, the variable transaction fees, the current difficulty, and the market price of Bitcoin into a single daily revenue figure per unit of hashpower. At $40.31 per PH/s, the current hashprice offers a modest buffer, but it remains heavily dependent on the block subsidy rather than transaction fees.
Data from a 144-block sample (spanning blocks 967,828 through 967,971) reveals a concerning trend regarding the fee market. During this window, transaction fees contributed only 2.048 BTC to the total 452 BTC rewarded to miners. This equates to just 0.45% of total revenue. For miners, this highlights a continued reliance on "subsidy-heavy" income. In a post-halving environment, where the block subsidy has already been cut to 3.125 BTC, the lack of a robust fee market puts immense pressure on the market price of Bitcoin to remain high.
If transaction fees do not increase through higher network utilization—such as increased demand for Ordinals, Runes, or Layer-2 settlements—miners remain vulnerable to price volatility. The current $40.31 benchmark is a theoretical gross revenue figure and does not account for the wide variance in operational costs, including electricity contracts, debt servicing for hardware, and labor.
Early Signals for the October Retarget
As the network enters a new epoch, early data suggests a potential cooling of the hashrate. With approximately 14.43% of the current epoch complete, the network is producing blocks at an average pace of 10 minutes and 25 seconds—slower than the ten-minute target. If this pace continues, the next difficulty adjustment, estimated for October 3, could see a reduction of 2.48%.
However, industry experts caution against treating these early estimates as a definitive sign of miner capitulation or equipment shutdowns. Block discovery is a stochastic process; it is governed by probability rather than a steady mechanical output. Short-term fluctuations in block times are common and do not always correlate with a change in the physical amount of hardware connected to the network.
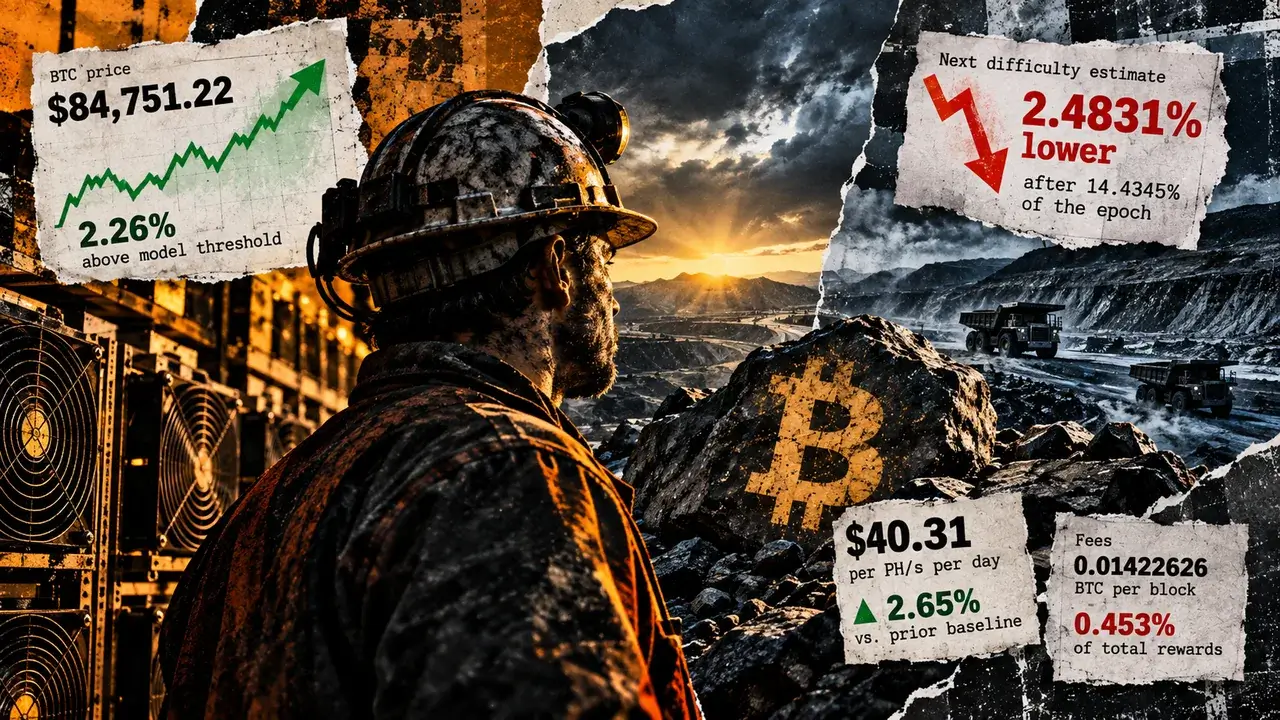
Research from the Hashrate Index and technical analysis by developers like Pieter Wuille suggest that early-epoch projections are "noisy" signals. A cluster of "slow blocks" can occur simply due to bad luck in the mining process, just as a cluster of "fast blocks" can occur when miners find solutions more quickly than the statistical average. Therefore, while a 2.48% decline is currently projected, it remains an unsettled metric that could easily reverse if block production accelerates in the coming days.
The Broader Impact on Mining Infrastructure and Strategy
The current economic landscape is forcing a divergence in strategy among the world’s largest mining firms. While the price rally has provided immediate relief, the long-term trend of rising difficulty is pushing many operators to diversify their revenue streams.
One of the most significant shifts in the industry is the pivot toward High-Performance Computing (HPC) and Artificial Intelligence (AI) infrastructure. Publicly traded miners such as Core Scientific, Hive Digital, and Bit Digital have begun reallocating portions of their power capacity and data center space to support AI workloads. These contracts often offer more stable, predictable revenue compared to the volatile nature of Bitcoin mining.
Recent reports suggest that Bitcoin miners have collectively amassed over $100 billion in potential AI-related infrastructure deals. While much of this revenue has yet to materialize on balance sheets, the shift indicates that the "arms race" for hashrate is no longer the only game in town. For those remaining purely focused on Bitcoin, the priority has shifted toward maximizing "joules per terahash" (J/TH) efficiency. Older machines, such as the Antminer S19 series, are increasingly being phased out in favor of the more efficient S21 and T21 models, which can maintain profitability at lower hashprices.
Timeline of Recent Economic Shifts
To understand the current reprieve, it is necessary to look at the chronology of the last several weeks:
- September 15: Bitcoin trades near $60,000. Models predict a significant difficulty hike, warning that a "margin trap" is forming unless the price reaches $82,000+.
- September 17-18: Market sentiment shifts as broader macroeconomic factors, including interest rate discussions, drive Bitcoin’s price upward.
- September 19: Difficulty increases by 4.16%. Bitcoin’s price continues its ascent, crossing the $80,000 mark.
- September 21-Present: Bitcoin stabilizes around $84,000. The theoretical hashprice reaches $40.31, providing the first real "breathing room" for miners since the April halving.
Implications for Market Stability
The current stability of the mining sector has broader implications for the Bitcoin market. When miners are profitable, they are under less pressure to sell their newly minted BTC to cover operational expenses. This reduction in "sell pressure" can create a virtuous cycle, allowing the price to find higher support levels.
Conversely, if the next difficulty adjustment were to increase significantly while the price stagnated, the industry could see a "shakeout." In such a scenario, smaller, less-capitalized miners might be forced to liquidate their holdings, creating temporary downward pressure on the price.
For now, the data suggests a period of "cautious optimism." The 2.65% improvement in gross revenue per unit of hashpower is a welcome development, but it is a narrow margin. The industry remains highly sensitive to even minor shifts in energy costs or regulatory changes.
Conclusion: A Fragile Equilibrium
The relief felt by Bitcoin miners in the wake of the September 19 retarget is real but remains contingent on several external factors. The rally to $84,751 has effectively "outrun" the difficulty increase for the time being, but the lack of transaction fee support means the floor is entirely dependent on market price.
As the industry looks toward the October 3 retarget, the focus will remain on whether the current block pace is a result of actual hashrate leaving the network or merely a statistical anomaly. Regardless of the outcome, the trend toward higher efficiency and diversified infrastructure continues to be the primary defense mechanism for an industry operating in an increasingly competitive global landscape. For the moment, the "miner margin squeeze" has been deferred, but the structural challenges of a post-halving world remain the dominant theme for 2024 and beyond.