admin
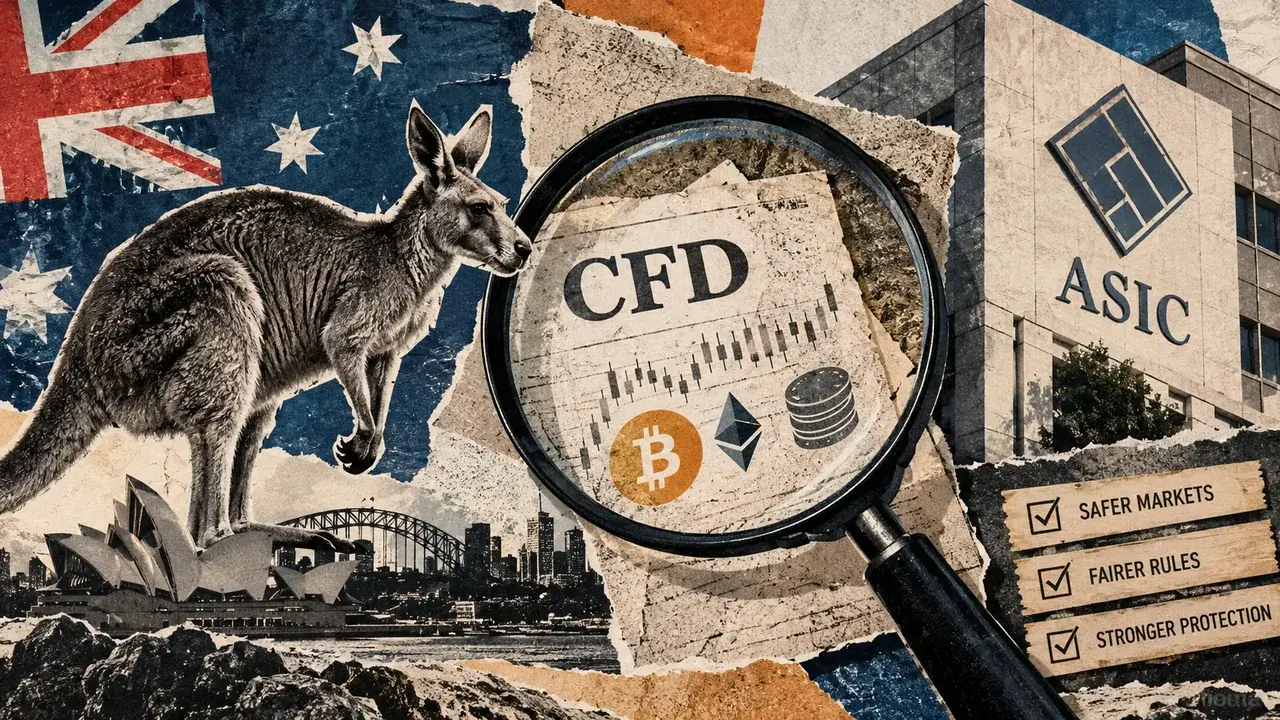
Australia’s financial markets regulator, the Australian Securities and Investments Commission (ASIC), is moving to significantly bolster consumer protections for retail investors trading leveraged financial products, proposing an extension of existing restrictions on contracts for difference (CFDs) to encompass qualifying derivatives settled through digital assets. This proactive measure, announced on October 12th, aims to close a burgeoning regulatory loophole that has allowed increasingly complex and risky products, particularly those tied to cryptocurrencies, to operate with less stringent oversight than their cash-settled counterparts, thereby exposing vulnerable retail investors to substantial and mounting losses.
The proposed expansion of the product intervention order, which currently governs CFDs, would bring a wider array of leveraged financial instruments under the purview of ASIC’s robust consumer protection framework. This includes leverage limits, standardized margin close-out arrangements, negative balance protections, and restrictions on promotional incentives. The move comes on the heels of ASIC’s stark findings regarding retail investor performance in the 2023-24 financial year, which revealed that a staggering 68% of retail CFD clients incurred losses, accumulating a collective deficit exceeding A$458 million (approximately $325 million). This figure includes a significant A$73 million attributed to fees, underscoring the pervasive financial drain on unsophisticated traders. While these figures encompass CFD trading across all asset classes, the growing prominence of crypto-linked derivatives has been a key driver for ASIC’s intervention.
ASIC’s proposed extension also seeks to prolong the life of these enhanced investor protections, aiming to keep them in force for an additional decade, until 2037, pending governmental approval. This long-term vision signals the regulator’s commitment to safeguarding retail participants in an evolving and increasingly complex financial landscape.
Targeting Leveraged Crypto Products and Margin Practices
Under the existing regulatory framework established by ASIC, CFDs are generally brought under control when their transactions are settled in cash or through the netting of offsetting obligations between parties. This has historically provided a clear line of demarcation. However, a significant development in financial product innovation has seen the emergence of derivatives with characteristics strikingly similar to CFDs, but which settle through the transfer of digital assets. This distinction has, in effect, allowed these crypto-settled derivatives to potentially sidestep the current product intervention order, creating a dual standard where economically analogous products face vastly different regulatory treatment.
ASIC’s proposed amendment seeks to decisively eliminate this disparity. By extending the definition of qualifying derivatives to include those settled digitally, regardless of the underlying asset – whether it be cryptocurrencies, traditional securities, interest rates, or market indices – the regulator intends to create a level playing field. This broadened scope will necessitate that brokers and derivatives platforms offering these digitally settled contracts adhere to the same stringent leverage restrictions, standardized margin close-out procedures, negative balance protections, and limitations on aggressive promotional offers that have been applied to cash-settled CFDs.
For CFDs directly referencing cryptocurrencies, the current maximum retail leverage is capped at a restrictive 2:1 ratio. This means that retail investors must provide at least 50% of the value of their leveraged positions as initial margin, significantly curtailing their capacity to magnify potential gains – and more importantly, potential losses. Other contracts are subject to varying leverage limits based on the underlying asset, with limits ranging from 5:1 for equities to a more permissive 30:1 for major currency pairs. The proposed expansion to crypto-settled derivatives will not automatically impose the 2:1 cryptocurrency leverage cap on all digitally settled products. Instead, the specific leverage limits will be determined by the nature of the derivative’s underlying exposure and its contractual structure, allowing for a nuanced approach that still ensures adequate protection. It is important to note that certain fixed-expiry crypto futures and options are expected to remain outside the scope of this particular intervention.
A History of Intervention and Investor Protection
The move to extend leverage restrictions is not unprecedented. ASIC’s initial product intervention order for CFDs, implemented in March 2021, was a significant step towards reining in the excesses observed in the leveraged trading market. Commissioner Alan Kirkland has previously emphasized the material reduction in investor harm achieved by these existing restrictions, particularly highlighting the impact of limiting excessive leverage. During the initial six months following the implementation of these protections, aggregate quarterly retail losses experienced a dramatic decline of 91%, plummeting from A$372 million to A$33 million. Furthermore, the regulator documented an 87% reduction in quarterly margin close-outs, a key indicator of reduced trading activity driven by margin calls. While subsequent reviews indicated that a majority of retail CFD investors continued to experience losses, the intervention demonstrably curbed the most egregious levels of risk-taking and subsequent financial devastation.
The current proposal also addresses critical issues surrounding margin calculation practices. ASIC’s sector-wide investigation identified instances where firms were reportedly offsetting customers’ opposing trading positions to artificially reduce collateral requirements. This practice, known as margin netting, effectively lowered the initial margin needed by traders, thereby increasing their leverage and potential for catastrophic losses. To counter this, the proposed clarification will mandate that brokers calculate the minimum margin separately for each individual CFD. This will prevent firms from utilizing one open position to offset the collateral required for another, ensuring that traders are adequately capitalized for each specific trade. ASIC’s previous intervention on margin netting practices alone resulted in 28 issuers refunding over A$36 million to affected retail customers, highlighting the significant financial implications of such practices.
Addressing Losses in Options-Linked Derivatives
A particular area of concern for ASIC is the performance of retail investors trading CFDs linked to options. The regulator’s data reveals that a substantial 85% of retail clients engaged in this specific type of trading incurred losses during the 2023-24 financial year. This alarming statistic has prompted ASIC to propose a dual approach: first, to clarify margin requirements for these products to ensure greater transparency and adequate risk management; and second, to critically examine whether certain options-linked derivatives should remain available to ordinary retail investors at all. ASIC is actively seeking evidence regarding contracts that could expose traders to losses exceeding the initial options premium, particularly those structures with the potential for unlimited downside exposure. The regulator has not yet made a definitive decision on whether these products warrant further restrictions or an outright prohibition, indicating a data-driven and cautious approach.
Enhanced Promotional Standards and Record Keeping
Beyond leverage and margin, ASIC is also seeking to tighten the conditions under which promotional discounts and incentives can be offered to retail clients. The proposed changes aim to ensure that any permitted offers are made available on substantially equal terms to all retail customers and are prominently displayed across brokers’ websites and trading platforms, thereby enhancing transparency and preventing discriminatory practices. Furthermore, firms will be required to retain records of qualifying discounts for a period of seven years following the cessation of the offers. This extended record-keeping requirement will facilitate future regulatory oversight and enforcement. Additionally, ASIC intends to ensure that educational and research tools provided by brokers are not subtly leveraged to encourage prohibited or excessively risky trading activity, reinforcing the objective of genuine investor education rather than sales promotion.
A Timeline for Regulatory Certainty and Stakeholder Input
The existing CFD intervention order is scheduled to expire on May 23, 2027. ASIC’s proposal to extend the investor protections for another decade aims to provide firms with greater regulatory certainty, allowing them to plan their operations with a clear understanding of the compliance landscape. Simultaneously, this extension preserves the regulator’s flexibility to revoke or amend these restrictions should market conditions or investor behavior necessitate it.
However, these proposed amendments are currently under consultation, and the feedback received from industry stakeholders is expected to play a crucial role in shaping their final scope. ASIC has formally invited submissions from brokers, trading platforms, and consumer advocacy groups, with a deadline of November 9th. The regulator is particularly interested in understanding which specific digitally settled products would be impacted by the proposed changes, the anticipated compliance costs for affected firms, and whether a transition period would be necessary for businesses to adapt to the new regulatory requirements. This open consultation process underscores ASIC’s commitment to a balanced regulatory approach that considers both investor protection and the operational realities of financial service providers. The outcome of this consultation will be a critical determinant in the final form and impact of Australia’s enhanced regulatory framework for leveraged financial products.