admin
The Securities and Exchange Commission (SEC), an agency that spent much of the last decade defining its relationship with the digital asset industry primarily through high-profile enforcement actions, has formally signaled a pivot toward the long-term integration of blockchain technology into the United States’ financial core. In its draft Strategic Plan for fiscal years 2026 through 2030, the commission describes blockchain not merely as a niche asset class, but as a technology with the "potential to revolutionize America’s financial infrastructure." This document represents a significant departure from previous years, where digital assets were often relegated to the periphery of regulatory discussions or framed almost exclusively as a source of market risk. By dedicating a standalone objective to digital assets and blockchain technology, the SEC is positioning the sector alongside its most fundamental mandates: investor protection, capital formation, and agency modernization.
The strategic roadmap arrives at a critical juncture for the American financial system. As global competitors in Europe and Asia-Pacific regions advance their own frameworks for Distributed Ledger Technology (DLT), the SEC is outlining a "rational, coherent, and principled approach" to building a domestic regulatory foundation. This transition suggests that the agency is moving beyond the "regulation by enforcement" era toward a more structured era of "regulation by architecture," where the goal is to provide institutional players with the clarity needed to allocate significant capital to on-chain financial products.
A Framework for Tokenized Securities and Market Integration
Just days after the publication of the five-year plan, Jamie Selway, the director of the SEC’s Division of Trading and Markets, provided further clarity on how this strategic vision would manifest in practical policy. Speaking at the Piper Sandler Global Exchange & Fintech Conference in New York, Selway confirmed that his division is actively developing a comprehensive framework for the listing and trading of tokenized securities. This framework aims to address the technical and legal requirements for assets that exist as digital tokens on a blockchain but represent traditional ownership stakes, debt, or other financial interests.
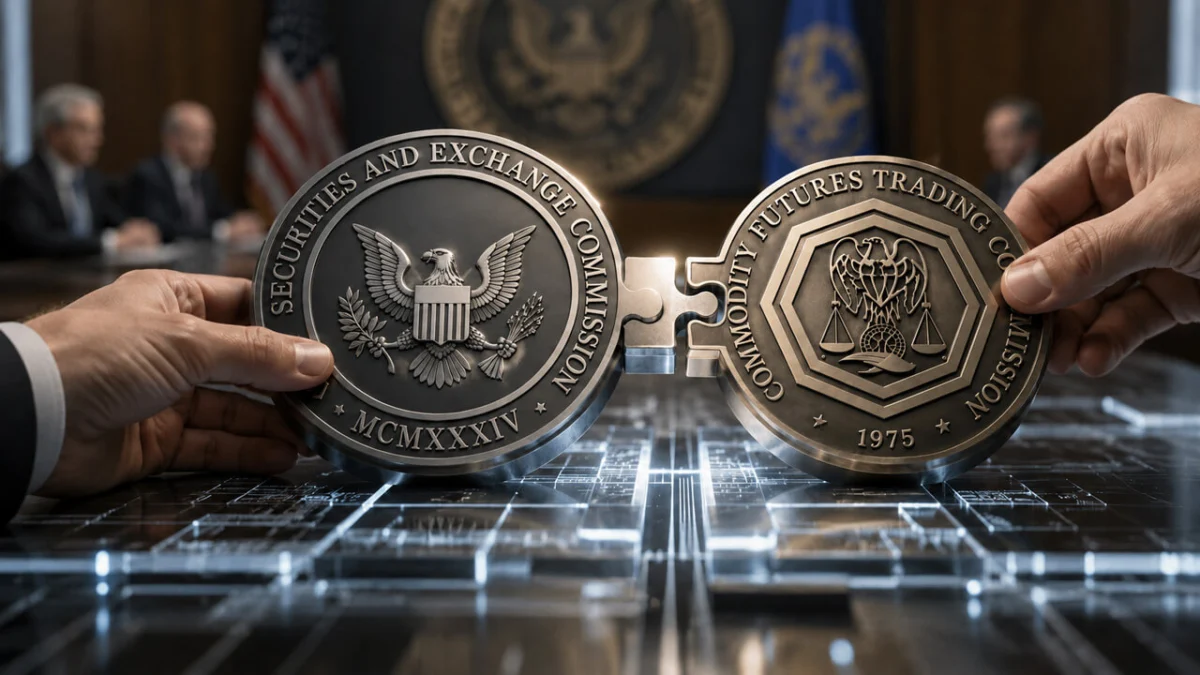
A central component of this effort is the ongoing collaboration between the SEC and the Commodity Futures Trading Commission (CFTC). Staff from both agencies are reportedly working to resolve long-standing conflicts in their respective rulebooks. Historically, the "alphabet soup" of overlapping jurisdictions has created a "structural paralysis" for firms attempting to launch cross-functional products. The joint efforts are currently focused on three primary friction points: swap reporting, portfolio margining, and standardized product definitions. By harmonizing these rules, the agencies hope to prevent regulatory arbitrage—a situation where firms choose a specific regulatory path simply because it offers lower oversight—while ensuring that the efficiency of blockchain technology is not hindered by outdated, manual compliance requirements.
Chronology of the SEC’s Policy Evolution
The 2026–2030 Strategic Plan is the culmination of a series of incremental steps taken by the commission over the past year. To understand the current shift, it is necessary to look at the timeline of actions that have moved blockchain from the periphery to the core of the SEC’s agenda:
- March 2026: The SEC approved a proposal by Nasdaq to begin trading tokenized versions of select equities alongside traditional shares. This marked the first time a major national exchange was permitted to utilize blockchain "rails" for the secondary trading of blue-chip stocks.
- April 2026: The New York Stock Exchange (NYSE) received similar approval, signaling that the move toward tokenization was not a pilot program for a single exchange but a broader industry-wide transition.
- April 2026 (Staff Statement): The SEC issued a staff statement providing self-custody trading interfaces with a five-year "runway" to obtain broker-dealer licenses. This provided temporary legal cover for decentralized finance (DeFi) innovators to transition into a compliant framework without immediate fear of shutdown.
- May 2026: The agency began contemplating a formal "innovation exemption" for tokenized stocks, which would allow certain experimental products to bypass specific legacy requirements if they could prove that the blockchain implementation provided equivalent or superior investor protections.
- June 2026: The publication of the draft Strategic Plan for 2026–2030, formalizing the agency’s commitment to blockchain as a tool for market modernization.
This chronology demonstrates that the SEC is no longer reacting to the crypto industry in a vacuum. Instead, it is responding to a growing demand from Wall Street incumbents to modernize the very plumbing of the capital markets.
The Narrative Shift: From Speculation to Market Modernization
One of the most profound impacts of the SEC’s new language is the way it alters the internal risk calculus for major financial institutions. For years, the term "crypto" was synonymous with speculative volatility and legal ambiguity. According to Jennie Levin, Chief Legal and Operating Officer at the Algorand Foundation and a former federal prosecutor, the SEC’s decision to frame the conversation around "market modernization" rather than "crypto" is a game-changer for institutional adoption.
"For institutions, stripping the word ‘crypto’ out of the conversation and replacing it with ‘market modernization’ fundamentally changes the risk calculus," Levin noted. She explained that compliance teams at major banks and asset managers, who were previously hesitant to "underwrite a speculative asset class," are now being asked to evaluate a more efficient and secure way to run existing financial infrastructure. This shift moves the technology from the "innovation lab" to the "core operations" budget.
The SEC’s stance acts as an invitation to build within a known legal architecture. In the past, firms often waited for an enforcement action against a competitor to understand where the "red lines" were drawn. The five-year plan suggests a future where the boundaries are defined by rules and guidance rather than lawsuits. For a risk committee at a global bank, a documented agency commitment to supporting "compliant capital formation" through tokenized offerings provides the concrete evidence needed to approve multi-year, multi-billion-dollar projects.
Programmable Compliance and Innovation Without Arbitrage
A recurring theme in the SEC’s recent communications is the principle of "innovation without arbitrage." This concept, emphasized by Jamie Selway, addresses a common skepticism: that blockchain’s only advantage is its ability to bypass traditional regulations. The SEC’s current leadership appears to be moving toward a different conclusion—that blockchain technology can actually make compliance more robust.
The concept of "programmable compliance" suggests that instead of having a team of hundreds of people manually verifying transactions at the end of a trading day, the rules can be baked into the asset itself. Using smart contracts, issuers can enforce transfer restrictions, maintain "allow lists" of verified investors, and execute "freeze-and-clawback" controls directly on the protocol level. In this model, the efficiency of the ledger does not come from cutting corners, but from eliminating the need for fragmented settlement infrastructure and the layers of reconciliation currently required to manufacture trust between intermediaries.
Levin argues that the networks most likely to succeed in this new environment are those that treated compliance as a primary feature rather than an afterthought. As the SEC and CFTC move toward a unified token taxonomy, the "greatest friction point"—jurisdictional ambiguity—will begin to dissolve. Predictable classification allows internal risk committees to make faster decisions, potentially reversing the trend of capital flowing offshore to more permissive, but less stable, jurisdictions.
Legislative Catalysts: The Role of the CLARITY Act
While the SEC’s strategic plan provides a roadmap, the ultimate destination requires statutory backing. The legislative piece of the puzzle is currently moving through the U.S. Congress in the form of the CLARITY Act. This legislation, which passed the House with a bipartisan 294-134 vote in July 2025 and cleared the Senate Banking Committee in May 2026, aims to codify the definitions of digital assets and provide a clear division of labor between the SEC and the CFTC.
The bill is currently on the Senate Legislative Calendar, but it faces a tight window. To pass before the August recess, it requires 60 votes on the Senate floor. Market analysts and political forecasters remain cautiously optimistic but wary of scheduling pressures. Galaxy Digital recently adjusted its odds for the bill’s passage in 2026 from 75% to 60%, citing the "calendar crunch" rather than a lack of political support. Polymarket, a decentralized prediction market, currently prices the probability of passage in the mid-50s.
The CLARITY Act is viewed by many as the "bridge" that will turn the SEC’s interpretations into permanent law. Without it, a change in administration or agency leadership could potentially shift the strategic direction once again. Statutory clarity would provide the "lock-in" effect that the largest global custodians and pension funds require before fully committing to on-chain assets.
Future Milestones and the New Financial Reality
As the SEC moves forward with its 2026–2030 strategy, several key milestones will serve as indicators of its progress. The industry will be watching for formal rule proposals governing tokenized securities, measurable updates on the SEC-CFTC harmonization project, and further guidance on the custody of digital assets by traditional banks.
The broader implication of this shift is that the primary beneficiaries of the next wave of blockchain adoption will likely be the infrastructure providers enabling compliant capital markets rather than the issuers of speculative tokens. The focus has moved from "disrupting" the financial system to "upgrading" it.
Ultimately, the SEC’s draft Strategic Plan marks the end of an era of skepticism and the beginning of an era of integration. By acknowledging that blockchain has the potential to revolutionize the nation’s financial infrastructure, the agency is no longer asking whether the technology belongs in the system, but rather how it can be used to make that system more transparent, efficient, and secure. The future of tokenization now rests on the ability of regulators and market participants to build a stable, predictable legal framework that fosters innovation while maintaining the rigorous investor protections that have long been the hallmark of the American capital markets.