admin
Bitcoin’s market dynamics present a complex and somewhat contradictory picture, as sophisticated options traders are increasingly hedging against downside risk while leveraged futures traders maintain a bullish outlook, even as the cryptocurrency grapples with ongoing selling pressure in the spot market. This divergence, highlighted in a recent Glassnode report, suggests a market on edge, bracing for potential volatility while underlying demand struggles to gain traction. The situation is further complicated by the looming Federal Reserve interest rate decision later this month, adding another layer of uncertainty to the cryptocurrency’s immediate future.
Shifting Sands in Bitcoin Options: A Growing Appetite for Protection
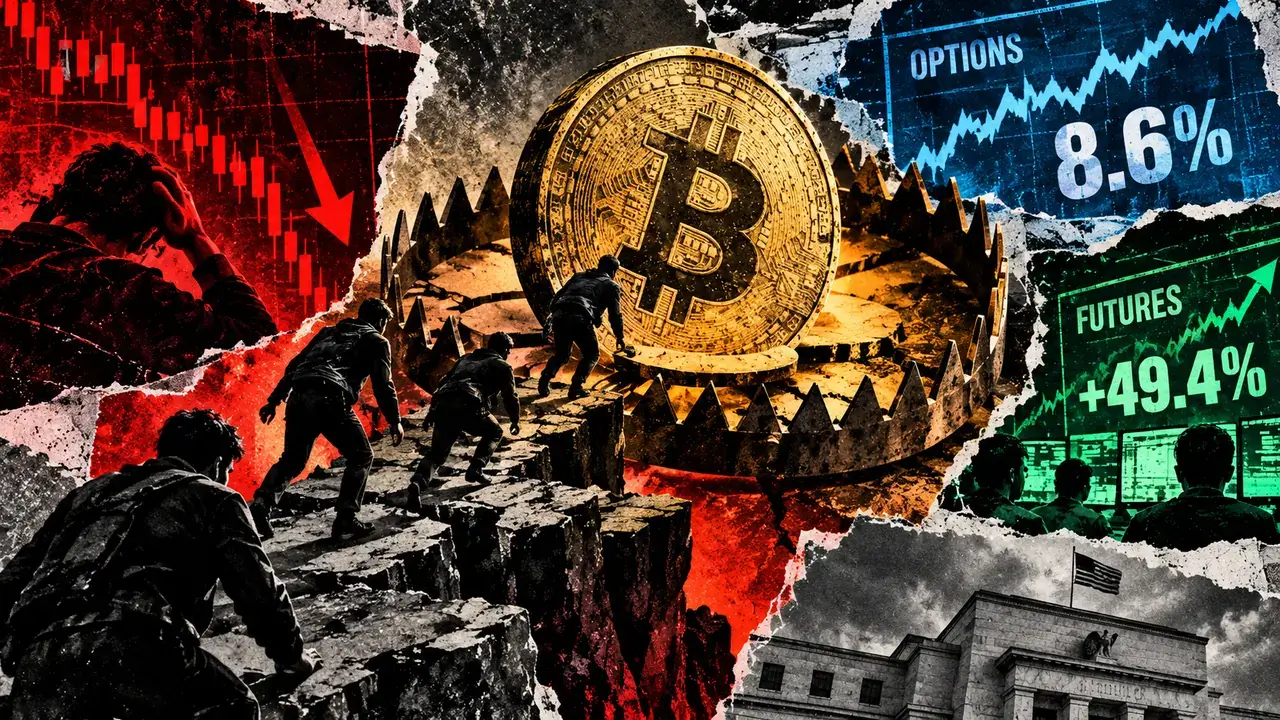
Analysis of Bitcoin’s options market, a sophisticated financial instrument used for hedging and speculation, reveals a marked shift towards caution. Over the preceding week, Glassnode data indicates that the 25-delta options skew, a key metric reflecting the relative pricing of out-of-the-money put (bearish) and call (bullish) options, climbed from 5.2% to 8.6%. This upward trend signifies that traders are willing to pay a higher premium for options that protect against a price decline compared to those that bet on price appreciation. Essentially, the cost of insurance against a Bitcoin drop has risen significantly.
This defensive posture is unfolding even as Bitcoin’s recent price action has been relatively subdued. Despite a sell-off that has seen the cryptocurrency trade near $81,300, more than 2% lower than the previous week at press time, the market is anticipating potential future turbulence. The implied-versus-realized volatility spread, another crucial indicator, flipped from -3.8% to +2.1% over the same period. This shift signifies that the volatility embedded in options prices – what traders expect to happen – has begun to outpace the actual, observed volatility in the market. This suggests a market increasingly willing to pay a premium for the possibility of significant price swings, even after a period of comparatively restrained trading.
The increase in the 25-delta skew to 8.6% is significant. While still within the historical statistical range, it represents a notable increase in the demand for downside protection. This indicates that investors are placing a greater emphasis on safeguarding their existing holdings against further depreciation, particularly following Bitcoin’s inability to sustain a robust recovery above key breakout levels observed in late September. The implied volatility exceeding realized volatility further underscores this sentiment, suggesting that market participants are pricing in a higher probability of future price fluctuations than what has recently materialized.
Despite this growing caution, open interest in Bitcoin options has seen a modest increase, rising 3.1% to $38.6 billion from $37.4 billion in the prior week. This suggests that while traders are actively seeking to hedge their positions, they are not necessarily exiting the options market altogether. Instead, they are reallocating their exposure, favoring instruments that offer protection. The combination of a stronger put skew and a positive volatility spread paints a picture of a market that is maintaining its derivative exposure while simultaneously prioritizing downside risk management.
The Conundrum of Weak Spot Demand and Robust Futures Interest
The defensive sentiment in the options market stands in stark contrast to the bullish positioning observed in Bitcoin’s perpetual futures market. Perpetual futures, a derivative product that allows traders to speculate on the price of an asset without an expiry date, have seen a surge in leveraged bullish bets. Aggregate funding payments by perpetual futures longs jumped by a substantial 49.4%, from $1.1 million to $1.6 million over the past week. Funding payments are a mechanism within perpetual futures contracts designed to keep the futures price tethered to the underlying spot price. When longs significantly outweigh shorts, longs pay a funding fee to shorts, incentivizing a rebalancing of positions. The increase in these payments indicates that traders holding long positions are collectively paying more to maintain their leveraged exposure, a clear sign of sustained bullish sentiment.
This resurgence in demand for leveraged bullish exposure, however, is occurring without a corresponding expansion in the overall open interest for Bitcoin futures, which slightly dipped by 0.3% to $36.4 billion. This suggests that while existing bullish positions are being reinforced and new ones are being opened, the total notional value of outstanding futures contracts remains relatively stable, hovering near the upper end of its historical range. This scenario implies that leveraged traders are actively seeking to profit from potential price increases, even as the underlying spot market shows signs of weakness.
Compounding this dichotomy, data from Glassnode indicates that while futures selling pressure has eased – with the perpetual futures cumulative volume delta improving significantly by 36.9% from -$891.1 million to -$562.7 million – sell orders continue to dominate trading. This suggests a moderation in aggressive selling but not a decisive shift towards accumulation. The fact that this improvement in futures dynamics is occurring alongside persistent selling in the spot market creates an uneven playing field.
Spot Market Under Pressure: The Tale of Cumulative Volume Delta
The spot market for Bitcoin has been under pressure, with evidence of sustained selling. Glassnode’s spot cumulative volume delta (CVD), a metric that measures the imbalance between aggressive buying and selling on centralized exchanges, has widened from -$67 million to -$83.6 million over the week. This represents a 24.7% deterioration, indicating that aggressive sell orders are increasingly outweighing aggressive purchase orders. This metric is crucial as it directly reflects the conviction behind buying and selling pressure in the immediate, on-the-ground market.
Despite this intensifying selling pressure, trading volume has remained relatively stable, increasing modestly from $5.4 billion to $5.5 billion. This suggests that while participation has not waned, the composition of that participation is leaning towards sellers. The lack of convincing evidence of sustained spot accumulation, coupled with this widening negative CVD, presents a challenge for Bitcoin’s price recovery.
On-Chain Indicators: A Shift Towards Shorter-Term Holders and Weakening Profitability
Further on-chain analysis adds another layer of complexity to the market’s current state. The ratio of short-term to long-term holder supply has increased, moving above its historical upper band. This indicates a greater proportion of Bitcoin is now held by investors who have held their assets for a shorter duration. These newer holders are often considered more price-sensitive and may be more inclined to sell during periods of price decline, potentially exacerbating downward pressure. The share of capital held by these newer, more speculative investors also remains elevated at 20.3%.
This shift towards shorter-term ownership coincides with weakening profitability for Bitcoin holders. The percentage of Bitcoin’s supply held in profit has declined from 70.1% to 68.2%. More strikingly, the realized profit-to-loss ratio has fallen from 0.8 to 0.4. This means that for every dollar gained in realized profit, there are now $0.40 in realized losses, a significant shift from the previous week where profits slightly outweighed losses. This trend suggests that a growing number of investors are selling their holdings at a loss, a sentiment that can further dampen market enthusiasm and encourage more defensive positioning.
The Road Ahead: Key Levels and Macroeconomic Headwinds
The immediate challenge for Bitcoin lies in its ability to defend the crucial $80,000 level. This price point has historically attracted significant buying interest since the October decline, and a sustained breakdown below it could trigger a wave of liquidations among leveraged long positions, thereby intensifying selling pressure. This scenario would align with the growing premium on downside protection already observed in the options market, potentially leading to a sharp acceleration of price declines.
Adding to the market’s volatility are macroeconomic factors, most notably the upcoming Federal Reserve interest-rate decision scheduled for October 27-28. Persistent inflation data in the United States could prompt the Federal Reserve to consider further monetary tightening, a move that typically dampens investor appetite for riskier assets like cryptocurrencies. Such a development could act as a significant catalyst, potentially pushing Bitcoin and other digital assets lower and forcing leveraged traders to reassess their bullish bets.
The current market environment for Bitcoin is characterized by a fascinating dichotomy: a growing sense of unease and a desire for protection among options traders, juxtaposed with a stubborn bullish conviction among leveraged futures participants. This, coupled with weakening spot demand and evolving on-chain holder behavior, creates a delicate balance. The cryptocurrency’s ability to navigate these competing forces, defend key price levels, and withstand potential macroeconomic headwinds will be critical in determining its trajectory in the coming weeks. The market is at a crossroads, where the actions of sophisticated traders and the broader economic landscape are poised to dictate Bitcoin’s next significant move.