admin
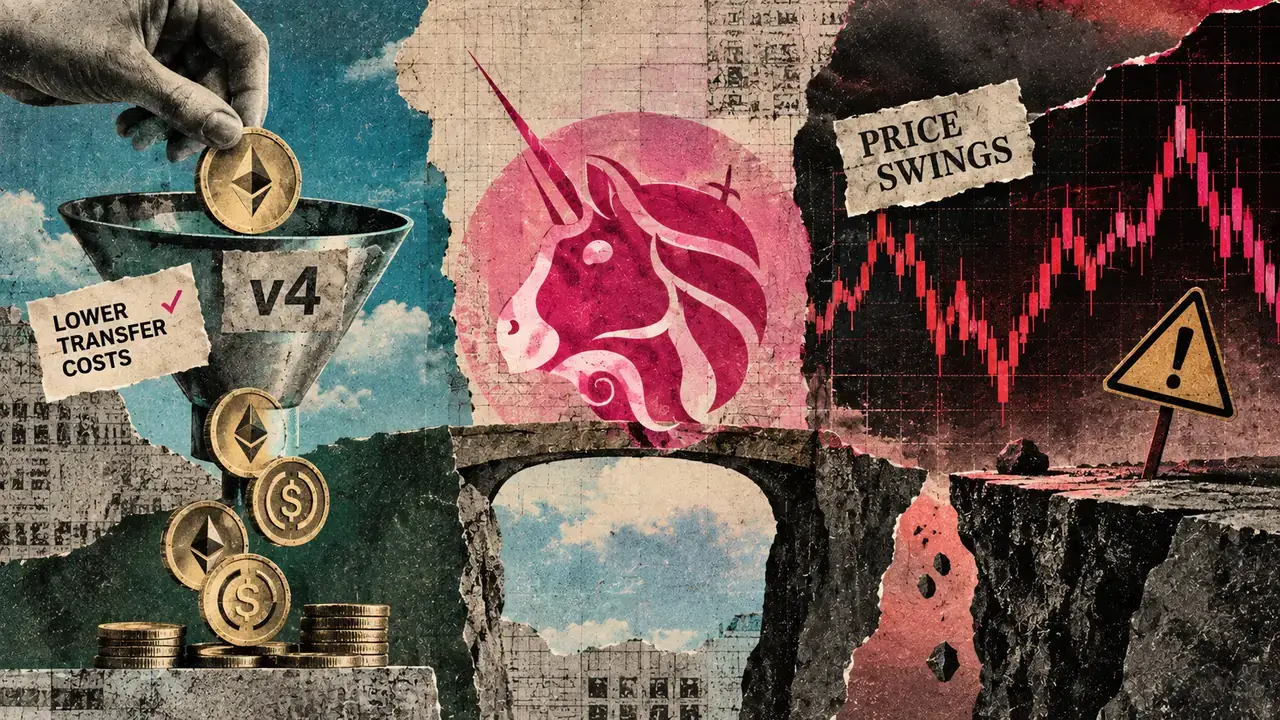
A comprehensive study conducted by blockchain data analytics firm Bitquery has illuminated a critical challenge facing smaller liquidity providers (LPs) on Uniswap v3: the disproportionate impact of gas fees on their returns. The findings, detailed in a report released on October 16, indicate that for many participants with modest capital invested in Uniswap v3 liquidity pools on Ethereum, the cost of transactions has significantly diminished or even negated the benefits of providing liquidity, often making simply holding the underlying tokens a more profitable strategy.
The research, which meticulously analyzed eight sampled Ethereum v3 pools over a one-year period from October 14, 2025, to October 13, 2026, revealed a stark contrast in profitability before and after accounting for transaction costs. Specifically, among closed regular positions with an initial deposit value of less than $1,000, a substantial 51% outperformed the strategy of simply holding the tokens when gas fees were not considered. However, once these transaction costs were factored in, this success rate plummeted to a mere 18%. The median gas bill for these small positions was a notable 67 cents, a sum that could easily consume any marginal gains.
This revelation underscores a fundamental economic reality in decentralized finance (DeFi): the pervasive influence of network transaction fees, commonly known as gas. In the context of automated market makers (AMMs) like Uniswap, LPs deposit pairs of tokens into liquidity pools, enabling traders to swap between them. In return for providing this liquidity, LPs earn a portion of the trading fees generated by the pool. However, every action an LP takes – adding liquidity, removing liquidity, or even managing their positions – incurs a gas fee on the underlying blockchain, in this case, Ethereum.
The Evolving Landscape of Uniswap and the Promise of v4
Uniswap, a pioneer in decentralized exchange technology, has undergone significant evolution. Uniswap v3 introduced the concept of concentrated liquidity, allowing LPs to specify price ranges within which their liquidity would be active and earn fees. While this innovation offered greater capital efficiency, it also introduced more complexity. As market prices fluctuate, the composition of an LP’s holdings within a concentrated liquidity position changes. If the price moves beyond a specified range, the LP’s position becomes entirely composed of one asset, ceasing to earn trading fees until the price re-enters the designated range. Consequently, fees earned must not only compensate for the base transaction costs but also for the potential inventory changes and the risk of liquidity becoming inactive.
The upcoming Uniswap v4, currently in development, aims to address some of these inefficiencies, particularly through its "flash accounting" feature. This mechanism is designed to reduce transfer overhead for LPs by netting internal obligations during complex operations. Instead of multiple token transfers occurring between different pool contracts, v4 intends to track these obligations internally and only execute final net balance changes. This can be particularly beneficial for LPs engaging in multi-step transactions, such as combining a swap with a liquidity deposit, where intermediate token movements can rack up significant gas costs.
Gas Costs: A Major Hurdle for Small-Scale Liquidity Providers
The Bitquery study’s granular breakdown of results by deposit size provides compelling evidence of how gas fees disproportionately affect smaller LPs. Across all eight sampled Ethereum v3 pools, 49% of the 71,166 closed regular positions managed to outperform the simple holding strategy before gas fees were deducted. After accounting for these transaction costs, this figure dropped to 34%.
The impact of gas becomes acutely pronounced for positions valued below $1,000. For these smaller stakes, a transaction cost measured in mere cents can easily erode any narrow advantage gained over simply holding the tokens. Larger deposits, conversely, benefit from a spreading of these fixed transaction costs over a greater capital base, which explains the widening gap in win rates between before-and-after gas fee calculations as position size increases.
The study’s published size breakdown vividly illustrates this trend:
- Below $1,000: 51% beat holding before gas; only 18% beat holding after gas. This represents a significant 33-percentage-point difference.
- $1,000 – $10,000: 45% beat holding before gas; 36% beat holding after gas. A 9-percentage-point difference.
- $10,000 – $100,000: 50% beat holding before gas; 45% beat holding after gas. A 5-percentage-point difference.
- $100,000 – $1 million: 55% beat holding before gas; 51% beat holding after gas. A 4-percentage-point difference.
- Above $1 million: 60% beat holding before gas; 59% beat holding after gas. A minimal 1-percentage-point difference.
It is crucial to note that these rounded percentages represent the frequency with which a closed position outperformed the holding benchmark, not the dollar-weighted average return. A portfolio can exhibit a high win frequency with many small gains and fewer large losses, which might appear favorable in terms of count but could still result in a net loss when compared to a holding strategy that experienced larger, less frequent gains.
For the smallest deposit band, the 33-percentage-point differential between before-and-after gas win rates highlights the consequential nature of even modest execution savings. When a position’s potential advantage over simply holding is already narrow, transaction costs can swiftly turn a profitable endeavor into a losing one.
Bitquery’s methodology for calculating returns involves comparing the dollar value of tokens returned from a position, plus any collected fees, against the value of holding the deposited tokens. Gas fees are then deducted from the LP’s net gains. It’s important to understand that a position could increase in dollar value but still underperform a holding benchmark that experienced even greater appreciation.
Aggregate Financial Performance and Unclaimed Fees
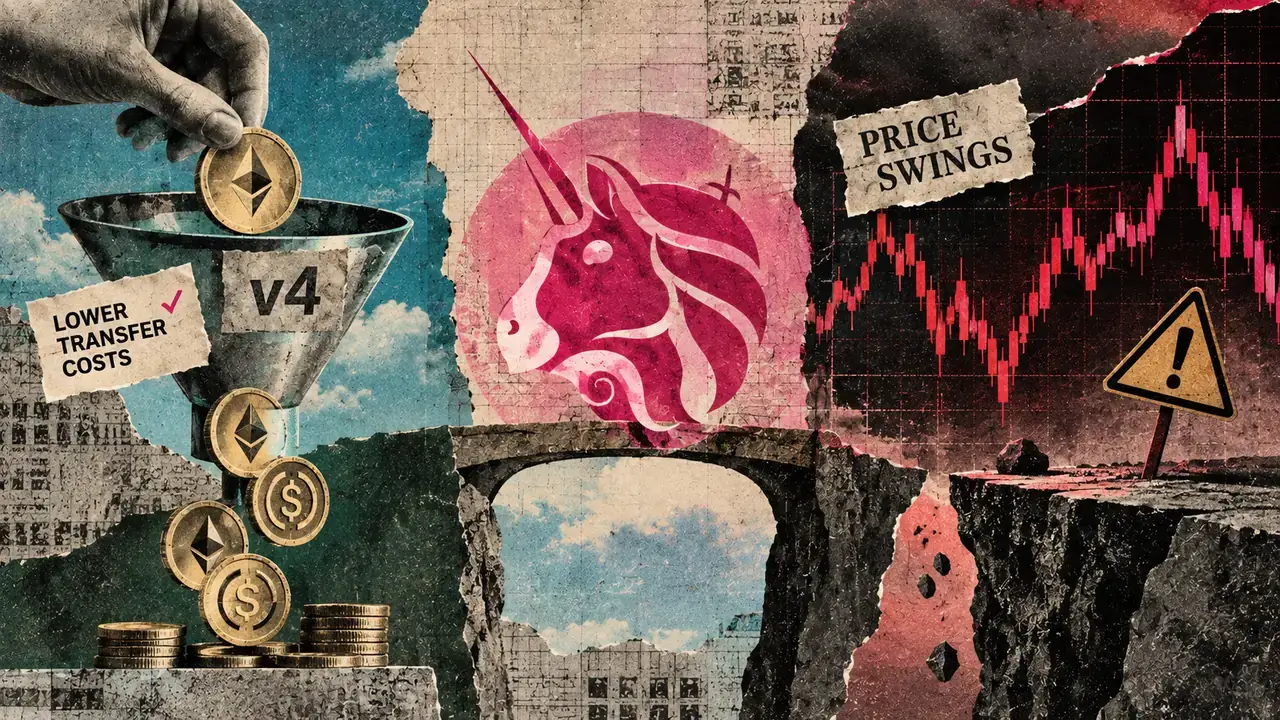
The study’s aggregate financial analysis, which incorporates both closed and open positions, paints a broader picture of the economic activity within the sampled pools. It reports a total of $41.6 million in collected fees. However, there was an inventory shortfall of $60.6 million when compared to a passive holding strategy, and gas costs amounted to $1.4 million. When these figures are reconciled, the net result shows a collective deficit of approximately $20.4 million behind the holding benchmark. Open positions are valued at their closing prices on the observation cutoff date.
Bitquery estimates that the sampled pools generated a gross total of $59.5 million in fees. The discrepancy between this figure and the $41.6 million in collected fees suggests that a portion of the earned fees remained unclaimed at the study’s cutoff or could not be definitively attributed to specific positions. These unclaimed or unassigned fees are a significant factor, particularly as open positions are excluded from the win rate calculations due to the absence of their unclaimed fees in the event-based accounting. Furthermore, 207 positions with fee claims that were transferred between sibling positions were excluded from per-position analyses to maintain data integrity. Bitquery applies a consistent methodology, counting each transaction’s gas once and distributing it across relevant liquidity actions.
Uniswap v4: A New Era of Efficiency and Flexibility?
The anticipated release of Uniswap v4 holds the promise of mitigating some of the gas-related challenges identified in the study. Ethereum transaction fees, paid in Ether (ETH), are a persistent concern. V4’s flash accounting system is engineered to streamline operations by internally managing token obligations. This means that instead of tokens being repeatedly transferred between separate pool contracts during a complex operation, their movements can be offset internally, with only the net changes requiring actual on-chain transfers.
This efficiency gain is particularly relevant for LPs who execute multi-pool routes or combine multiple actions, such as depositing liquidity while simultaneously executing a swap. By avoiding numerous intermediate transfers, these LPs could see a significant reduction in their gas expenditure. The degree of saving will, however, be contingent on the specific transaction route and the integration of various components within the v4 architecture.
Despite the potential for gas savings, the core concentrated liquidity mechanics introduced in v3 are slated to be retained in v4. This means that LPs will continue to define price ranges for their capital. As trading activity shifts market prices, the quantity of each token within an LP’s position will fluctuate. If the price breaches the boundaries of the specified range, the position will transform into an exclusive holding of one asset, ceasing to earn trading fees until the price reverts. This inherent characteristic means that even with reduced gas costs, an LP can still find themselves underperforming a simple holding strategy if the "inventory gap" – the difference in asset composition due to price movement – outpaces the fees earned.
Adoption Trends and the Road to v4
Early indicators suggest a growing interest in Uniswap v4. A separate Bitquery study comparing v3 and v4 activity, updated on October 15, analyzed data from July 15 to October 13. This research indicated a substantial increase in v4 liquidity additions, rising from approximately 1,288 per day in the first week of the observation period to 4,474 per day in the final week, representing a nearly 3.5-fold increase. In contrast, v3 liquidity additions remained relatively stable, hovering around 1,300 per day. This corrected comparison, which excludes zero-size events from both versions, reveals that v4 liquidity additions outpaced removals on 88 out of 91 days, while v3 saw this trend on 89 out of 91 days. While this metric captures the frequency of liquidity movements, it does not quantify the dollar value of assets added or withdrawn.
The "standard position-manager" route emerged as a significant driver of v4’s growth in add-count, accounting for 77% of the increase. This route is utilized by a diverse range of actors, including automated trading bots, token launch protocols, and individual wallet holders. The study identified 3,074 unique wallet addresses actively engaging in transactions across both v3 and v4, a stark contrast to the 18 addresses observed when counting only the contracts directly calling the liquidity pools. These figures represent counts of active addresses rather than an estimation of the number of individual users. Due to differences in fee recording mechanisms between v3 and v4, Bitquery’s comparative analysis has thus far been confined to liquidity behavior, and direct comparisons of matched v3 and v4 position returns have not been undertaken.
The Impact of Dynamic Fees and Hooks
Uniswap v4 also introduces the flexibility of "hooks," which are optional modules that can customize various aspects of pool behavior, including fee structures, accounting methods, and pricing curves. These advanced customizations can significantly alter the economic outcomes for LPs, extending beyond mere transfer costs. As such, standard concentrated liquidity mechanics may not be sufficient to fully assess the performance of all hooked pools.
On October 14, Uniswap Labs announced the launch of its "VolatilePair Hook" on Ethereum, initially implemented for the ETH/USDC trading pair. This hook is designed to recalculate separate buying and selling fees dynamically on each swap, based on recent price movements. This innovative feature, however, falls outside the scope of the Bitquery study’s observation window, which concluded on October 13.
A related analysis by CryptoSlate on October 1, examining the "StablePair Hook," highlighted a critical distinction: changes in fee rules can impact trading income while LPs remain exposed to the price volatility of their held assets. The new data from the Bitquery v3 study adds a concrete dimension to this challenge by illustrating how position size exacerbates the problem, particularly for smaller investors.
Ultimately, the success of providing liquidity on Uniswap, even with the advent of v4, will continue to be a multifaceted calculation. While v4 offers the potential to reduce the overall gas bill through its flash accounting, the net outcome for any given LP will depend on a complex interplay of factors: the ultimate inventory of assets returned, the fees earned from trading activity, and the total gas paid throughout the lifecycle of their liquidity provision. The Bitquery study serves as a crucial reminder that in the decentralized finance ecosystem, transaction costs remain a significant variable that can profoundly influence the profitability of even seemingly straightforward investment strategies.