admin
The European Securities and Markets Authority (ESMA) has issued a critical directive to crypto firms operating under the European Union’s Markets in Crypto-Assets (MiCA) regulation, mandating that they resolve all outstanding client exposure to stablecoins that do not comply with MiCA by January 8, 2027. This stringent deadline, set approximately three months from the opinion’s publication on October 8, 2026, significantly tightens restrictions on how these firms can manage customer assets, with a particular focus on custody and transfer services. The move signals a decisive step by EU regulators to enforce the framework of MiCA and ensure a level playing field within the burgeoning digital asset market.
ESMA’s Mandate: A Three-Month Countdown for Compliance
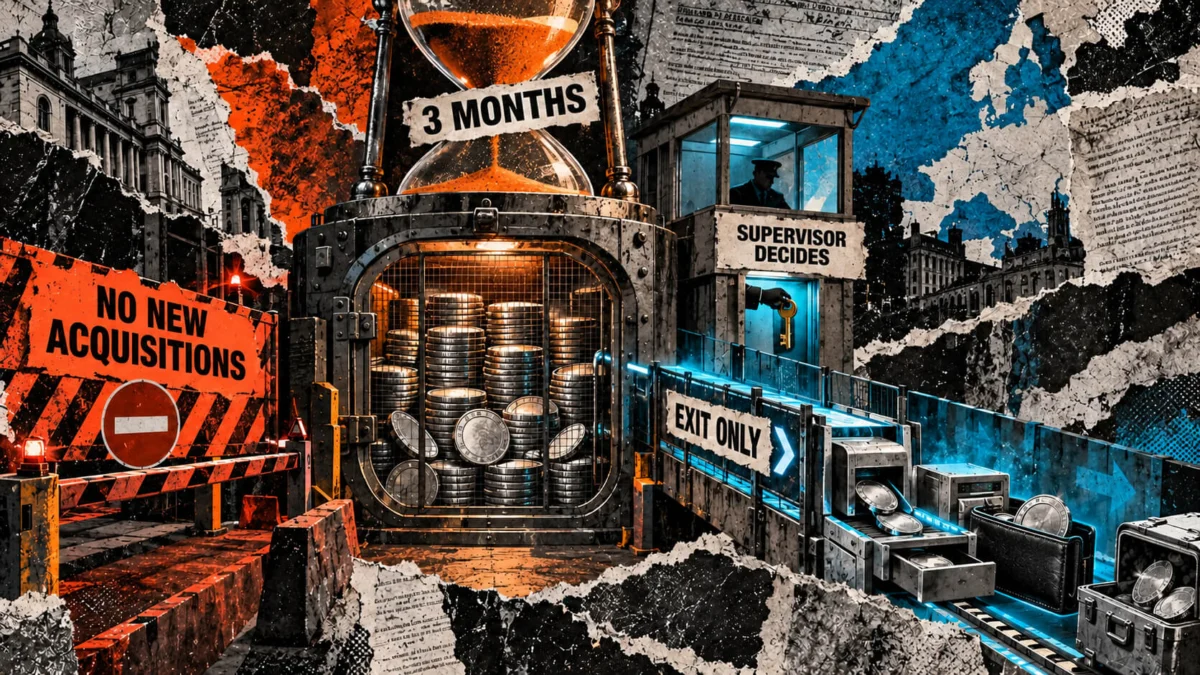
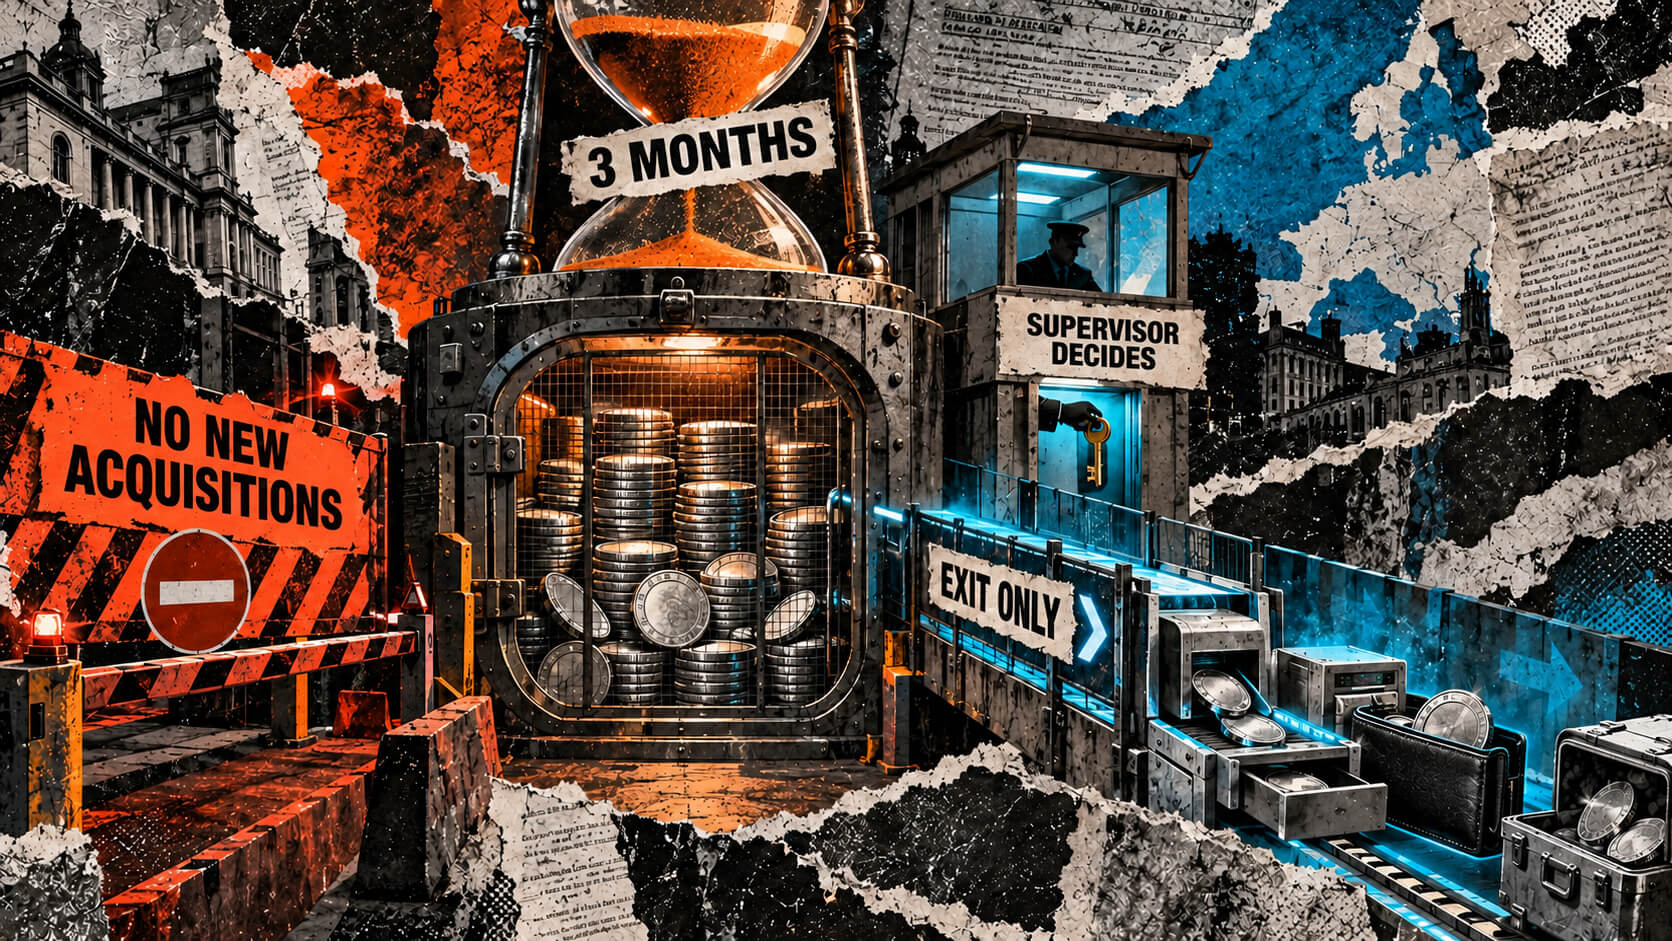
ESMA’s latest opinion, published on October 8, 2026, provides crucial guidance to national regulators on how to handle existing exposures to asset-referenced tokens (ARTs) and e-money tokens (EMTs) that do not meet the stringent requirements laid out in MiCA. The watchdog’s stance is clear: any legacy exposure to non-compliant stablecoins must be addressed by EU crypto firms through their regulated services. National supervisors are instructed to require firms to facilitate an orderly wind-down of these exposures as swiftly as possible, with a firm deadline of three months from the opinion’s release, effectively placing the onus on firms to complete these resolutions by early January 2027.
While the directive emphasizes the need for resolution, ESMA acknowledges that a complete and immediate cessation of all services might not always be feasible or in the best interest of clients. Therefore, national regulators are granted discretion to permit firms to offer strictly limited services necessary for an orderly wind-down. These permitted services are narrowly defined and can include liquidation, conversion into compliant assets or fiat currency, withdrawal, transfer to a compliant platform, or safekeeping of existing holdings. The primary objective is to prevent harm to clients and ensure a smooth transition away from non-compliant assets.
Crucially, these exceptional services must be time-limited, clearly communicated to clients, and subject to close supervision by national authorities. They are explicitly designed to facilitate an exit and do not permit any new acquisitions, promotional activities, active distribution of non-compliant tokens, or their continued availability in the market. The ultimate decision on whether to allow these limited services rests with the national supervisor, meaning clients do not automatically gain an extended period of continued access; rather, it depends on the specific supervisory assessment within their jurisdiction.
The Legal Basis: Protecting Client Interests Under MiCA
The legal foundation for ESMA’s opinion lies in Article 66(1) of MiCA, which imposes a general obligation on crypto-asset service providers (CASPs) to act honestly, fairly, and professionally in accordance with the best interests of their clients. ESMA interprets providing any MiCA service that involves a non-compliant stablecoin as inherently incompatible with this duty. This presumption holds true regardless of whether the specific service constitutes an offer to the public or an admission to trading on a regulated market.
ESMA’s rationale is that crypto firms cannot adequately mitigate the inherent risks associated with stablecoins that lack the requisite issuer-level safeguards mandated by MiCA. The watchdog explicitly states that mere warnings, disclosures to clients, or even client acknowledgments of risk would not be sufficient to alleviate these concerns. The absence of robust issuer-level controls, such as reserves, redemption rights, and governance mechanisms, creates an unacceptable level of risk that EU-authorized firms are not permitted to facilitate, even indirectly.
A Progressive Enforcement Approach: Building on Previous Guidance
This latest opinion builds upon ESMA’s previous guidance. In a statement released on January 17, 2025, ESMA had already outlined a more restrictive stance, leaving only mere custody and transfers of non-compliant stablecoins open while significantly restricting trading and other services that could be interpreted as public offers. The new opinion complements this earlier guidance by preserving the interpretation of "offer to the public" while also introducing specific expectations regarding providers’ existing duties under MiCA and a concrete timeline for addressing legacy exposures.
Earlier, on September 30, 2026, in its response to the European Commission’s consultation on the MiCA regulation review, ESMA had advocated for legislative amendments to prohibit all licensable services involving non-compliant stablecoins. However, that proposal did not specify an implementation date or a clear path for the wind-down of existing exposures. The October opinion thus adds a crucial temporal dimension and outlines a framework for supervised exit arrangements under the current MiCA obligations, aligning with ESMA’s legislative request made on October 3, 2026.
Beyond Trading: The Broader Implications for Stablecoin Access
While ESMA’s opinion does not name specific tokens or issuers, its implications are far-reaching. Stablecoins such as Tether’s USDT, which have been identified by exchanges like Coinbase in their EEA retail guidance as MiCA-non-compliant, are now directly affected. Coinbase has labeled USDT as non-compliant with MiCA, indicating potential restrictions for EU users.
Similarly, Kraken, in its updated guidance from April 13, 2026, has delisted USDT trading pairs for its European Economic Area (EEA) clients. While Kraken still permits deposits and withdrawals of USDT, it actively discourages them, signaling a cautious approach to managing exposure to potentially non-compliant assets. The practical effect of ESMA’s directive is that simply removing USDT trading pairs may not be sufficient for MiCA-authorized firms if they continue to service USDT as a non-compliant token in any capacity. Any remaining services must align with the narrowly defined, supervised wind-down procedures.
For existing holders of non-compliant stablecoins, the immediate concern is the extent to which their service provider, in conjunction with their national supervisor, will permit exit services. It is important to note that ESMA’s directive specifically addresses access through regulated EU firms. It does not impose a global ban on the ownership of stablecoins like USDT. However, EU-based individuals holding such assets through regulated platforms will need to navigate the specific rules and timelines set by their providers and national authorities to divest or transfer their holdings.
Background and Chronology of Regulatory Action
The development of MiCA and its subsequent implementation has been a multi-year process, aiming to bring clarity and consumer protection to the rapidly evolving crypto market.
- 2020-2022: Initial proposals and discussions around crypto-asset regulation in the EU, with a growing focus on stablecoins due to their increasing market capitalization and potential systemic risks.
- June 2022: The European Parliament and Council reach a provisional agreement on the MiCA Regulation.
- 2023: MiCA is formally adopted and published in the Official Journal of the European Union, with most provisions scheduled to take effect from late 2024.
- January 17, 2025: ESMA releases an initial statement clarifying its stance on stablecoins under MiCA, restricting services beyond custody and transfers for non-compliant tokens.
- Early 2026: National regulators begin identifying specific stablecoins and assessing their compliance with MiCA. Some exchanges start delisting or restricting certain stablecoins for EU clients.
- September 30, 2026: ESMA submits its response to the MiCA review consultation, proposing a legislative ban on all licensable services involving non-compliant stablecoins.
- October 3, 2026: ESMA reiterates its call for legislative action on non-compliant stablecoins.
- October 8, 2026: ESMA publishes its opinion providing a three-month deadline for EU crypto firms to resolve client exposure to non-compliant stablecoins, detailing the scope of permitted exit services.
- January 8, 2027: The deadline for EU crypto firms to resolve outstanding client exposures to non-compliant stablecoins under ESMA’s directive.
Supporting Data and Market Context
The stablecoin market has seen exponential growth in recent years. As of late 2026, the total market capitalization of stablecoins is estimated to be over $200 billion, with several individual tokens holding tens of billions of dollars in market value. This scale underscores the potential systemic impact of any instability or regulatory non-compliance within the stablecoin ecosystem.
MiCA’s introduction of strict rules for stablecoins, particularly for significant tokens that may become "significant" under the regulation, aims to address these risks. These rules include requirements for issuers to maintain adequate reserves, provide redemption rights, and adhere to governance and transparency standards. Tokens that fail to meet these criteria, often referred to as non-compliant or legacy stablecoins, pose a challenge for regulators seeking to apply the new framework.
The current regulatory action by ESMA reflects a broader global trend towards increased scrutiny of stablecoins. Jurisdictions worldwide, including the United States, are grappling with how to regulate these digital assets effectively, balancing innovation with financial stability and consumer protection. The EU’s approach, with its clear timeline and defined exit strategy, provides a concrete example of how a major regulatory bloc is enforcing its established framework.
Analysis of Implications
ESMA’s directive is a significant development with several key implications:
- Increased Regulatory Certainty (and Pressure): While firms have had some time to prepare, the concrete deadline of January 8, 2027, removes ambiguity. It compels firms to act decisively and allocate resources towards resolving legacy exposures, potentially incurring costs associated with client communication, asset liquidation, or conversion.
- Shift in Stablecoin Landscape: The directive will likely accelerate the consolidation of the stablecoin market within the EU, favoring tokens that fully comply with MiCA. Issuers of non-compliant stablecoins will face diminished utility and access within the EU’s regulated financial ecosystem.
- Client Protection and Risk Mitigation: By mandating an orderly wind-down, ESMA aims to protect retail and institutional investors from potential losses due to the inherent risks of non-compliant stablecoins. The focus on supervised exit services ensures that clients have a pathway to recover their funds or convert them into compliant assets.
- Operational Challenges for Firms: Crypto firms will need to develop robust processes for identifying, communicating, and facilitating the resolution of non-compliant stablecoin exposures for their EU clients. This may involve complex logistical challenges, especially for firms with a large client base and diverse asset offerings.
- Potential for Market Fragmentation: While the goal is harmonization, the discretion granted to national supervisors in allowing limited exit services could lead to minor variations in implementation across different EU member states. This could create complexities for firms operating in multiple jurisdictions within the bloc.
The stringent deadline and the detailed guidance from ESMA underscore the EU’s commitment to a well-regulated digital asset market. The coming months will be crucial as crypto firms navigate these new requirements and work towards a compliant future for stablecoins within the European Union.