admin
The United States Securities and Exchange Commission (SEC), an agency that spent nearly a decade defining its relationship with the digital asset sector primarily through high-profile enforcement actions, has formally signaled a transition toward a more integrated regulatory posture. In its recently published draft Strategic Plan for fiscal years 2026 through 2030, the commission describes blockchain technology as possessing the "potential to revolutionize America’s financial infrastructure." This document marks a significant rhetorical and policy departure, elevating digital assets from a peripheral enforcement concern to a core strategic priority alongside foundational mandates such as investor protection, capital formation, and agency modernization.
The draft plan dedicates a standalone objective to the oversight of digital assets and blockchain technology. Within this framework, the SEC outlines an intent to build a regulatory foundation characterized by a "rational, coherent, and principled approach." This shift suggests that the agency is moving beyond the "regulation by enforcement" era toward a structured environment where innovation can occur within established legal boundaries. The implications of this shift are already resonating across Wall Street, as the change in narrative from "crypto" to "market modernization" begins to alter the risk calculus for the nation’s largest financial institutions.
A New Framework for Tokenized Securities
Shortly after the release of the strategic plan, Jamie Selway, Director of the SEC’s Division of Trading and Markets, provided additional clarity on how these high-level goals would manifest in practical regulation. Speaking at the Piper Sandler Global Exchange & Fintech Conference in New York, Selway confirmed that his division is actively developing a comprehensive framework for the listing and trading of tokenized securities.
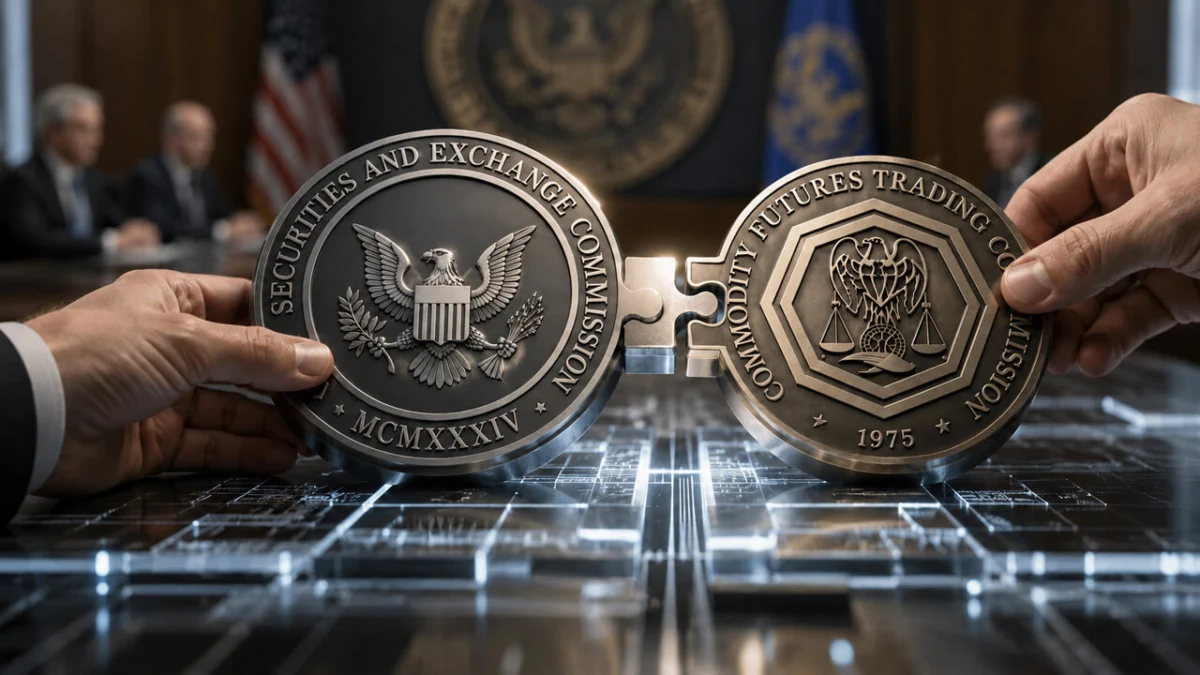
This development is being coordinated in tandem with the Commodity Futures Trading Commission (CFTC). Staff from both agencies are reportedly working to harmonize conflicting rulebooks regarding swap reporting, portfolio margining, and product definitions. This inter-agency cooperation is intended to resolve long-standing jurisdictional ambiguities that have historically hindered institutional participation in the digital asset space.
Selway introduced the principle of "innovation without arbitrage" as the guiding philosophy for this new framework. This principle posits that while the SEC is open to the efficiency gains offered by blockchain, it will not permit the technology to be used as a vehicle to bypass traditional regulatory obligations. The goal is to ensure that tokenized markets offer the same level of transparency and investor protection as traditional exchanges, while leveraging the unique capabilities of distributed ledger technology (DLT) to improve settlement speed and reduce operational costs.
The Narrative Shift as Regulatory Architecture
The SEC’s evolving language is viewed by legal experts not merely as a change in tone, but as a foundational component of a new regulatory architecture. Institutional adoption of blockchain has rarely been limited by the technology itself; rather, the primary obstacles have been legal uncertainty and the associated reputational risks. When the SEC’s primary interaction with the sector was through lawsuits, corporate compliance teams often viewed blockchain initiatives as high-risk exposure to speculative assets with unresolved legal status.
Jennie Levin, Chief Legal and Operating Officer at the Algorand Foundation and a former federal prosecutor, notes that the SEC’s new framing fundamentally changes the internal conversations within banks and asset managers. By reframing the technology as "market modernization," the SEC has provided a pathway for risk committees to evaluate blockchain as an infrastructure upgrade rather than a speculative investment.
"Compliance teams that were previously sitting on the sidelines are no longer being asked to underwrite a speculative asset class," Levin observed. "Instead, they are being asked to evaluate a more efficient, secure way to run the financial infrastructure they already operate every day." This shift is expected to accelerate the allocation of institutional capital toward on-chain financial products, as it provides an invitation to build within a recognized legal framework.
Chronology of the SEC’s Path to Modernization
The 2026–2030 Strategic Plan is the culmination of several years of incremental policy shifts and pilot programs. To understand the current trajectory, it is necessary to examine the timeline of events that moved blockchain from the periphery to the center of SEC policy:
- 2017–2022: The Enforcement Era: The SEC focused heavily on Initial Coin Offerings (ICOs) and secondary market trading of tokens, utilizing the Howey Test to determine security status. This period was characterized by high-profile litigation against firms like Ripple and various exchange platforms.
- January 2024: Spot Bitcoin ETF Approvals: The approval of spot Bitcoin Exchange-Traded Funds marked a turning point in institutional accessibility, forcing the agency to create a standardized path for digital asset-linked products.
- March–April 2026: Major Exchange Integration: The SEC granted approvals allowing Nasdaq and the New York Stock Exchange (NYSE) to begin trading tokenized versions of select equities alongside traditional shares. This move effectively brought blockchain "rails" into the heart of the U.S. equity market.
- April 2026: Self-Custody Guidance: An SEC staff statement provided a five-year "runway" for self-custody trading interfaces to obtain broker licenses, signaling a willingness to accommodate decentralized infrastructure within the existing regulatory perimeter.
- June 2026: The Strategic Plan and Selway’s Remarks: The formalization of blockchain as a five-year strategic priority and the announcement of a tokenized securities framework marked the transition to a proactive regulatory stance.
Programmable Compliance and Efficiency Gains
One of the most compelling arguments for the transition to on-chain markets is the concept of "programmable compliance." In traditional financial markets, compliance is often a manual, reactive process involving multiple layers of reconciliation between intermediaries. Settlement cycles (such as T+1 or T+2) exist largely because of the time required for these intermediaries to verify transactions and update their respective ledgers.
On a public ledger, compliance can be shifted from a post-trade manual check to an automated, protocol-level requirement. Features such as transfer restrictions, investor "allow lists," and freeze-and-clawback controls can be embedded directly into the smart contracts of the assets themselves. This means that a transaction cannot be executed unless it meets all regulatory parameters defined in the code.
Levin argues that this capability renders the "regulatory arbitrage" argument obsolete. "The real inefficiencies in traditional markets are fragmented settlement infrastructure and the reconciliation layers built on top of it," she stated. "A public ledger does not need legal shortcuts to outperform that system." When compliance is a property of the asset itself, the goals of market efficiency and investor protection no longer conflict; they become mutually reinforcing.
Legislative Catalysts: The CLARITY Act
While the SEC’s strategic plan provides a roadmap for administrative policy, the ultimate stability of the sector depends on statutory backing from Congress. The "CLARITY Act" (Clarifying Lawful Oversight of Crypto Assets and Regulatory Infrastructure and Technology) represents the most significant legislative effort to date to provide this foundation.
The CLARITY Act passed the House of Representatives with a bipartisan vote of 294-134 in July 2025 and cleared the Senate Banking Committee with a 15-9 vote in May 2026. As of early June 2026, the bill has been placed on the Senate Legislative Calendar. It requires 60 votes on the floor to pass before the August recess.
The legislation is designed to codify a unified token taxonomy, clearly defining which assets fall under the jurisdiction of the SEC and which belong to the CFTC. This would eliminate the "structural paralysis" that has historically caused institutional projects to stall during legal review. However, the timeline for passage remains tight. Market analysts at Galaxy Digital recently adjusted the odds of the bill passing in 2026 to 60%, down from 75%, citing intense scheduling pressure on the Senate floor. Polymarket participants currently price the likelihood of passage in the mid-50% range.
Implications for the Future of Financial Infrastructure
The SEC’s Strategic Plan for 2026-2030 suggests that the future of the American financial system will be increasingly defined by its digital architecture. If the goals outlined in the plan are met, several key milestones are expected to follow:
- Formal Proposals for Tokenized Securities: The SEC is likely to issue formal rule-making proposals that define how tokenized stocks, bonds, and funds can be legally issued and traded on both traditional and decentralized venues.
- Harmonized SEC-CFTC Oversight: Continued joint efforts will likely lead to a unified reporting system for digital assets, reducing the compliance burden on firms that currently have to navigate two different sets of rules.
- Institutional Product Launches: With greater regulatory clarity, major banks are expected to move beyond pilot programs and launch full-scale tokenized deposit and settlement platforms on public or "permissioned-public" blockchain rails.
- Modernized Custody and Settlement: The SEC’s focus on custody suggests new guidance will be issued to help traditional custodians manage digital assets without violating capital requirement rules or safety-and-soundness standards.
The broader impact of this shift is a move away from the speculative "crypto" markets of the early 2020s toward a system where blockchain serves as the invisible plumbing for global finance. The primary beneficiaries of this evolution are expected to be infrastructure providers that prioritize compliance and institutions that can leverage the technology to reduce costs and increase transparency.
Ultimately, the SEC’s 2026–2030 roadmap indicates that the debate over whether blockchain has a place in the financial system is largely over. The focus has moved to how the technology can be harnessed to modernize that system while preserving the core tenets of investor protection and market integrity. For the financial industry, this provides the "predictable legal framework" necessary to move from experimentation to large-scale implementation. The next five years will likely determine if the SEC’s vision of a "revolutionized" financial infrastructure becomes the new global standard.